Related Experiment Video
Updated: Oct 19, 2025

Author Spotlight: Advancements in Multiplex Detection of Respiratory Viruses
Published on: November 10, 2023
Return connectedness among commodity and financial assets during the COVID-19 pandemic: Evidence from China and the
Xiafei Li1, Bo Li2, Guiwu Wei3
1School of Economics and Management, Southwest Jiaotong University, Chengdu, China.

Abstract:
In this paper, we explore the dynamics of the return connectedness among major commodity assets (crude oil, gold and corn) and financial assets (stock, bond and currency) in China and the US during recent COVID-19 pandemic by using the time-varying connectedness measurement introduced by Antonakakis et al. (2020). Firstly, we find that the total return connectedness of the US commodity and financial assets is stronger than that of the Chinese commodity and financial assets in most cases, and both of them increase rapidly after the outbreak of COVID-19. Secondly, gold is a net transmitter of return shocks in both the Chinese and the US markets before the burst of COVID-19 pandemic, while stock and currency become net transmitters of shocks in both markets after that. Thirdly, corn usually receives the shocks from other commodity and financial assets in both China and the US markets during the COVID-19 epidemic, and the shocks it receives peak during this period, making it the strongest net receiver of shocks. Fourthly, crude oil shifts from a net transmitter to a net receiver of shocks in China after the outbreak of COVID-19, but it remains to be a net transmitter of shocks in the US. Finally, bond changes from a net receiver to a net transmitter of shocks in China after the outbreak of the epidemic, but converts from a net transmitter to a net receiver of shock in the US. The interchangeable roles of the commodity and financial assets suggest flexible regulatory and portfolio allocation strategies should be applied by policy makers and investors.

Related Concept Videos
 00:52
Pareto Chart
The Pareto chart is named after the Italian economist Vilfredo Pareto, who described the Pareto...
 01:26
Equity Theory
 01:25
Importance of Need for Affiliation
 01:09
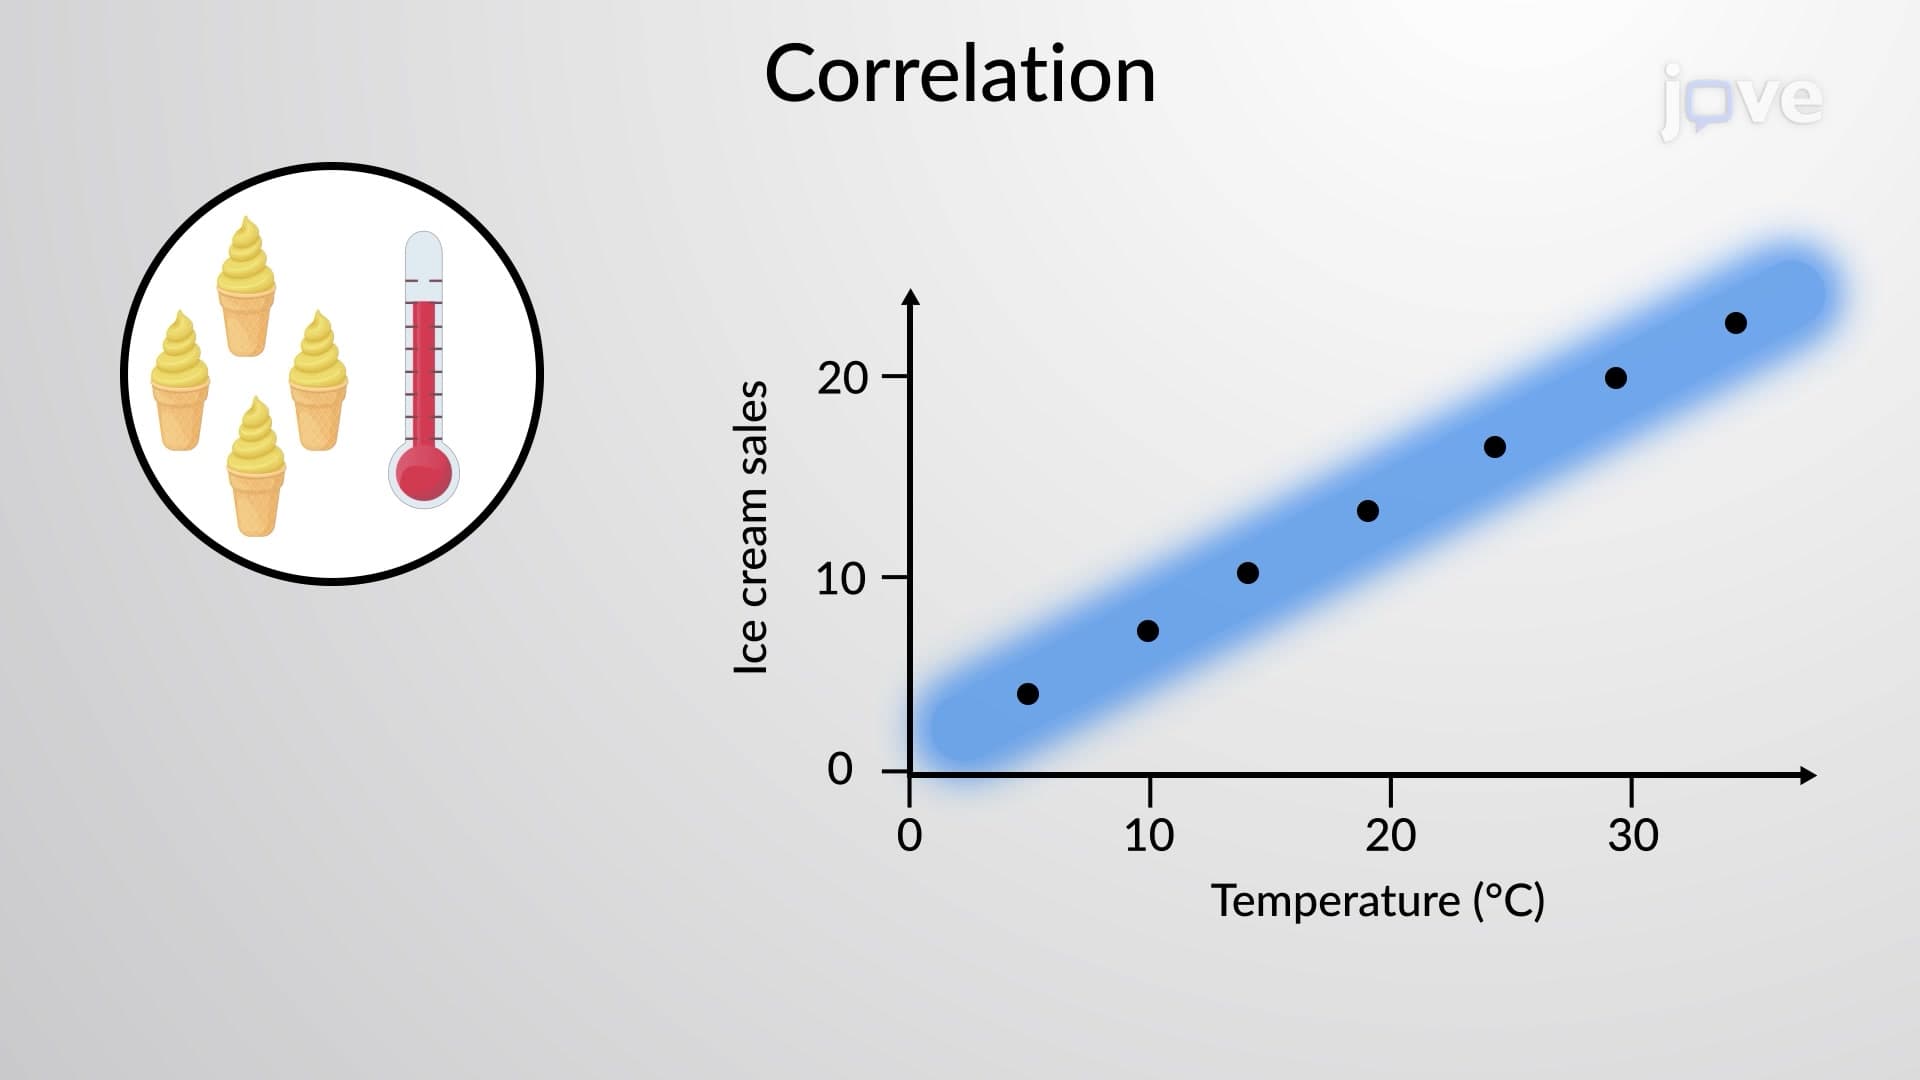
Correlation
Two variables, for example, a and b, are said to be positively correlated if both variables move in the same direction. In other words, a positive correlation exists between two variables, a and b, if:
 01:27
Relationship Growth
 02:06
Social Exchange Theory