Related Experiment Video
Updated: Oct 19, 2025

Author Spotlight: Advancements in Multiplex Detection of Respiratory Viruses
Published on: November 10, 2023
Quantifying Time-Frequency Co-movement Impact of COVID-19 on U.S. and China Stock Market Toward Investor Sentiment
Rui Nian1,2, Yijin Xu1, Qiang Yuan1,3
1School of Electronic Engineering, Ocean University of China, Qingdao, China.

Abstract:
The worldwide spread of COVID-19 dramatically influences the world economic landscape. In this paper, we have quantitatively investigated the time-frequency co-movement impact of COVID-19 on U.S. and China stock market since early 2020 in terms of daily observation from National Association of Securities Dealers Automated Quotations Index (NDX), Dow Jones Industrial Average (DJIA), Standard & Poor's 500 Index (SPX), Shanghai Securities Composite Index (SSEC), Shenzhen Securities Component Index (SZI), in favor of spatiotemporal interactions over investor sentiment index, and propose to explore the divisibility and the predictability to the volatility of stock market during the development of COVID-19. We integrate evidence yielded from wavelet coherence and phase difference to suggest the responses of stock market indexes to the COVID-19 epidemic in a long-term band, which could be roughly divided into three distinguished phases, namely, 30-75, 110-150, and 220-280 business days for China, and 80-125 and 160-175 after 290 business days for the U.S. At the first phase, the reason for the extreme volatility of stock market mainly attributed to the sudden emergence of the COVID-19 epidemic due to the pessimistic expectations from investors; China and U.S. stock market shared strongly negative correlation with the growing number of COVID-19 cases. At the second phase, the revitalization of stock market shared strong simultaneous moves but exhibited opposite responses to the COVID-19 impact on China and U.S. stock market; the former retained a significant negative correlation, while the latter turned to positively correlated throughout the period. At the third phase, the progress in vaccine development and economic stimulus began to impose forces to stock market; the vulnerability to COVID-19 diminished to some extent as the investor sentiment indexes rebounded. Finally, we attempted to initially establish a coarse-grained representation to stock market indexes and investor sentiment indexes, which demonstrated the homogenous spacial distribution in the vectorgraph after normalization and quantization, implying the strong consistency when filtering the frequent small fluctuations during the evolution of the COVID-19 pandemic, which might help insights into the prediction of possible status transition in stock market performance under the public health issues, potentially performing as the quantitative references in reasonably deducing the economic influences.
Related Concept Videos
 00:52
Pareto Chart
The Pareto chart is named after the Italian economist Vilfredo Pareto, who described the Pareto...
 01:15
Drug Concentration Versus Time Correlation
Two pivotal parameters are the minimum effective concentration (MEC) and the minimum toxic concentration (MTC). The MEC is the...
 01:04
Pie Chart
In a pie chart, the central angle, the arc length of each slice, and the area are directly proportional to the quantity or percentage it represents. Some real-world examples that can be depicted using pie charts include marks obtained by students...
 01:09
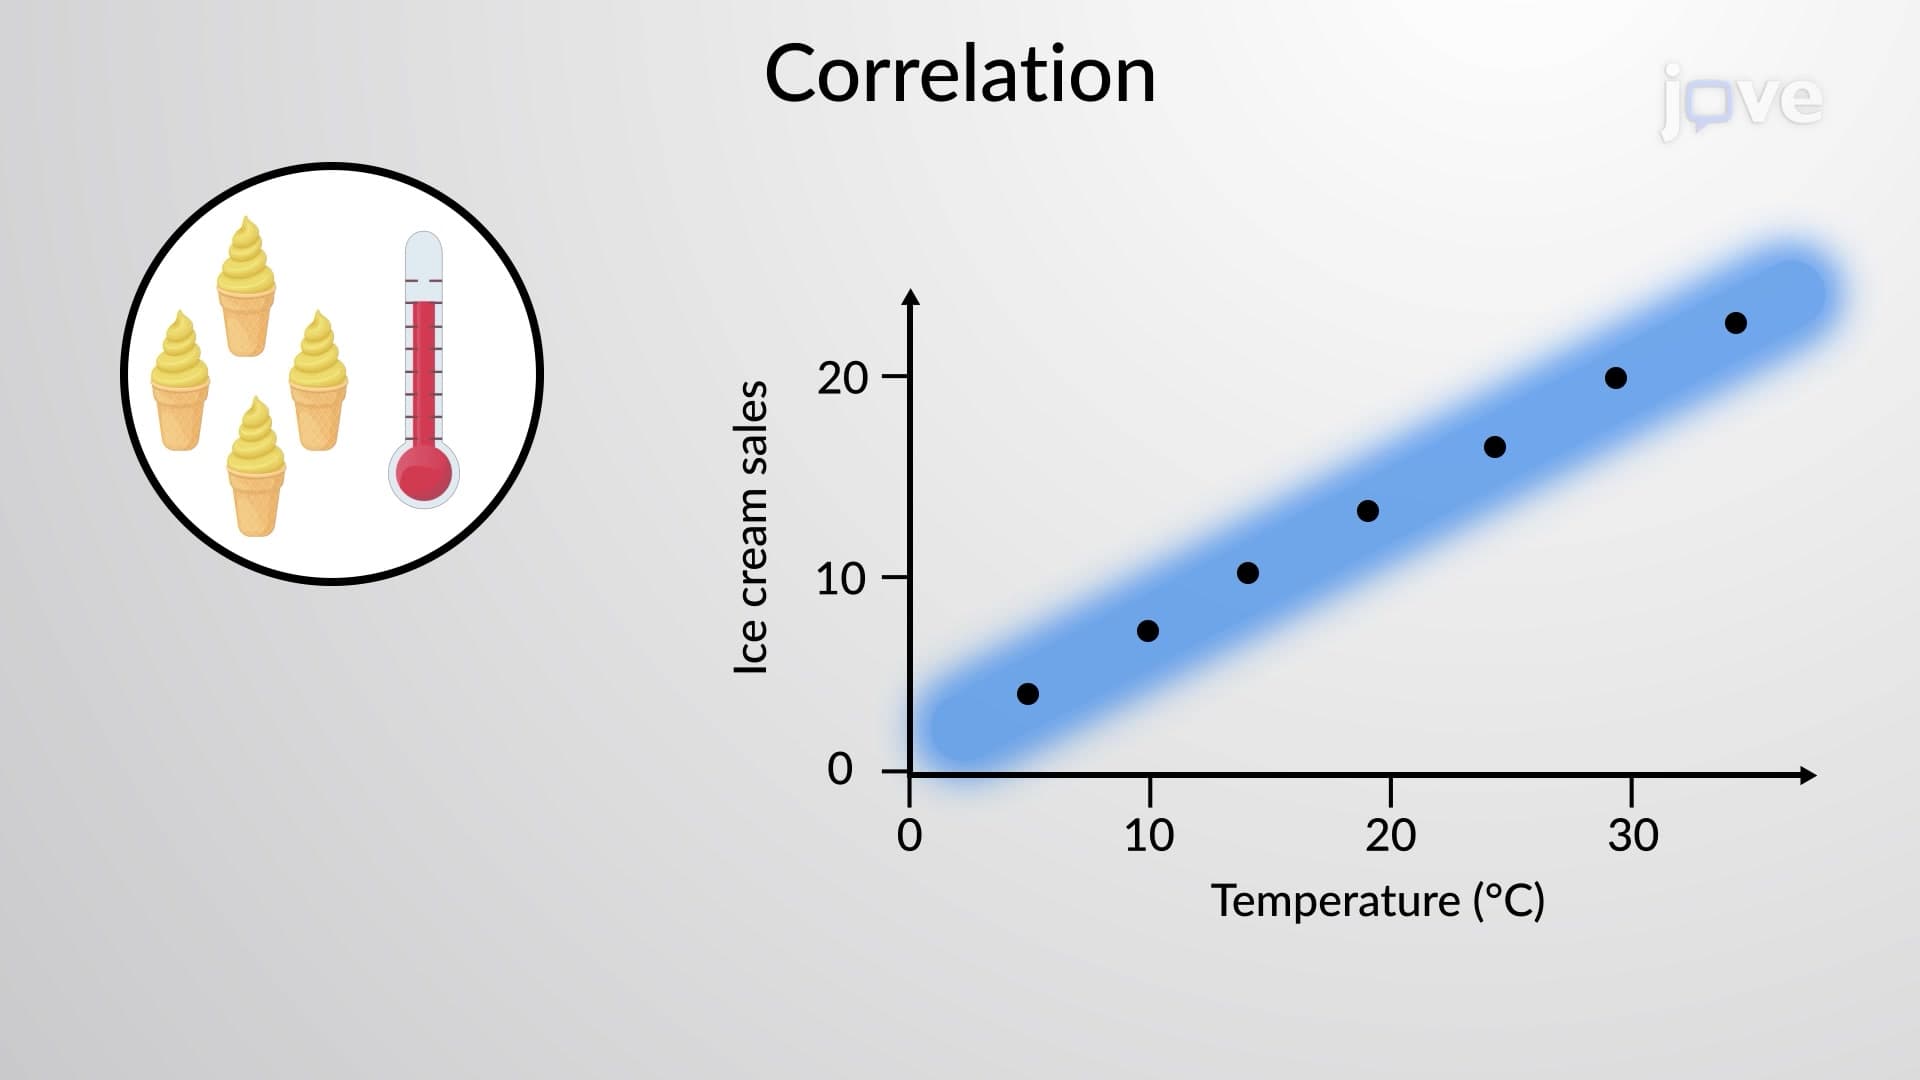
Correlation
Two variables, for example, a and b, are said to be positively correlated if both variables move in the same direction. In other words, a positive correlation exists between two variables, a and b, if:
 01:10
Central Tendency: Analysis
The mean is one such measure, calculated by totaling all values in a dataset and dividing by the number of values. For instance, the mean blood pressure reading (120, 130, 140, 150) would be 135. However, the mean can be affected by extreme values or outliers.
The median, another measure,...
 00:54
Time-Series Graph