Related Experiment Video
Updated: Oct 14, 2025
Enhanced Oil Recovery using a Combination of Biosurfactants
Published on: June 3, 2022
US QE and the Indian Bond Market
Moumita Paul1, Kalluru Siva Reddy1
1Institute of Politics and Economics, Pune, 411 004 India.

Abstract:
This paper examines the long- and short-run spillover effects of US quantitative easing (QE) on the benchmark 10-year Indian government bond (IGB) yield by Autoregressive Distributed Lag (ARDL) bounds testing co-integration approach using monthly data from September 2008 to June 2019. The results show that a 10%-point rise in US QE led to a 4 bp rise in yields. The counterfactual analysis shows that volatility of the yields would have been less without the QE. During the episodes of QE, the Reserve Bank of India (RBI) had to alter its policy rate and engage in open-market operations (OMOs) to simultaneously maintain liquidity in the system and reduce the volatility of interest rates. Spillover on the debt yield leads to mispricing of assets and partial loss of the monetary-policy autonomy of the RBI.
More Related Videos
 05:59
Author Spotlight: Advancing Antimicrobial Resistance Research with Innovative Approaches and Synthetic Compounds
Published on: September 27, 2024
 07:46
Author Spotlight: Improving Beef Cattle Nutrition and Production with a Focus on Feed Efficiency and Meat Quality Traits Through Advanced Biochemical and Molecular Assays
Published on: July 12, 2024
Related Concept Videos
 02:49
Bond Energies and Bond Lengths
 01:12
Bonding and Strength of Aggregate
 02:32
Bonding in Metals
 02:35
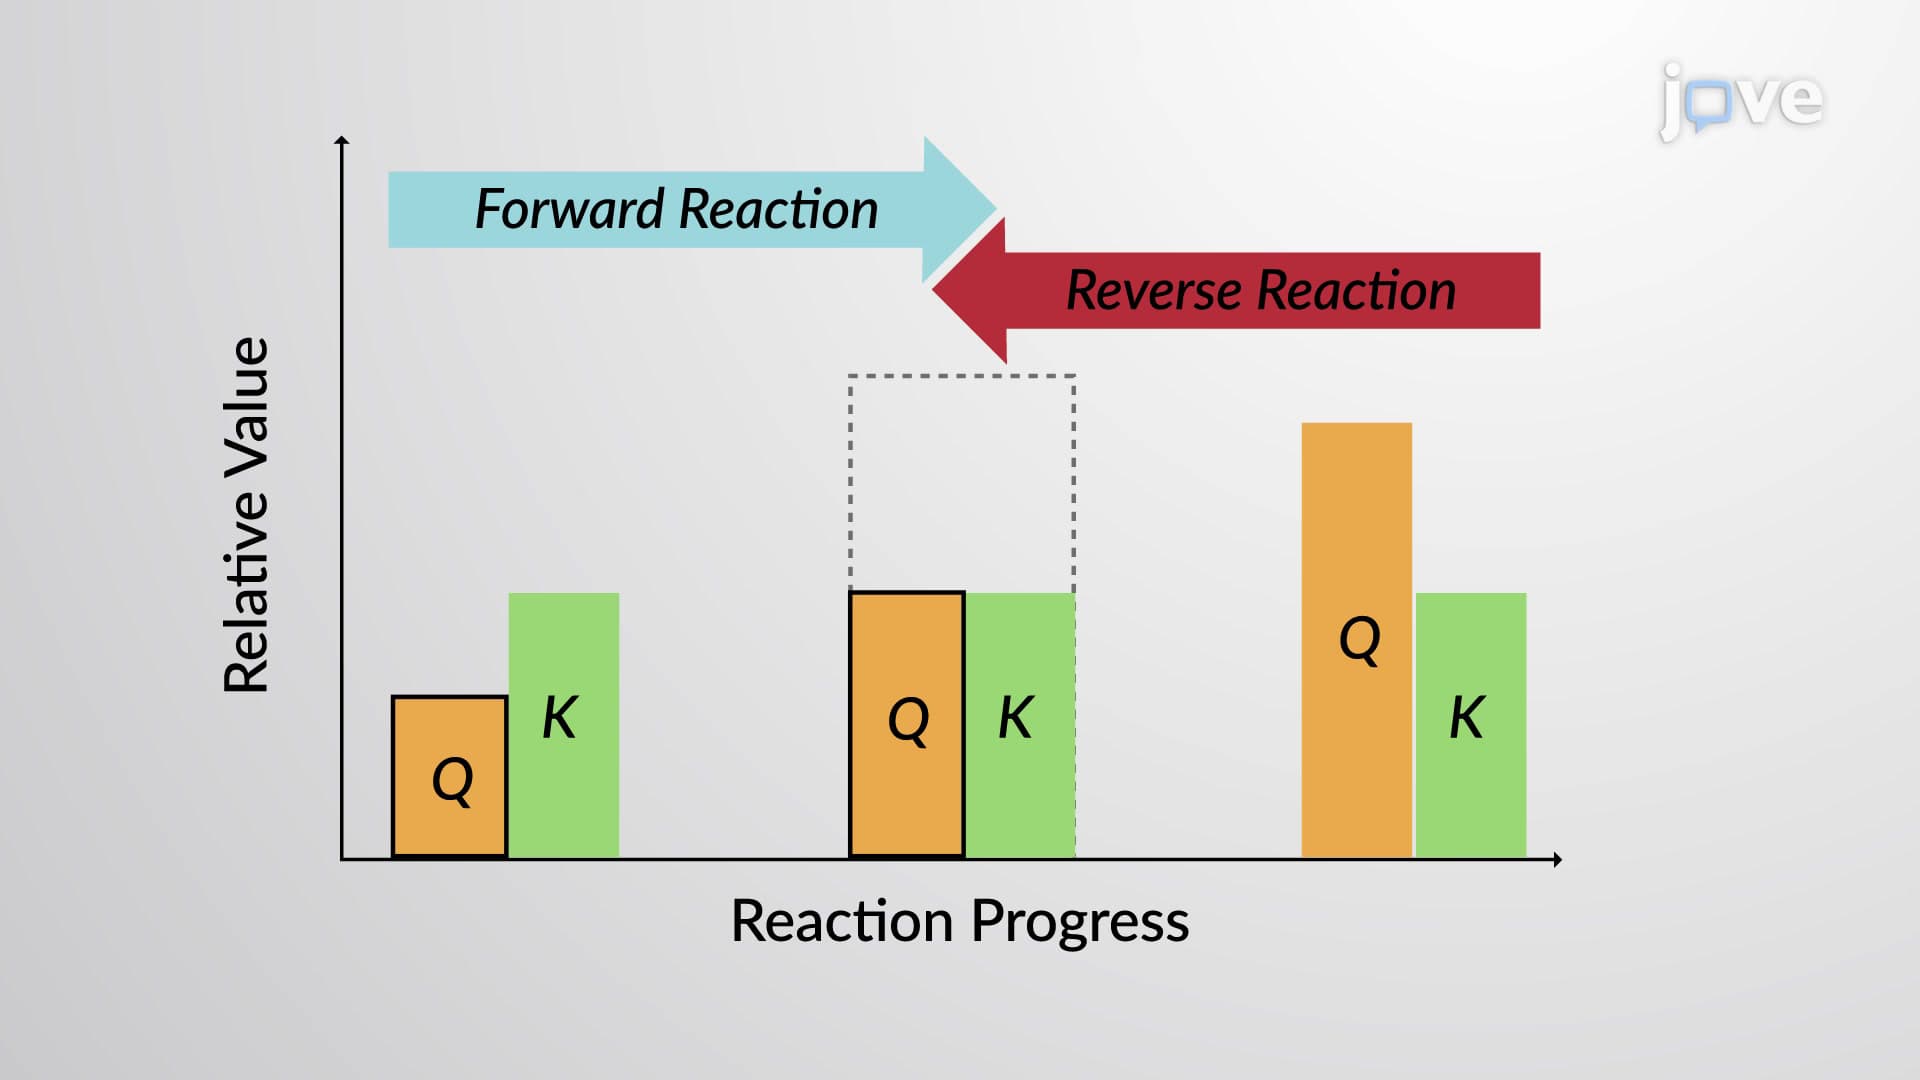
Reaction Quotient
 01:20
IR Spectrum Peak Intensity: Dipole Moment
 01:24
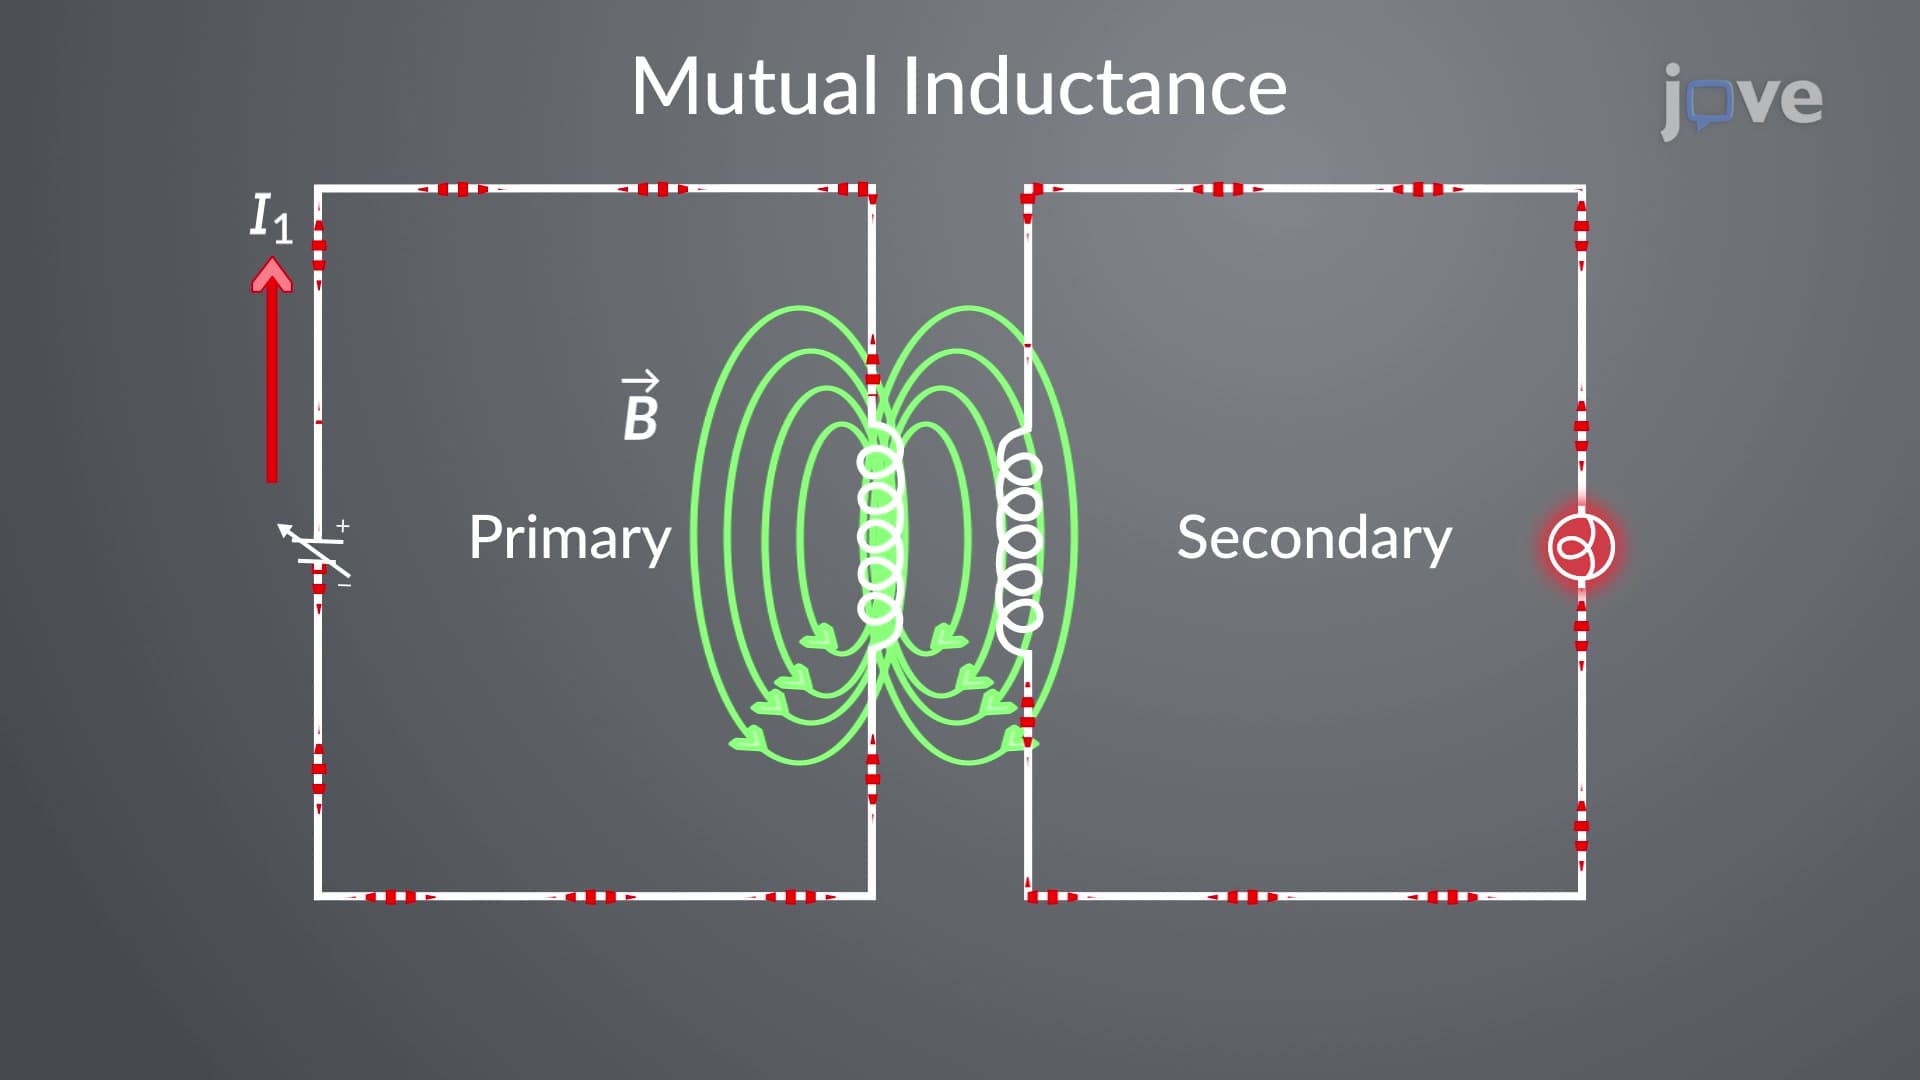
Mutual Inductance
When two circuits carrying time-varying currents are close to one another, the magnetic flux through each circuit varies because of the changing current in the other circuit. Consequently, an emf is induced in each circuit by the changing current in the other. Therefore, this type of emf is called...