Related Experiment Video
Updated: Oct 13, 2025
Large Scale Energy Efficient Sensor Network Routing Using a Quantum Processor Unit
Published on: September 8, 2023
QF-TraderNet: Intraday Trading via Deep Reinforcement With Quantum Price Levels Based Profit-And-Loss Control
Yifu Qiu1, Yitao Qiu1, Yicong Yuan1
1Department of Computer Science and Technology, Division of Science and Technology, BNU-HKBU United International College, Zhuhai, China.

Abstract:
Reinforcement Learning (RL) based machine trading attracts a rich profusion of interest. However, in the existing research, RL in the day-trade task suffers from the noisy financial movement in the short time scale, difficulty in order settlement, and expensive action search in a continuous-value space. This paper introduced an end-to-end RL intraday trading agent, namely QF-TraderNet, based on the quantum finance theory (QFT) and deep reinforcement learning. We proposed a novel design for the intraday RL trader's action space, inspired by the Quantum Price Levels (QPLs). Our action space design also brings the model a learnable profit-and-loss control strategy. QF-TraderNet composes two neural networks: 1) A long short term memory networks for the feature learning of financial time series; 2) a policy generator network (PGN) for generating the distribution of actions. The profitability and robustness of QF-TraderNet have been verified in multi-type financial datasets, including FOREX, metals, crude oil, and financial indices. The experimental results demonstrate that QF-TraderNet outperforms other baselines in terms of cumulative price returns and Sharpe Ratio, and the robustness in the acceidential market shift.
Related Concept Videos
 01:12
Observational Learning
 01:23
Reinforcement
Positive reinforcement occurs when a behavior is followed by the presentation of a rewarding stimulus, increasing the frequency of that behavior. For example:
 01:24
Reinforcement Schedules
Once a behavior is learned,...
 01:30
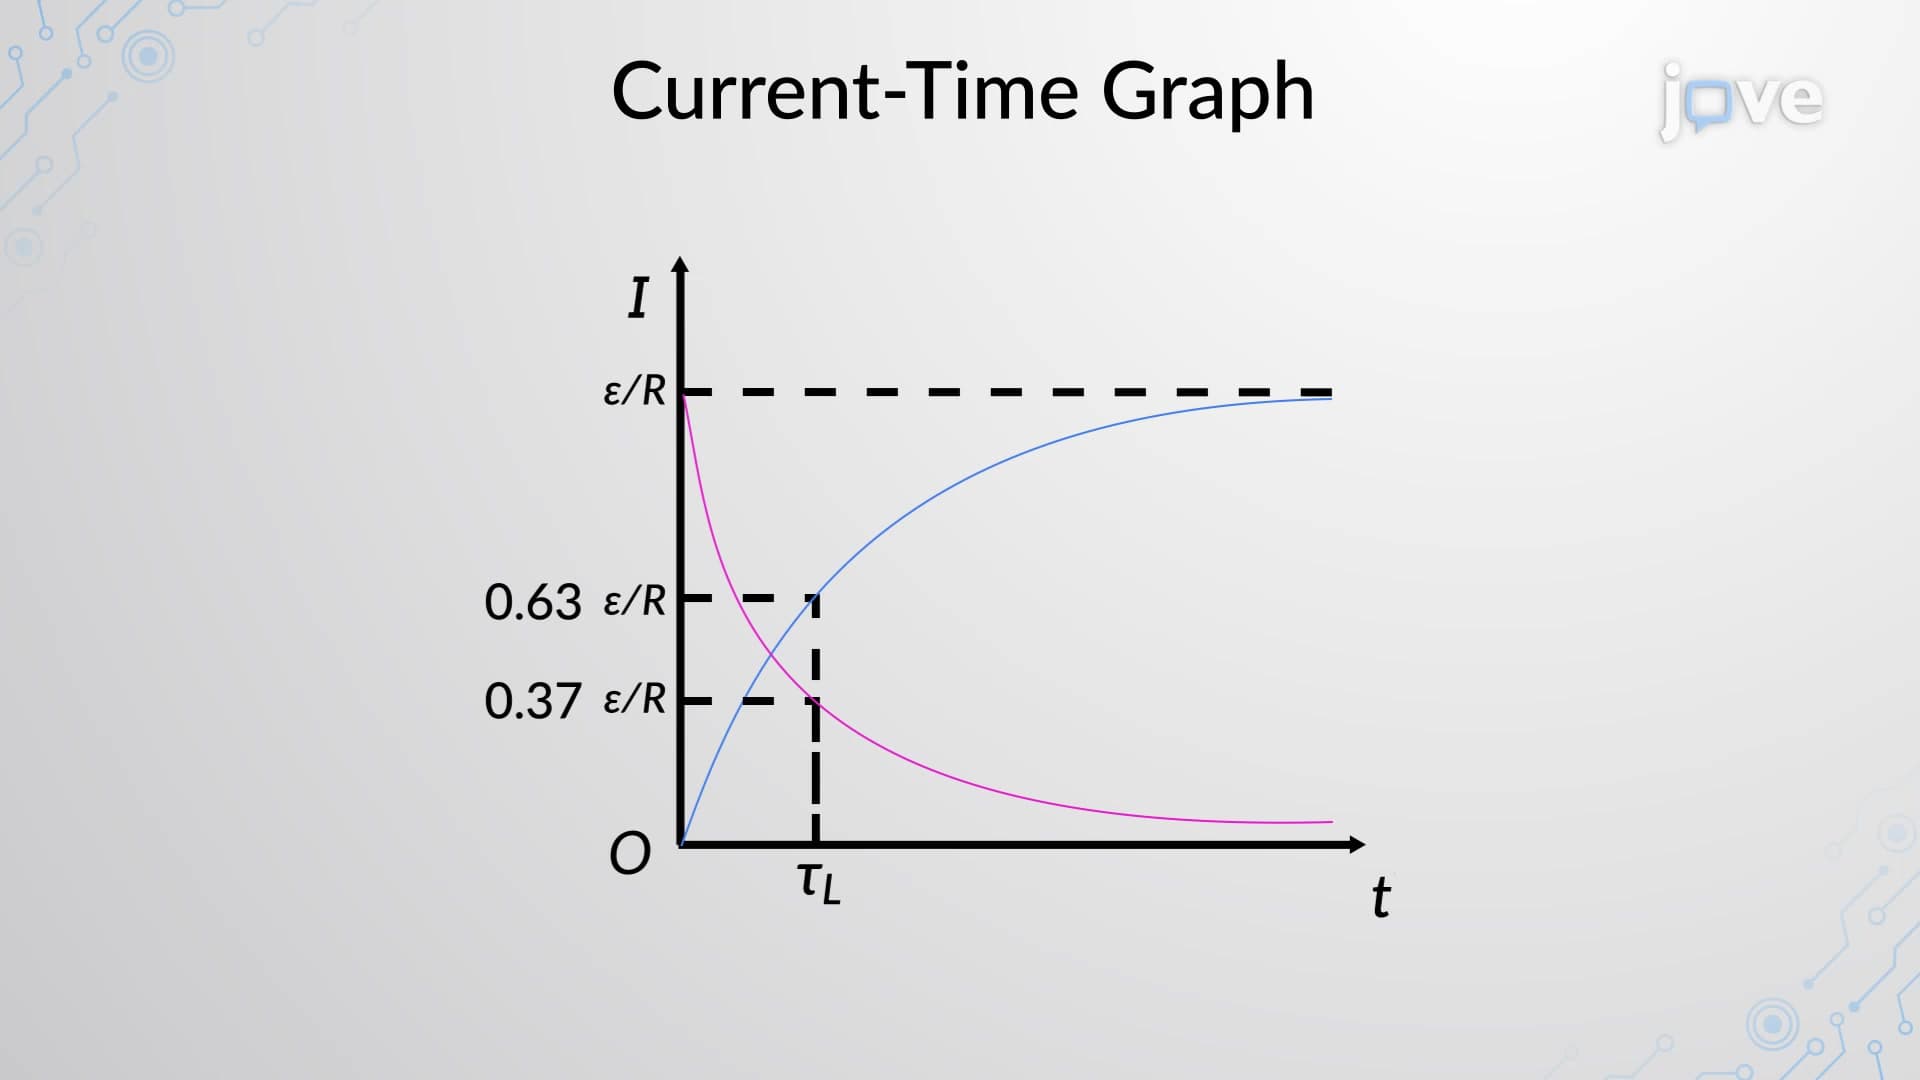
Current Growth And Decay In RL Circuits
 02:20
Dynamic Equilibrium
 01:37
Neural Regulation