Related Experiment Video
Updated: Oct 6, 2025

Author Spotlight: Advancements in Multiplex Detection of Respiratory Viruses
Published on: November 10, 2023
COVID-19 and instability of stock market performance: evidence from the U.S
Hui Hong1,2, Zhicun Bian3, Chien-Chiang Lee1,2
1Research Center for Central China Economic and Social Development, Nanchang University, Nanchang, Jiangxi China.

Abstract:
The effect of COVID-19 on stock market performance has important implications for both financial theory and practice. This paper examines the relationship between COVID-19 and the instability of both stock return predictability and price volatility in the U.S over the period January 1st, 2019 to June 30th, 2020 by using the methodologies of Bai and Perron (Econometrica 66:47-78, 1998. 10.2307/2998540; J Appl Econo 18:1-22, 2003. 10.1002/jae.659), Elliot and Muller (Optimal testing general breaking processes in linear time series models. University of California at San Diego Economic Working Paper, 2004), and Xu (J Econ 173:126-142, 2013. 10.1016/j.jeconom.2012.11.001). The results highlight a single break in return predictability and price volatility of both S&P 500 and DJIA. The timing of the break is consistent with the COVID-19 outbreak, or more specifically the stock selling-offs by the U.S. senate committee members before COVID-19 crashed the market. Furthermore, return predictability and price volatility significantly increased following the derived break. The findings suggest that the pandemic crisis was associated with market inefficiency, creating profitable opportunities for traders and speculators. Furthermore, it also induced income and wealth inequality between market participants with plenty of liquidity at hand and those short of funds.
More Related Videos
Related Concept Videos
 01:25
Interpreting Run Charts
 02:26
Ecological Disturbance
 01:26
Equity Theory
 01:28
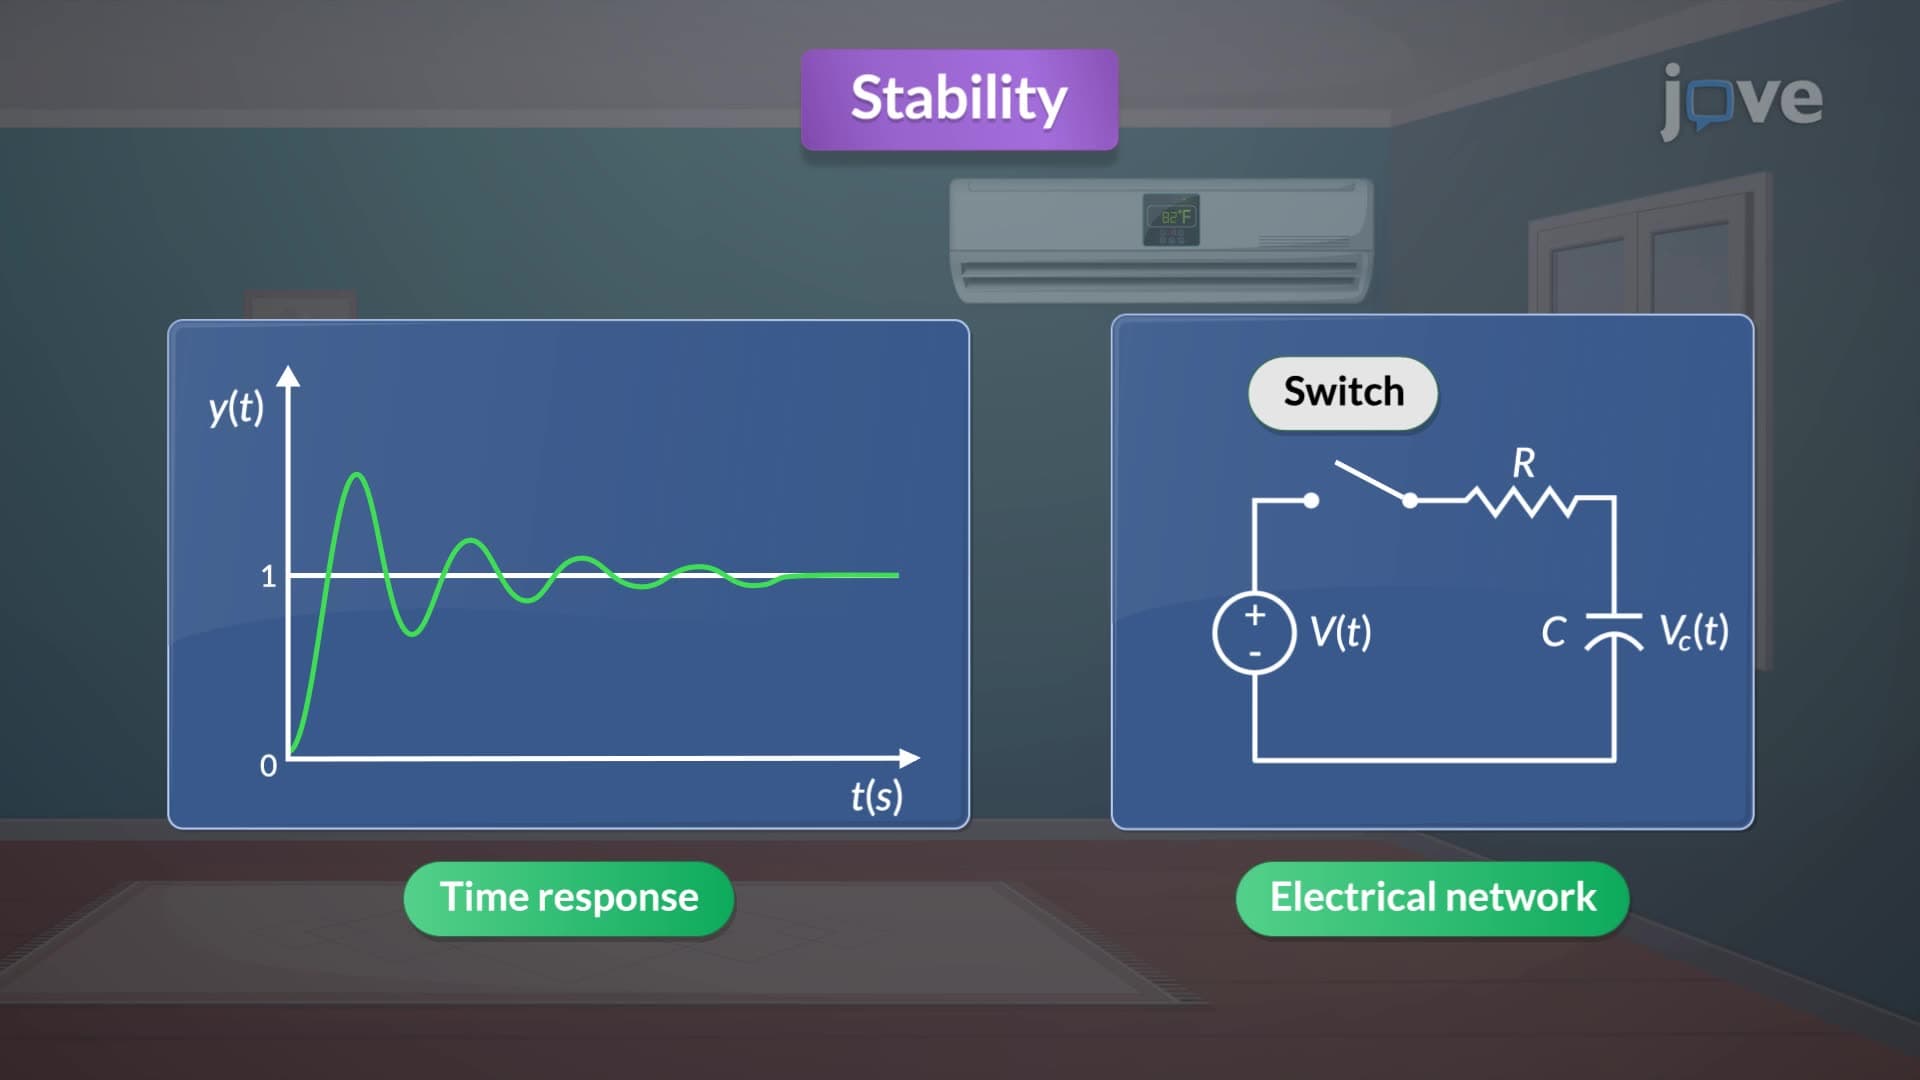
Stability
The stability of an LTI system is determined by the roots of its characteristic equation, known as poles. A system is stable if it produces a bounded...
 00:52
Pareto Chart
The Pareto chart is named after the Italian economist Vilfredo Pareto, who described the Pareto...
 01:09
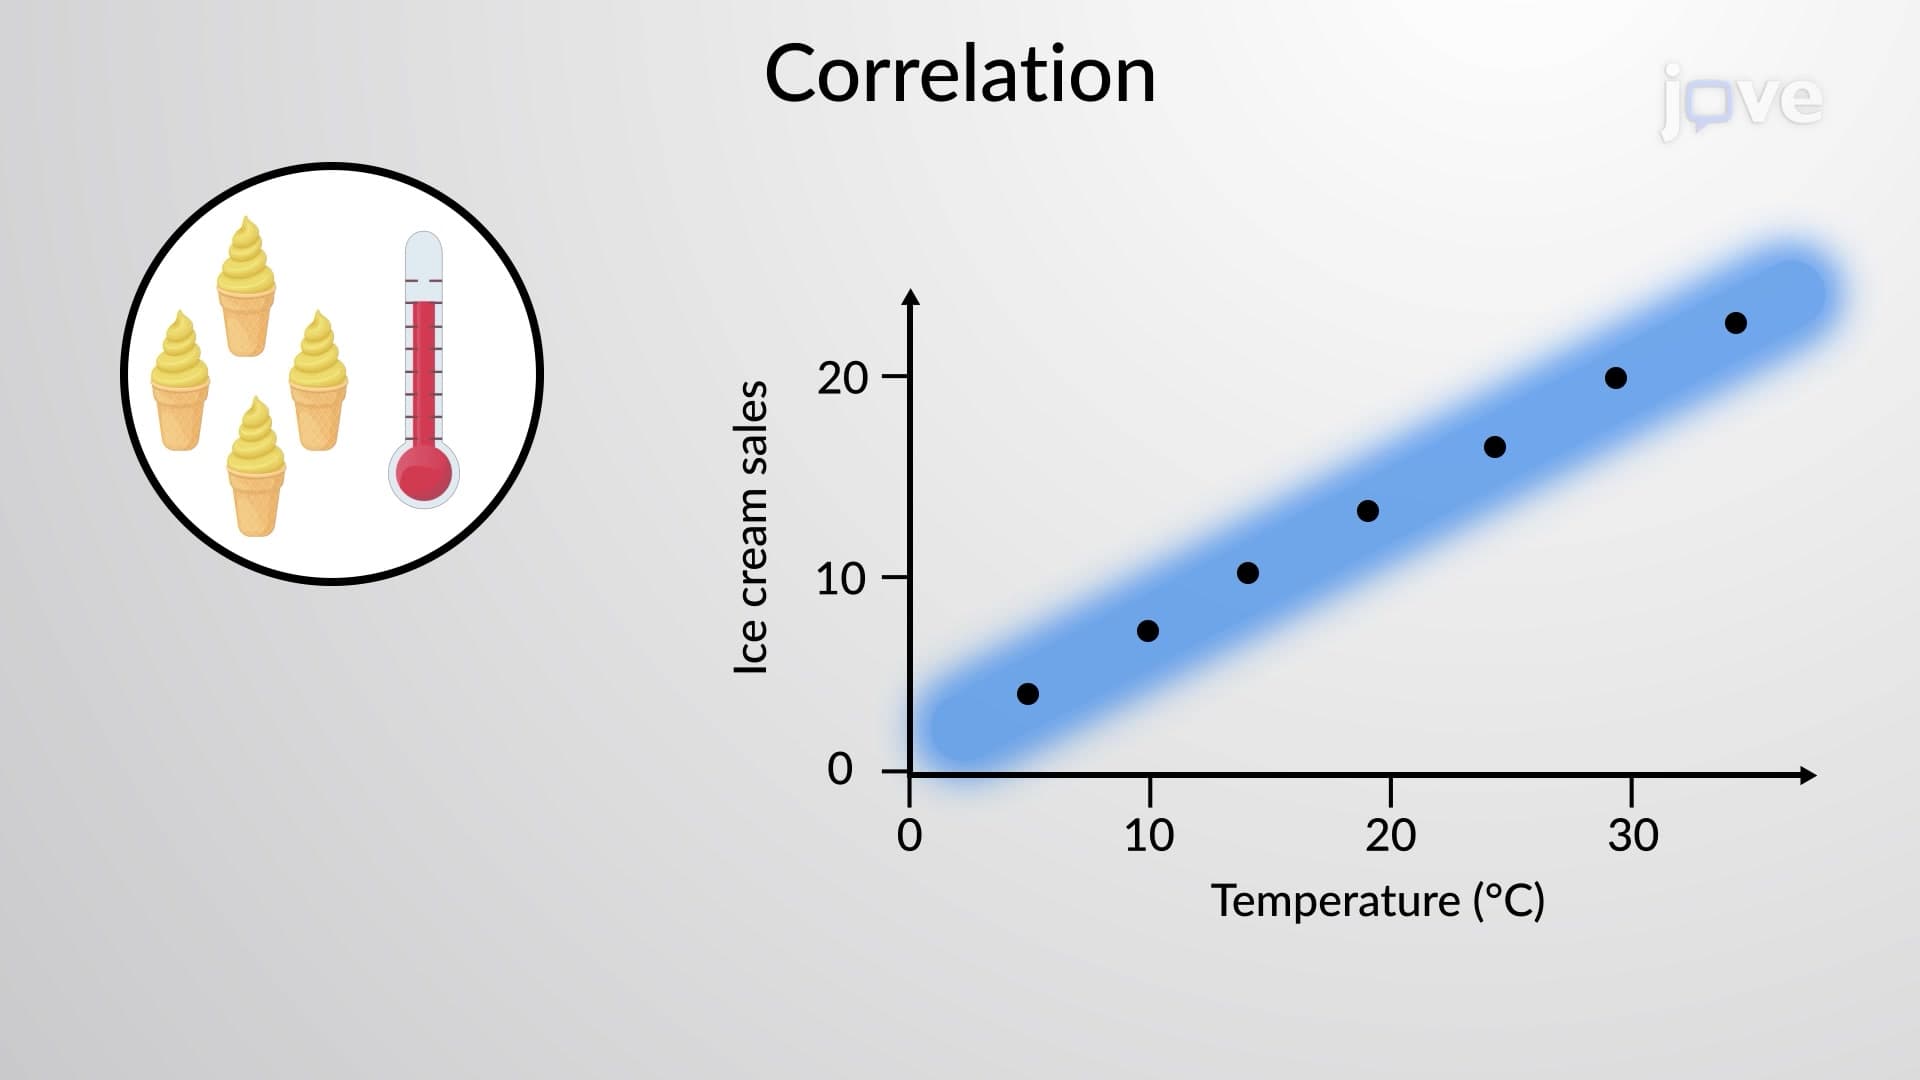
Correlation
Two variables, for example, a and b, are said to be positively correlated if both variables move in the same direction. In other words, a positive correlation exists between two variables, a and b, if: