Related Experiment Video
Updated: Oct 6, 2025

The Collective Trust Game: An Online Group Adaptation of the Trust Game Based on the HoneyComb Paradigm
Published on: October 20, 2022
High frequency multiscale relationships among major cryptocurrencies: portfolio management implications
Walid Mensi1, Mobeen Ur Rehman2, Muhammad Shafiullah3
1Department of Economics and Finance, College of Economics and Political Science, Sultan Qaboos University, Muscat, Oman.

Abstract:
This paper examines the high frequency multiscale relationships and nonlinear multiscale causality between Bitcoin, Ethereum, Monero, Dash, Ripple, and Litecoin. We apply nonlinear Granger causality and rolling window wavelet correlation (RWCC) to 15 min-data. Empirical RWCC results indicate mostly positive co-movements and long-term memory between the cryptocurrencies, especially between Bitcoin, Ethereum, and Monero. The nonlinear Granger causality tests reveal dual causation between most of the cryptocurrency pairs. We advance evidence to improve portfolio risk assessment, and hedging strategies.
Related Concept Videos
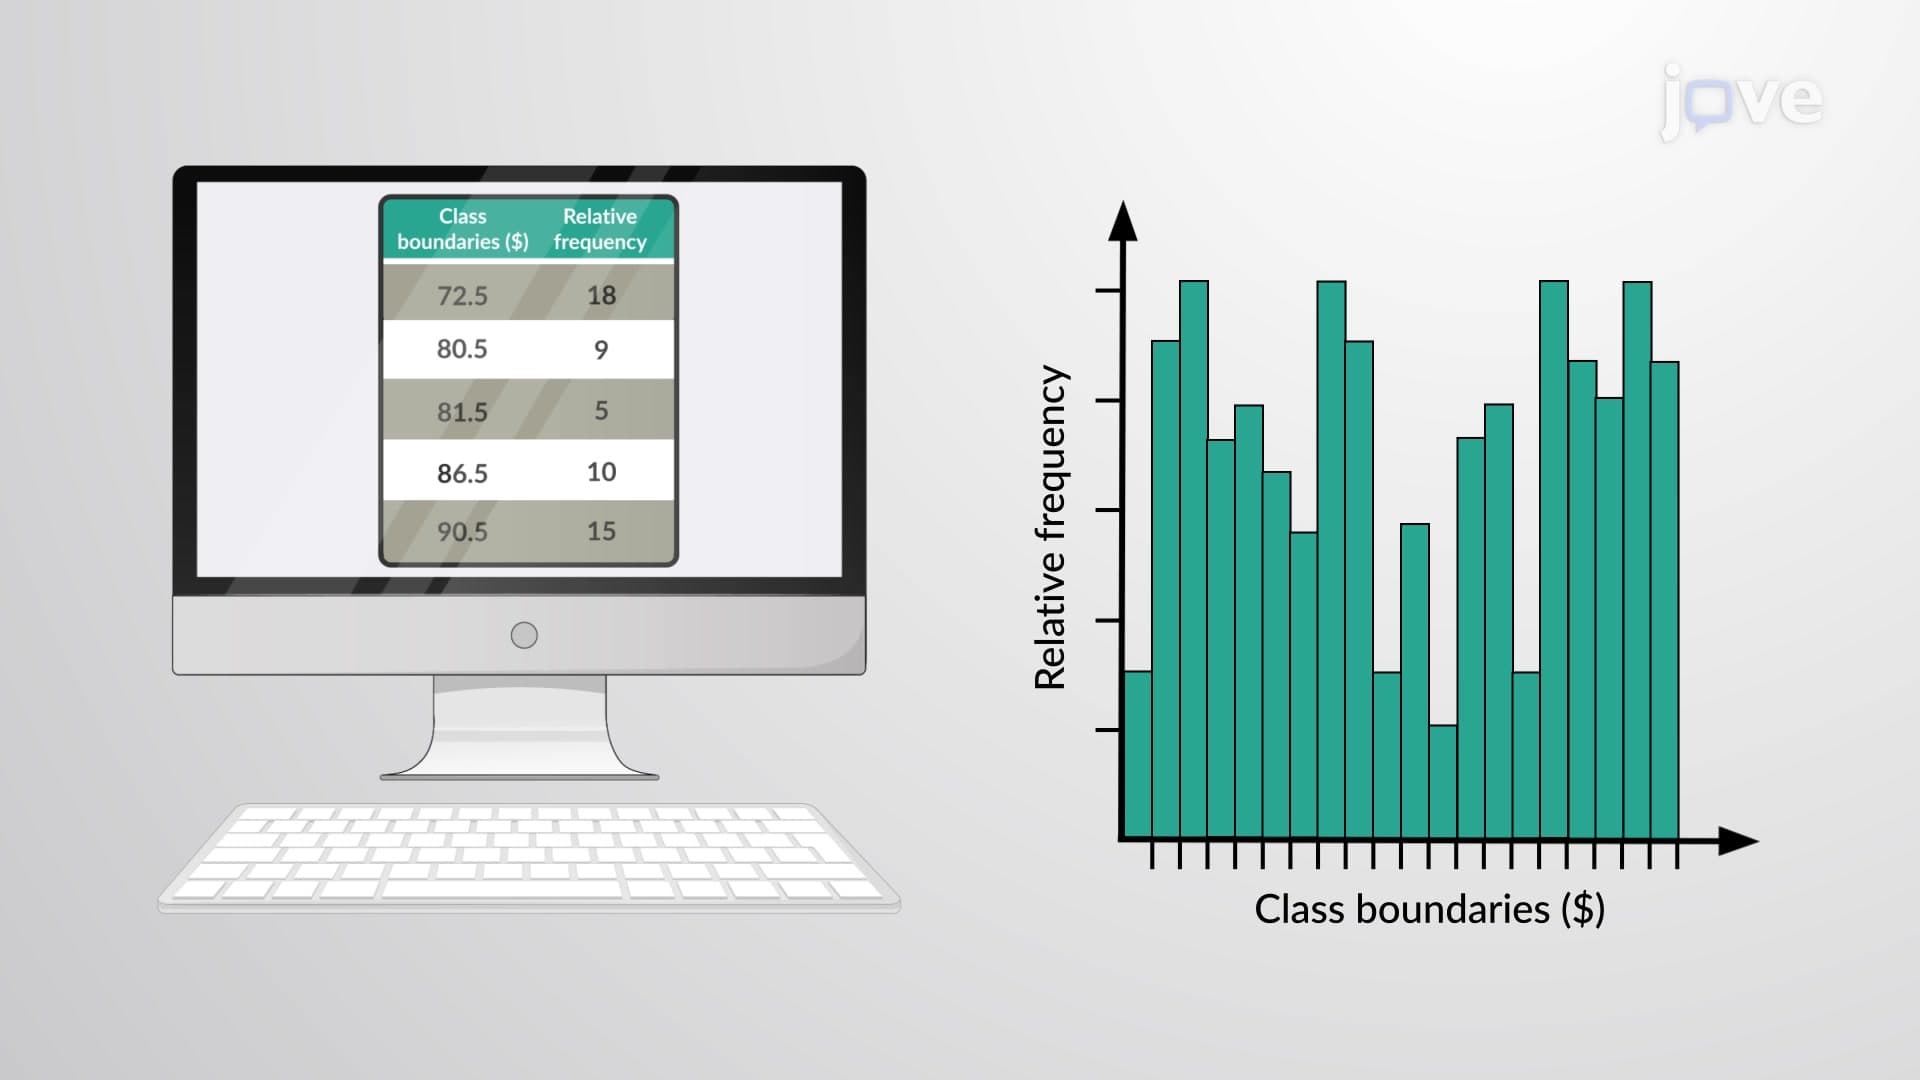 01:14
Relative Frequency Histogram
 01:14
Multicompartment Models: Overview
These models offer a more comprehensive representation of drug behavior in the body than one-compartment models. They accommodate the complexity of drug distribution,...
 01:15
Drug Concentration Versus Time Correlation
Two pivotal parameters are the minimum effective concentration (MEC) and the minimum toxic concentration (MTC). The MEC is the...
 01:26
Equity Theory
 01:26
Scaling
 01:07
Ogive Graph