Related Experiment Video
Updated: Oct 2, 2025


An R-Based Landscape Validation of a Competing Risk Model
Published on: September 16, 2022
Backtesting VaR under the COVID-19 sudden changes in volatility
Brenda Castillo1, Ángel León1, Trino-Manuel Ñíguez2
1Dept. Fundamentos del Análisis Económico (FAE), Universidad de Alicante, Alicante 03690, Spain.

Abstract:
We analyze the impact of the COVID-19 pandemic on the conditional variance of stock returns. We look at this effect from a global perspective, so we employ series of major stock market and sector indices. We use the Hansen's Skewed-t distribution with EGARCH extended to control for sudden changes in volatility. We oversee the COVID-19 effect on measures of downside risk such as the Value-at-Risk. Our results show that there is a significant sudden shift up in the return distribution variance post the announcement of the pandemic, which must be explained properly to obtain reliable measures for financial risk management.
More Related Videos
 13:04
Measuring the Subjective Value of Risky and Ambiguous Options using Experimental Economics and Functional MRI Methods
Published on: September 19, 2012
 10:46
A Method of Trigonometric Modelling of Seasonal Variation Demonstrated with Multiple Sclerosis Relapse Data
Published on: December 9, 2015
Related Concept Videos
 01:12
Relative Risk
 01:14
Standard Deviation of Calculated Results
A broad Gaussian distribution curve has a wider standard deviation, representing a data set with...
 01:03
Prediction Intervals
However, the point estimate is most likely not the exact value of the population parameter, but close to it. After calculating point estimates, we construct interval estimates, called confidence intervals or prediction intervals. This prediction interval comprises a range of values unlike the point estimate and is a better predictor of the observed sample value, y.
 01:15
Expected Value
 01:21
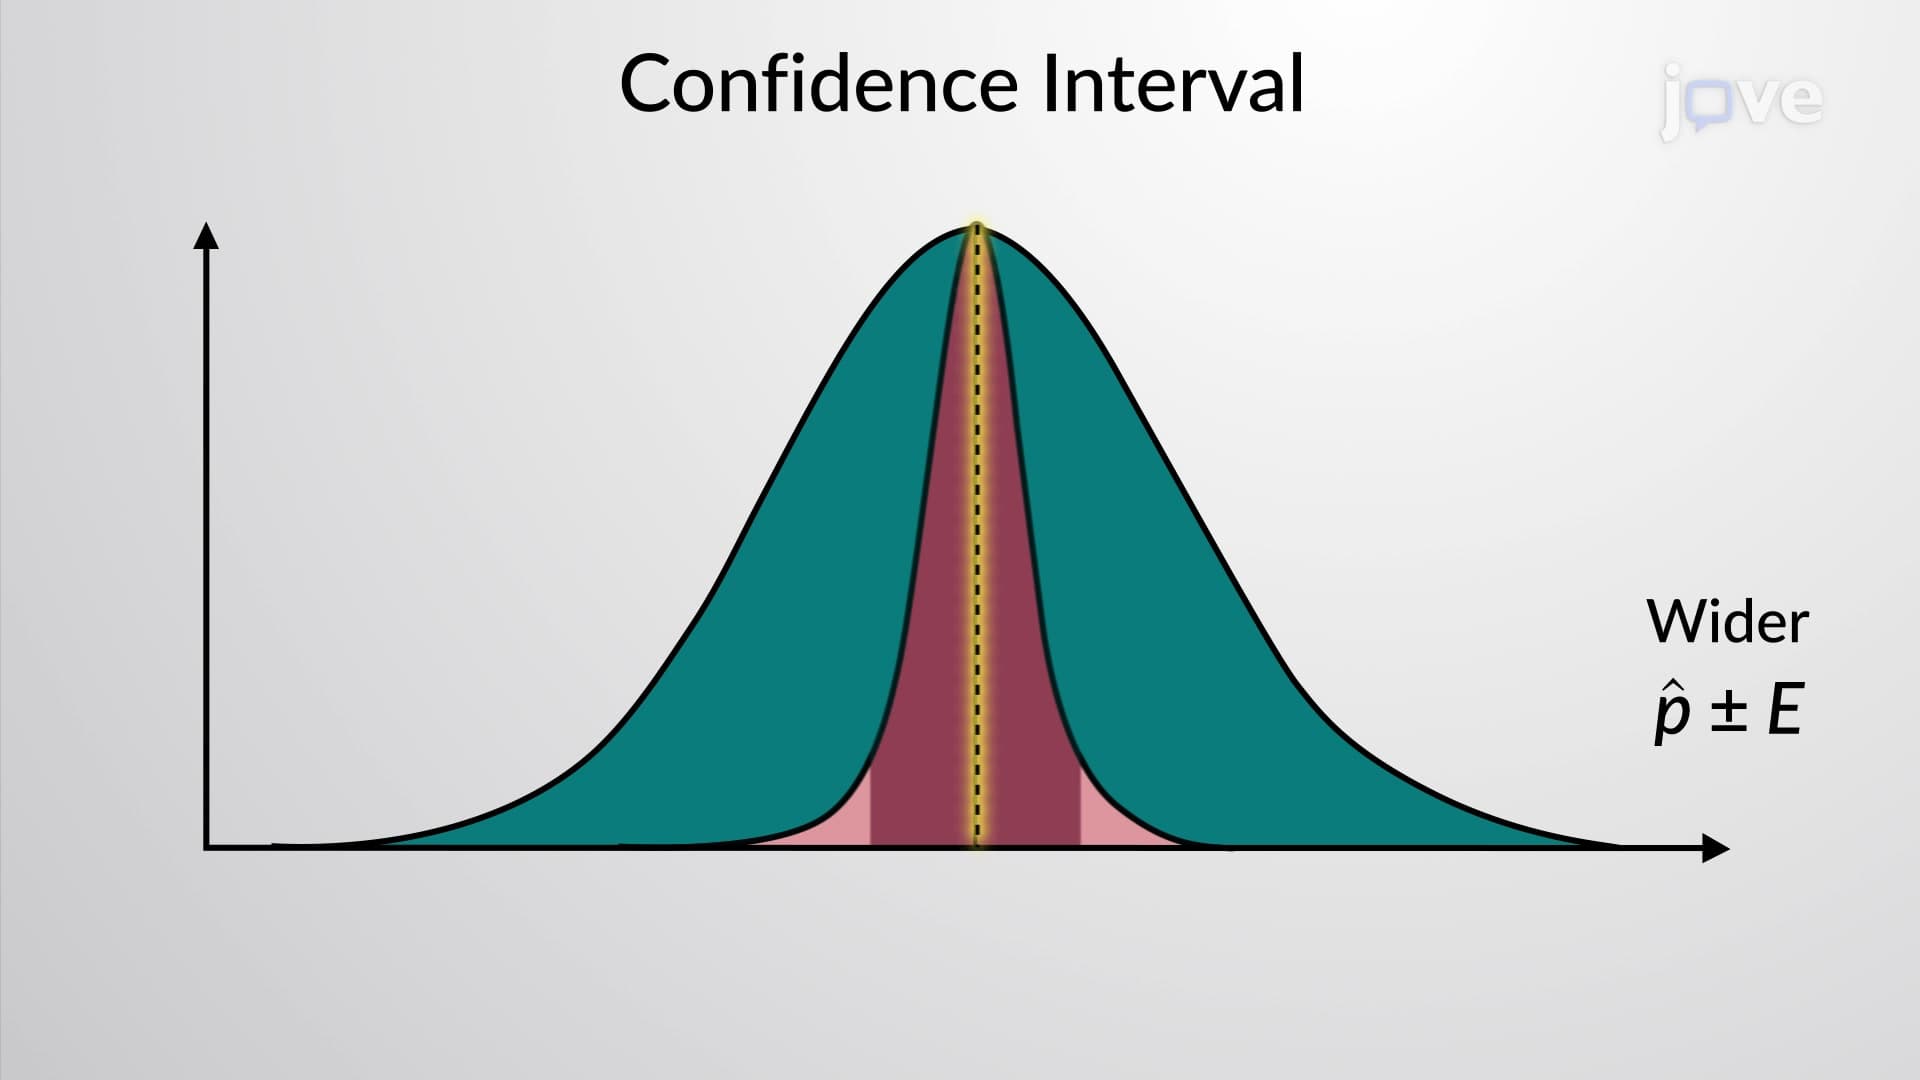
Confidence Intervals
A...
 01:11
Residuals and Least-Squares Property
If the observed data point lies above the line, the residual is positive, and the line underestimates the actual data value for y. If the observed data point lies below the line, the residual is negative, and the line overestimates the actual data value for y.
The process of fitting the best-fit...