Related Experiment Video
Updated: Sep 26, 2025

Identification of Disease-related Spatial Covariance Patterns using Neuroimaging Data
Published on: June 26, 2013
Eigenvalues of autocovariance matrix: A practical method to identify the Koopman eigenfrequencies
Yicun Zhen1, Bertrand Chapron1, Etienne Mémin2
1Institut Franais de Recherche pour l'Exploitation de la Mer, 29280 Plouzané, France.

Abstract:
To infer eigenvalues of the infinite-dimensional Koopman operator, we study the leading eigenvalues of the autocovariance matrix associated with a given observable of a dynamical system. For any observable f for which all the time-delayed autocovariance exist, we construct a Hilbert space H_{f} and a Koopman-like operator K that acts on H_{f}. We prove that the leading eigenvalues of the autocovariance matrix has one-to-one correspondence with the energy of f that is represented by the eigenvectors of K. The proof is associated to several representation theorems of isometric operators on a Hilbert space, and the weak-mixing property of the observables represented by the continuous spectrum. We also provide an alternative proof of the weakly mixing property. When f is an observable of an ergodic dynamical system which has a finite invariant measure μ, H_{f} coincides with closure in L^{2}(X,dμ) of Krylov subspace generated by f, and K coincides with the classical Koopman operator. The main theorem sheds light to the theoretical foundation of several semi-empirical methods, including singular spectrum analysis (SSA), data-adaptive harmonic analysis (DAHD), Hankel DMD, and Hankel alternative view of Koopman analysis (HAVOK). It shows that, when the system is ergodic and has finite invariant measure, the leading temporal empirical orthogonal functions indeed correspond to the Koopman eigenfrequencies. A theorem-based practical methodology is then proposed to identify the eigenfrequencies of K from a given time series. It builds on the fact that the convergence of the renormalized eigenvalues of the Gram matrix is a necessary and sufficient condition for the existence of K-eigenfrequencies. Numerical illustrating results on simple low dimensional systems and real interpolated ocean sea-surface height data are presented and discussed.

Related Concept Videos
 01:24
One-Compartment Open Model: Wagner-Nelson and Loo Riegelman Method for ka Estimation
On...
 01:08
Vector Algebra: Method of Components
In many applications, the magnitudes and directions of...
 01:08
Determination of Expected Frequency
 01:20
Kendall's Coefficient of Concordance
 01:14
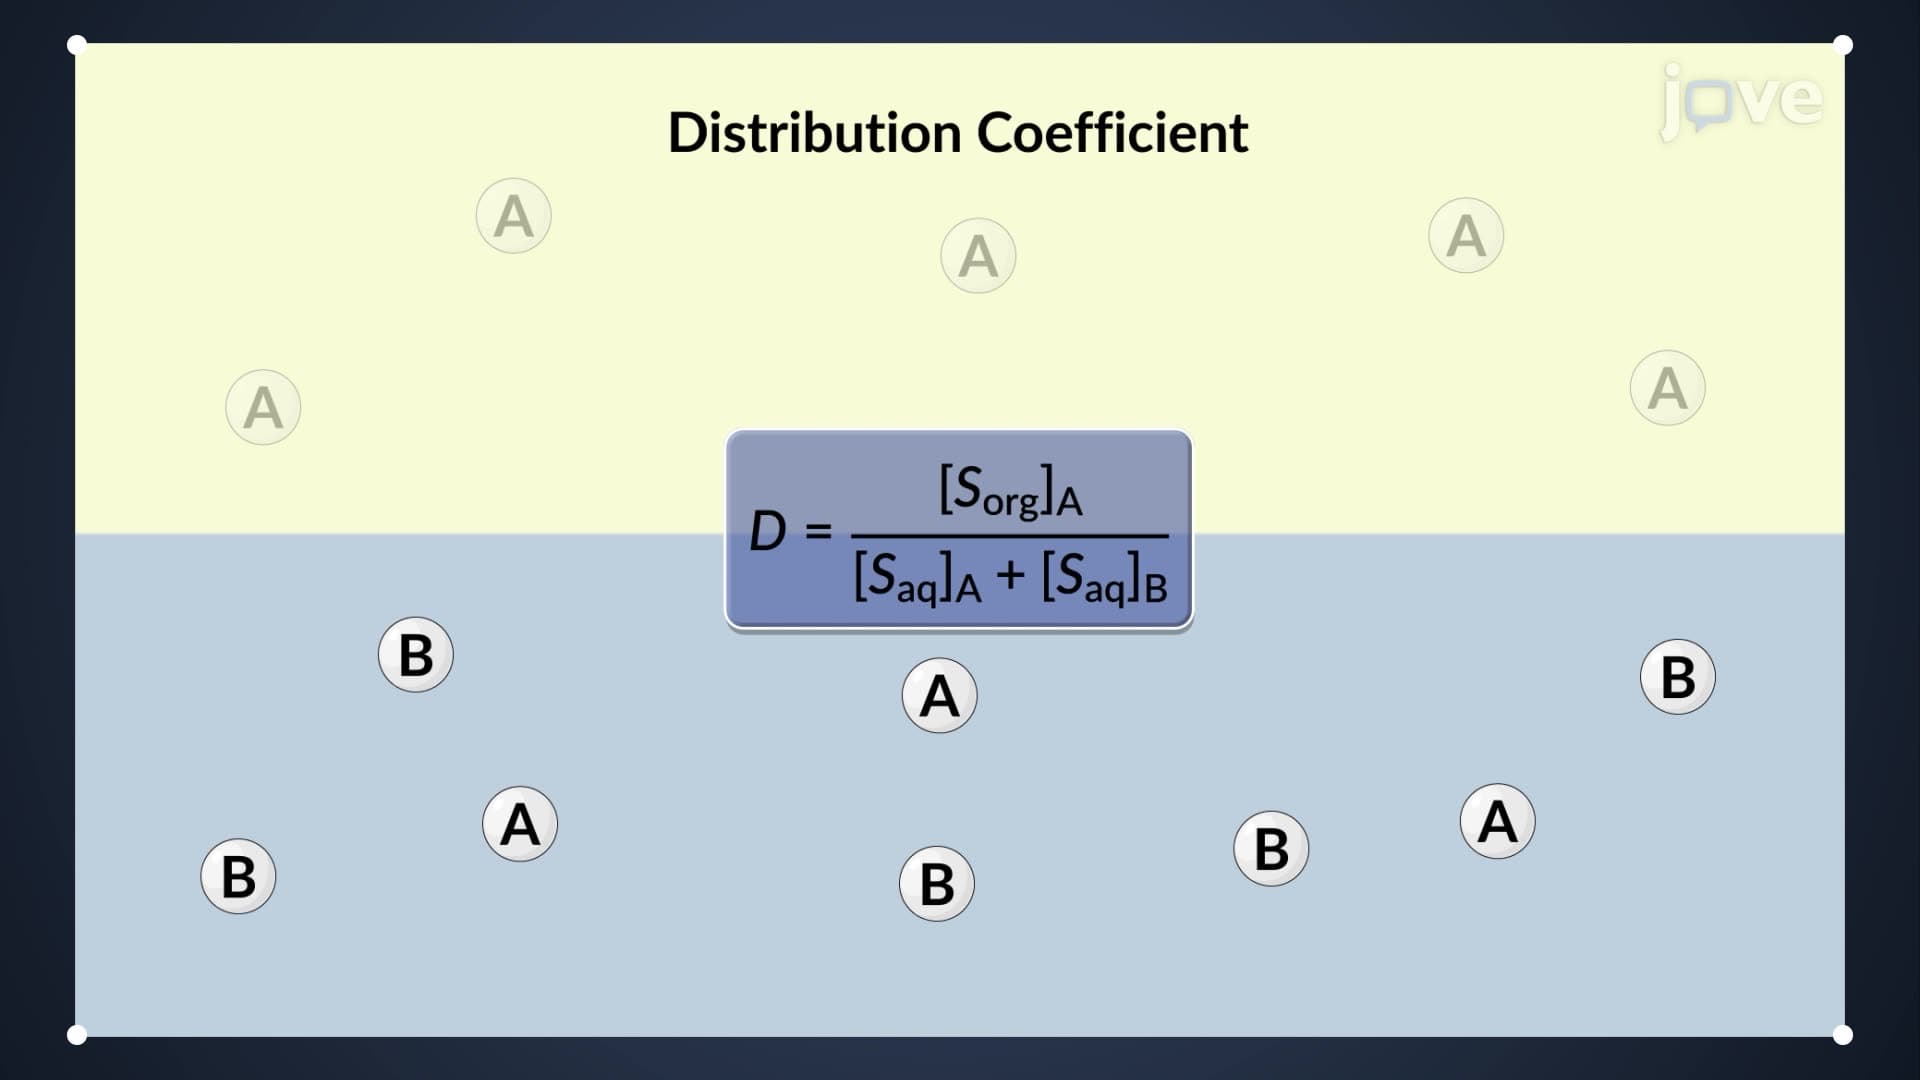
Extraction: Partition and Distribution Coefficients
For extracting a solute from an aqueous phase into an...
 01:12
Coefficient of Correlation
If you suspect a linear relationship between x and y, then r can measure how strong the linear relationship is.
What the VALUE of r tells us:
The value of r is always between –1 and +1: –1 ≤ r ≤ 1.
The size of the correlation r indicates the...