Related Experiment Video
Updated: Sep 26, 2025
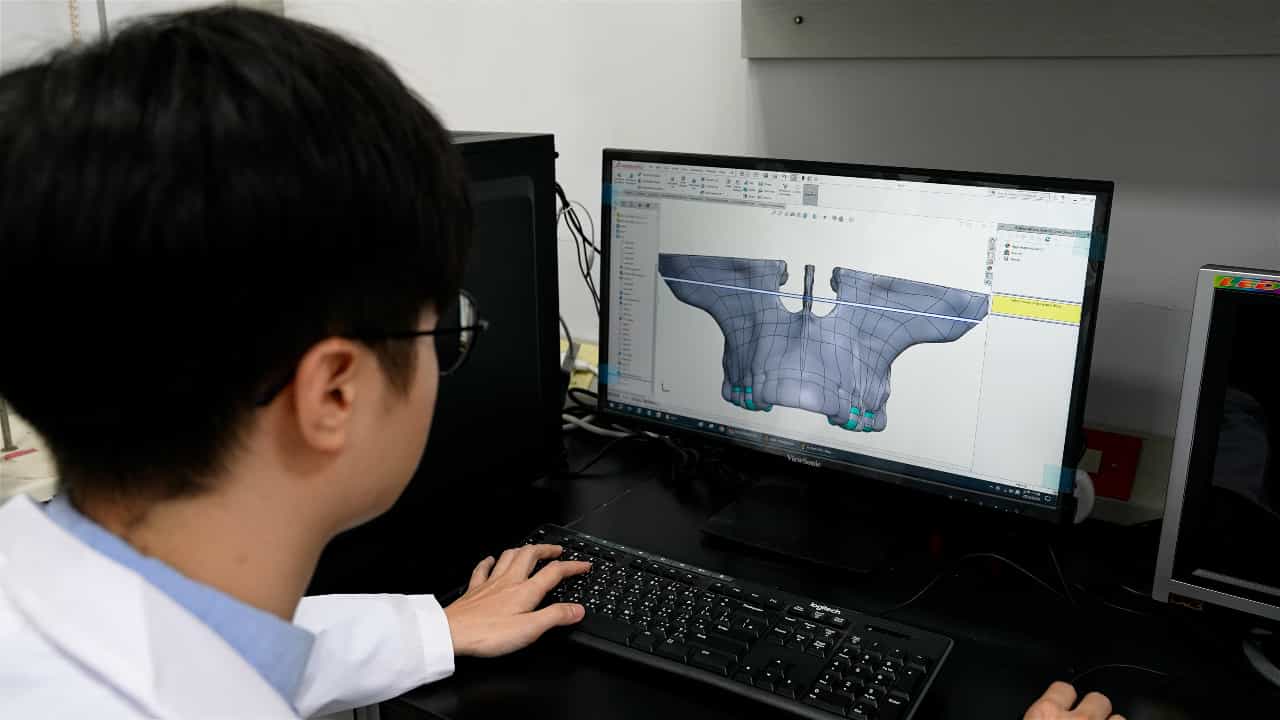

Author Spotlight: Development of a Novel Finite Element Analysis Model for Improved Orthognathic Surgical Techniques
Published on: October 20, 2023
RETRACTED ARTICLE: Modeling and prediction of KSE - 100 index closing based on news sentiments: an applications of
Asma Zaffar1, S M Aalim Hussain1
1Department of Mathematics, Sir Syed University of Engineering & Technology, Karachi, Pakistan.

Abstract:
The main financial markets of every country are stock exchange and consider as an imperative cause for the corporations to increase capital. The novelty of this study to explore machine learning techniques when applied to financial stock market data, and to understand how machine learning algorithms can be applied and compare the result with time series analysis to real lifetime series data and helpful for any investor. Investors are constantly reviewing past pricing history and using it to influence their future investment decisions. The another novelty of this study, using news sentiments, the values will be processed into lists displaying and representing the stock and predicting the future rates to describe the market, and to compare investments, which will help to avoid uncertainty amongst the investors regarding the stock index. Using artificial neural network technique for prediction for KSE 100 index data on closing day. In this regard, six months' data cycle trained the data and apply the statistical interference using a ARMA (p, q) model to calculate numerical result. The novelty of this study to find the relation between them either they are strongly correlated or not, using machine learning techniques and ARMA (p, q) process to forecast the behavior KSE 100 index cycles. The adequacy of model describes via least values Akaike information criterion (AIC), Bayesian Schwarz information criterion (SIC) and Hannan Quinn information criterion (HIC). Durbin- Watson (DW) test is also applied. DW values (< 2) shows that all cycles are strongly correlated. Most of the KSE-100 index cycles expresses that the appropriate model is ARMA (2,1). Cycle's 2nd,3rd,4th and 5th shows that ARMA (3,1) is best fitted. Cycle 8th is shows ARMA (1,1) best fit and cycle 12th shows that the most appropriate model is ARMA (4,1). Diagnostic checking tests like Root Mean Squared Error (RMSE), Mean Absolute Error (MAE), Mean Absolute Percentage Error (MAPE) and Theil's U-Statistics are used to predict KSE-100 index cycles. Theil's U-Statistics demonstrate that each cycle is strongly correlated to previous one.
Related Concept Videos
 01:29
Econometric Views (EViews)
 01:03
Prediction Intervals
However, the point estimate is most likely not the exact value of the population parameter, but close to it. After calculating point estimates, we construct interval estimates, called confidence intervals or prediction intervals. This prediction interval comprises a range of values unlike the point estimate and is a better predictor of the observed sample value, y.
 01:29
Mechanistic Models: Compartment Models in Algorithms for Numerical Problem Solving
In individual population analyses, different algorithms are employed, such as Cauchy's method, which uses a...
 01:23
Mechanistic Models: Compartment Models in Individual and Population Analysis
 01:24
One-Compartment Open Model: Wagner-Nelson and Loo Riegelman Method for ka Estimation
On...
 01:18
Steps in Outbreak Investigation