Related Experiment Video
Updated: Sep 25, 2025


An R-Based Landscape Validation of a Competing Risk Model
Published on: September 16, 2022
The upper bound of cumulative return of a trading series
Can Yang1, Junjie Zhai1, Helong Li2
1School of Computer Science and Engineering, South China University of Technology, Guangzhou, Guangdong, China.

Abstract:
We present an upper bound of cumulative return in financial trading time series to formulate the most possible profit of many trades. The bound can be used to formally analyze the cumulative return varied by the number of trades, the mean return, and transaction cost rate. We also prove and show the validation of the upper bound, and verify the trend of cumulative return is consistent with that of the proposed bound via simulation experiments. Introducing a set of stochastic assessment methodology based on bootstrap into the organization of experimental data, we illustrate the influence on cumulative return from the relationship between the mean of return and transaction cost rate, technical trading rules, and stock indexes. To the best of our knowledge, this is the first to present and prove a bound of cumulative return of a stock trading series in theory. Both theoretical analyses and simulation experiments show the presented bound is a good mathematical tool to evaluate the trading risks and chances using given trading rules in stock trading markets.

Related Concept Videos
 01:04
Cumulative Frequency Distribution
 01:21
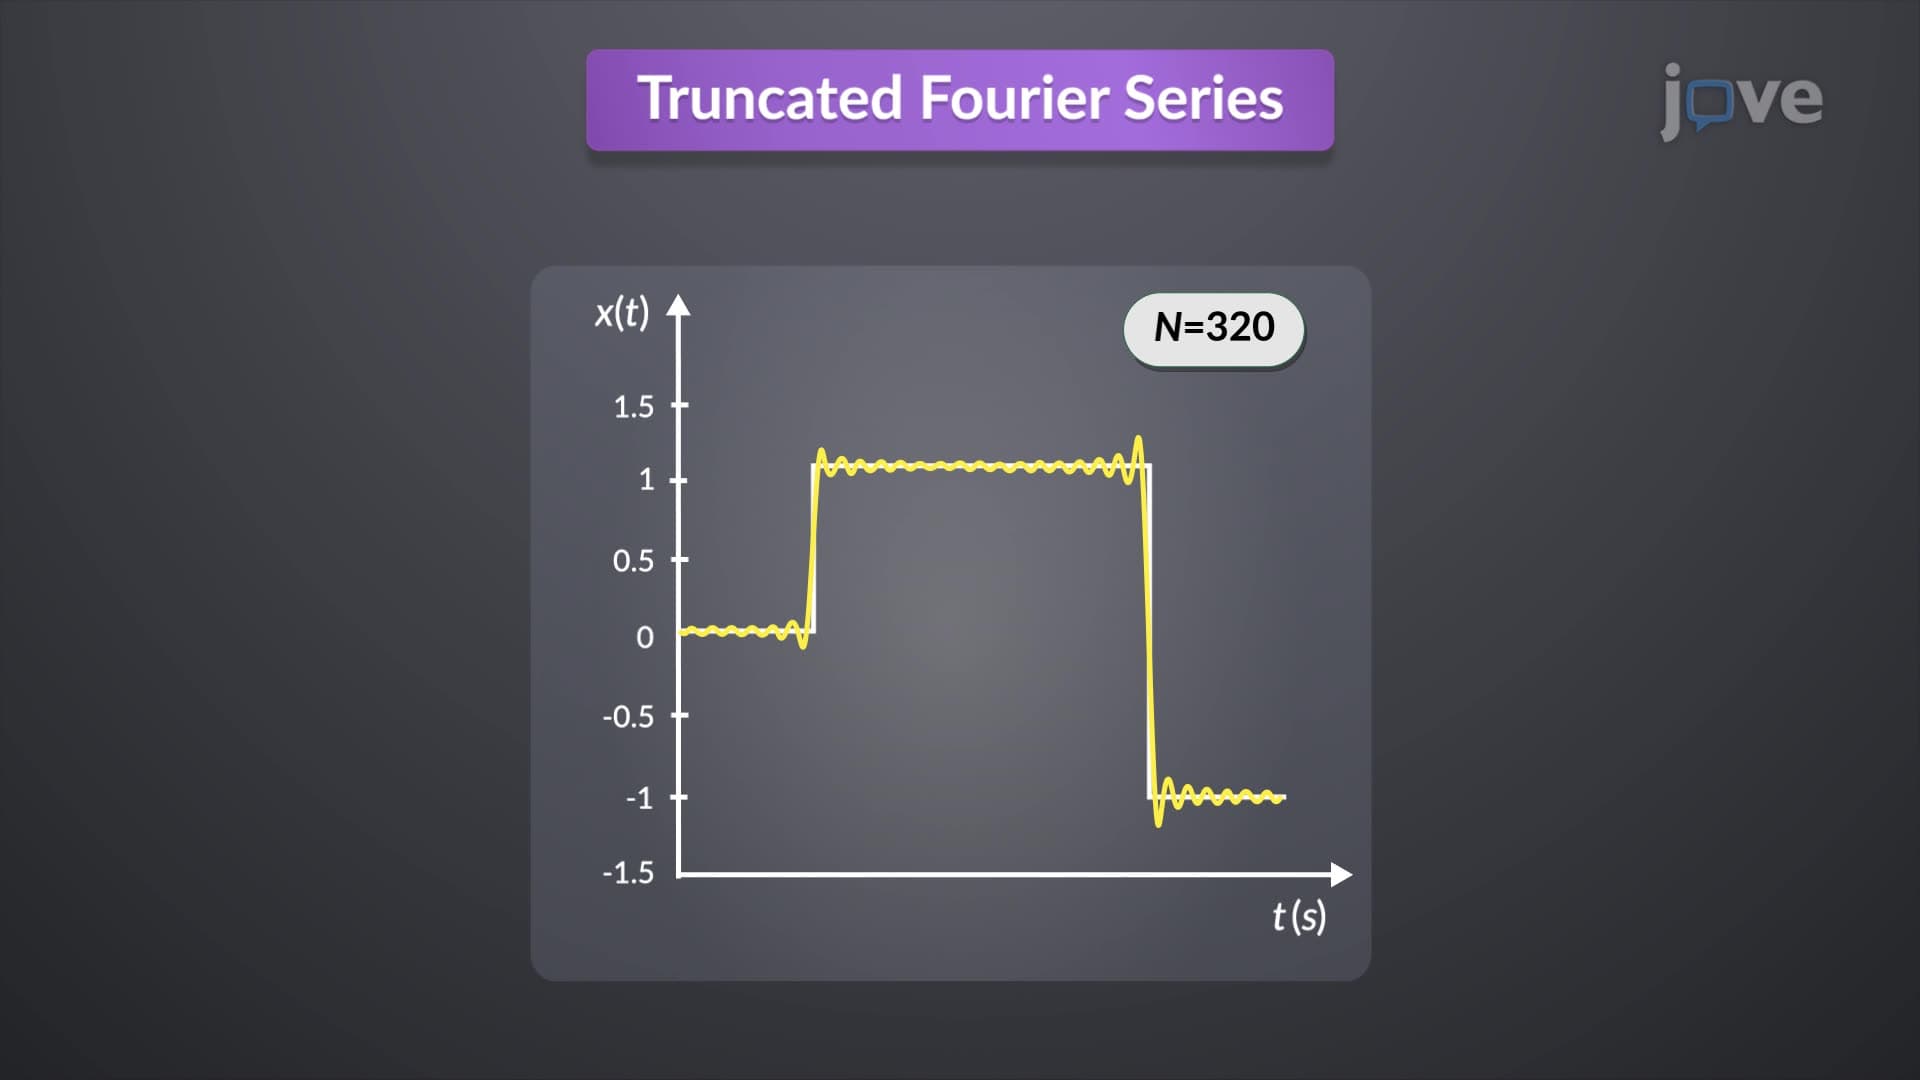
Convergence of Fourier Series
The Gibbs phenomenon refers to the persistent oscillations and overshoots that occur near discontinuities...
 01:07
Ogive Graph
 01:17
Trigonometric Fourier series
The trigonometric Fourier series specifically expresses a periodic function with a defined period T using sine...
 01:16
Unusual Results
According to the range rule of thumb, any value above or below two standard deviations, 2σ from the mean, μ is considered unusual.
Maximum unusual value =...
 01:10
Trimmed Mean
Although certain measures of central tendency are not sensitive to outliers, there are alternative versions of the mean that get around the...