Related Experiment Video
Updated: Sep 8, 2025
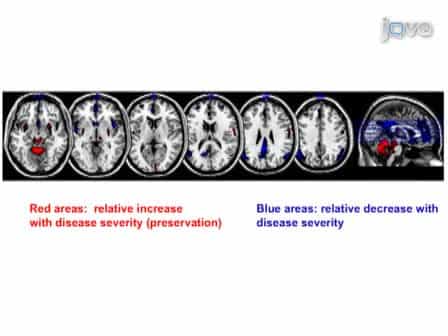

Basics of Multivariate Analysis in Neuroimaging Data
Published on: July 24, 2010
An automatic robust Bayesian approach to principal component regression
Philippe Gagnon1, Mylène Bédard2, Alain Desgagné3
1Department of Statistics, University of Oxford, Oxford, UK.

Abstract:
Principal component regression uses principal components (PCs) as regressors. It is particularly useful in prediction settings with high-dimensional covariates. The existing literature treating of Bayesian approaches is relatively sparse. We introduce a Bayesian approach that is robust to outliers in both the dependent variable and the covariates. Outliers can be thought of as observations that are not in line with the general trend. The proposed approach automatically penalises these observations so that their impact on the posterior gradually vanishes as they move further and further away from the general trend, corresponding to a concept in Bayesian statistics called whole robustness. The predictions produced are thus consistent with the bulk of the data. The approach also exploits the geometry of PCs to efficiently identify those that are significant. Individual predictions obtained from the resulting models are consolidated according to model-averaging mechanisms to account for model uncertainty. The approach is evaluated on real data and compared to its nonrobust Bayesian counterpart, the traditional frequentist approach and a commonly employed robust frequentist method. Detailed guidelines to automate the entire statistical procedure are provided. All required code is made available, see ArXiv:1711.06341.
Related Concept Videos
 01:25
Multiple Regression
Farmers can use multiple regression to determine the crop yield based on more than one factor, such as water availability, fertilizer, soil properties, etc. Here, the crop yield is the response or dependent variable as it depends on the other independent variables. The analysis requires the construction of a scatter plot...
 01:14
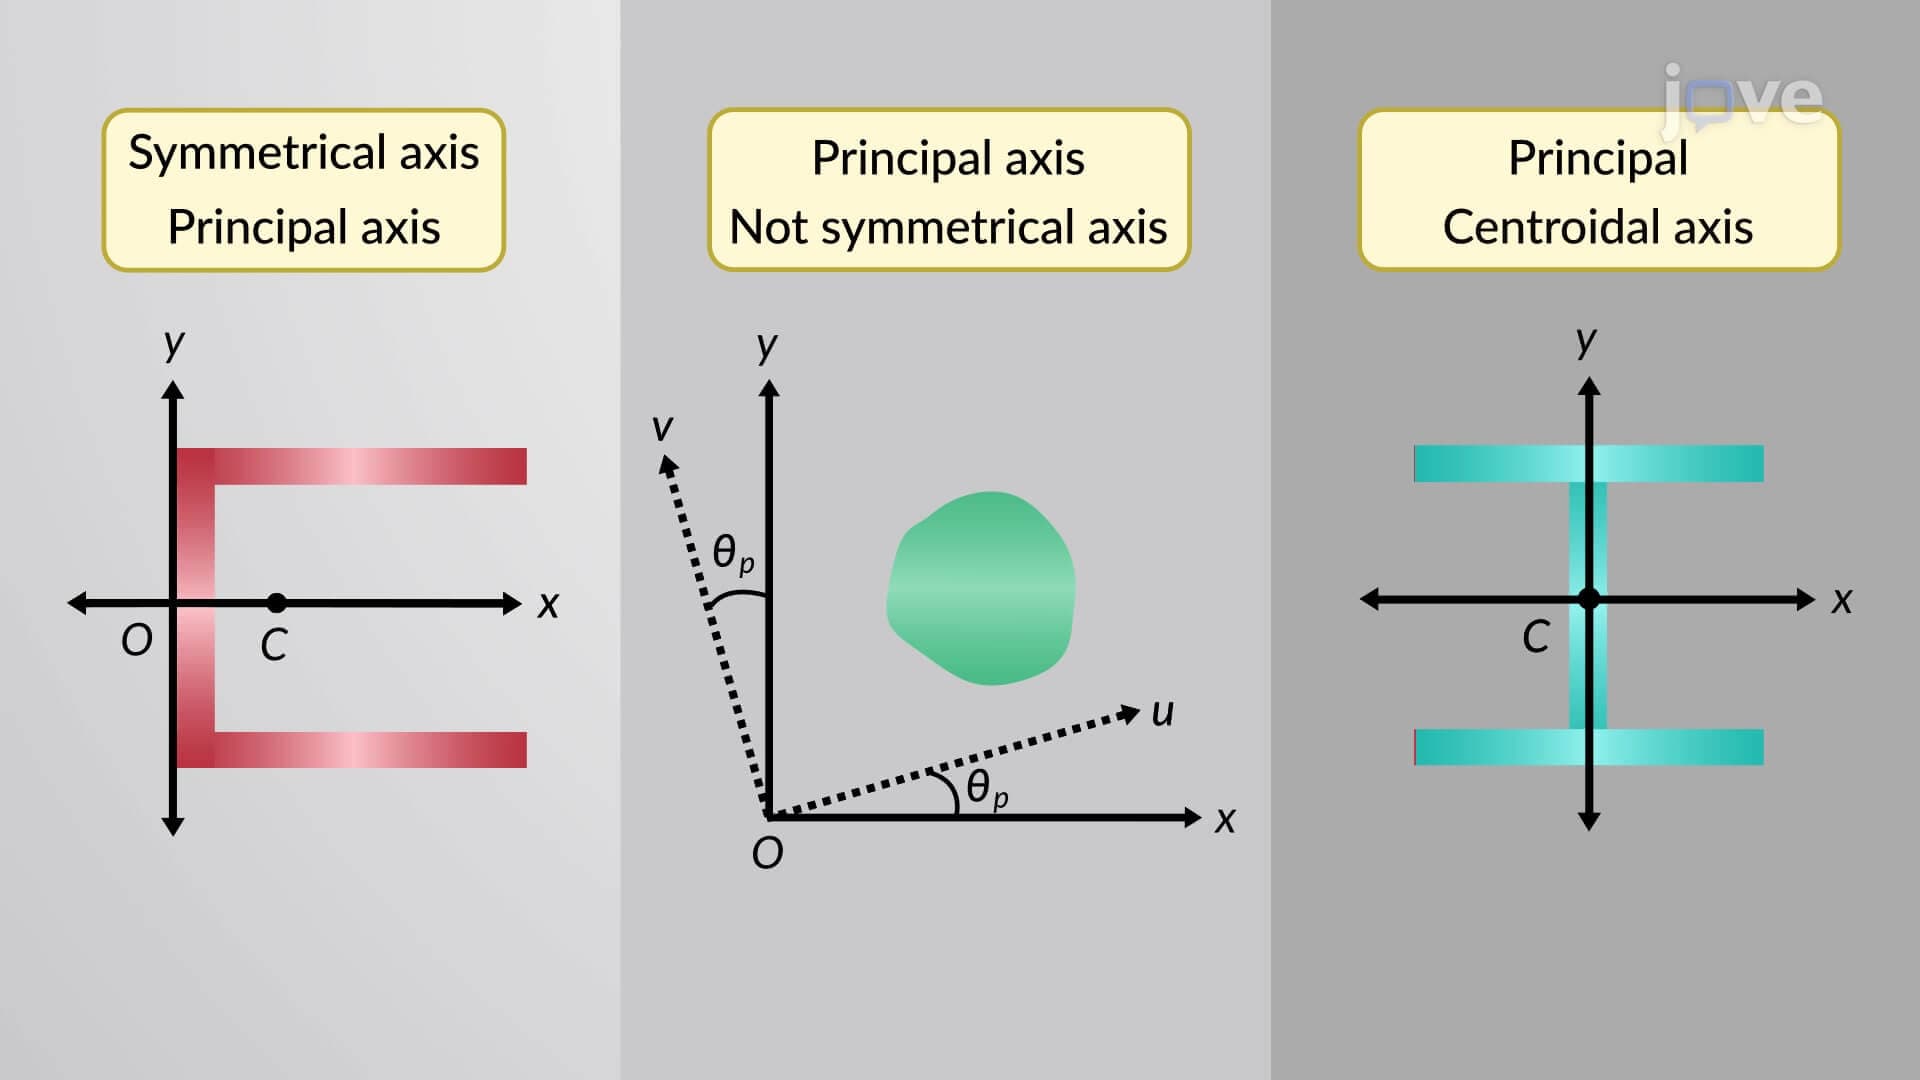
Principal Moments of Area
The principal moment of inertia axes are the...
 01:11
Regression Analysis
In regression analysis, a regression equation is determined based on the line of best fit– a line that best fits the data points plotted in a graph. This line is also called the regression line. The algebraic equation for the regression line is called the regression equation. It is represented as:
 01:24
One-Compartment Open Model: Wagner-Nelson and Loo Riegelman Method for ka Estimation
On...
 01:06
Model Approaches for Pharmacokinetic Data: Distributed Parameter Models
The distributed parameter models are specifically designed to account for variations and differences in some drug classes. This model is particularly useful for assessing regional concentrations of anticancer or...
 01:11
Residuals and Least-Squares Property
If the observed data point lies above the line, the residual is positive, and the line underestimates the actual data value for y. If the observed data point lies below the line, the residual is negative, and the line overestimates the actual data value for y.
The process of fitting the best-fit...