Related Experiment Video
Updated: Sep 3, 2025

Applications of EEG Neuroimaging Data: Event-related Potentials, Spectral Power, and Multiscale Entropy
Published on: June 27, 2013
Regularity in Stock Market Indices within Turbulence Periods: The Sample Entropy Approach
Joanna Olbryś1, Elżbieta Majewska2
1Faculty of Computer Science, Bialystok University of Technology, Wiejska 45a, 15-351 Białystok, Poland.

Abstract:
The aim of this study is to assess and compare changes in regularity in the 36 European and the U.S. stock market indices within major turbulence periods. Two periods are investigated: the Global Financial Crisis in 2007-2009 and the COVID-19 pandemic outbreak in 2020-2021. The proposed research hypothesis states that entropy of an equity market index decreases during turbulence periods, which implies that regularity and predictability of a stock market index returns increase in such cases. To capture sequential regularity in daily time series of stock market indices, the Sample Entropy algorithm (SampEn) is used. Changes in the SampEn values before and during the particular turbulence period are estimated. The empirical findings are unambiguous and confirm no reason to reject the research hypothesis. Moreover, additional formal statistical analyses indicate that the SampEn results are similar both for developed and emerging European economies. Furthermore, the rolling-window procedure is utilized to assess the evolution of SampEn over time.
Related Concept Videos
 01:04
Random Error
 01:09
Empirical Method to Interpret Standard Deviation
This rule is used widely in statistics to calculate the proportion of data values...
 01:12
Sampling Distribution
 01:20
Entropy and the Second Law of Thermodynamics
The relation between entropy and disorder can be illustrated with the example of the phase change of ice to water. In ice, the molecules are located at specific sites giving a solid state, whereas, in a liquid form, these molecules are much freer to move. The molecular arrangement has therefore become more randomized. Although the change in average...
 01:16
Unusual Results
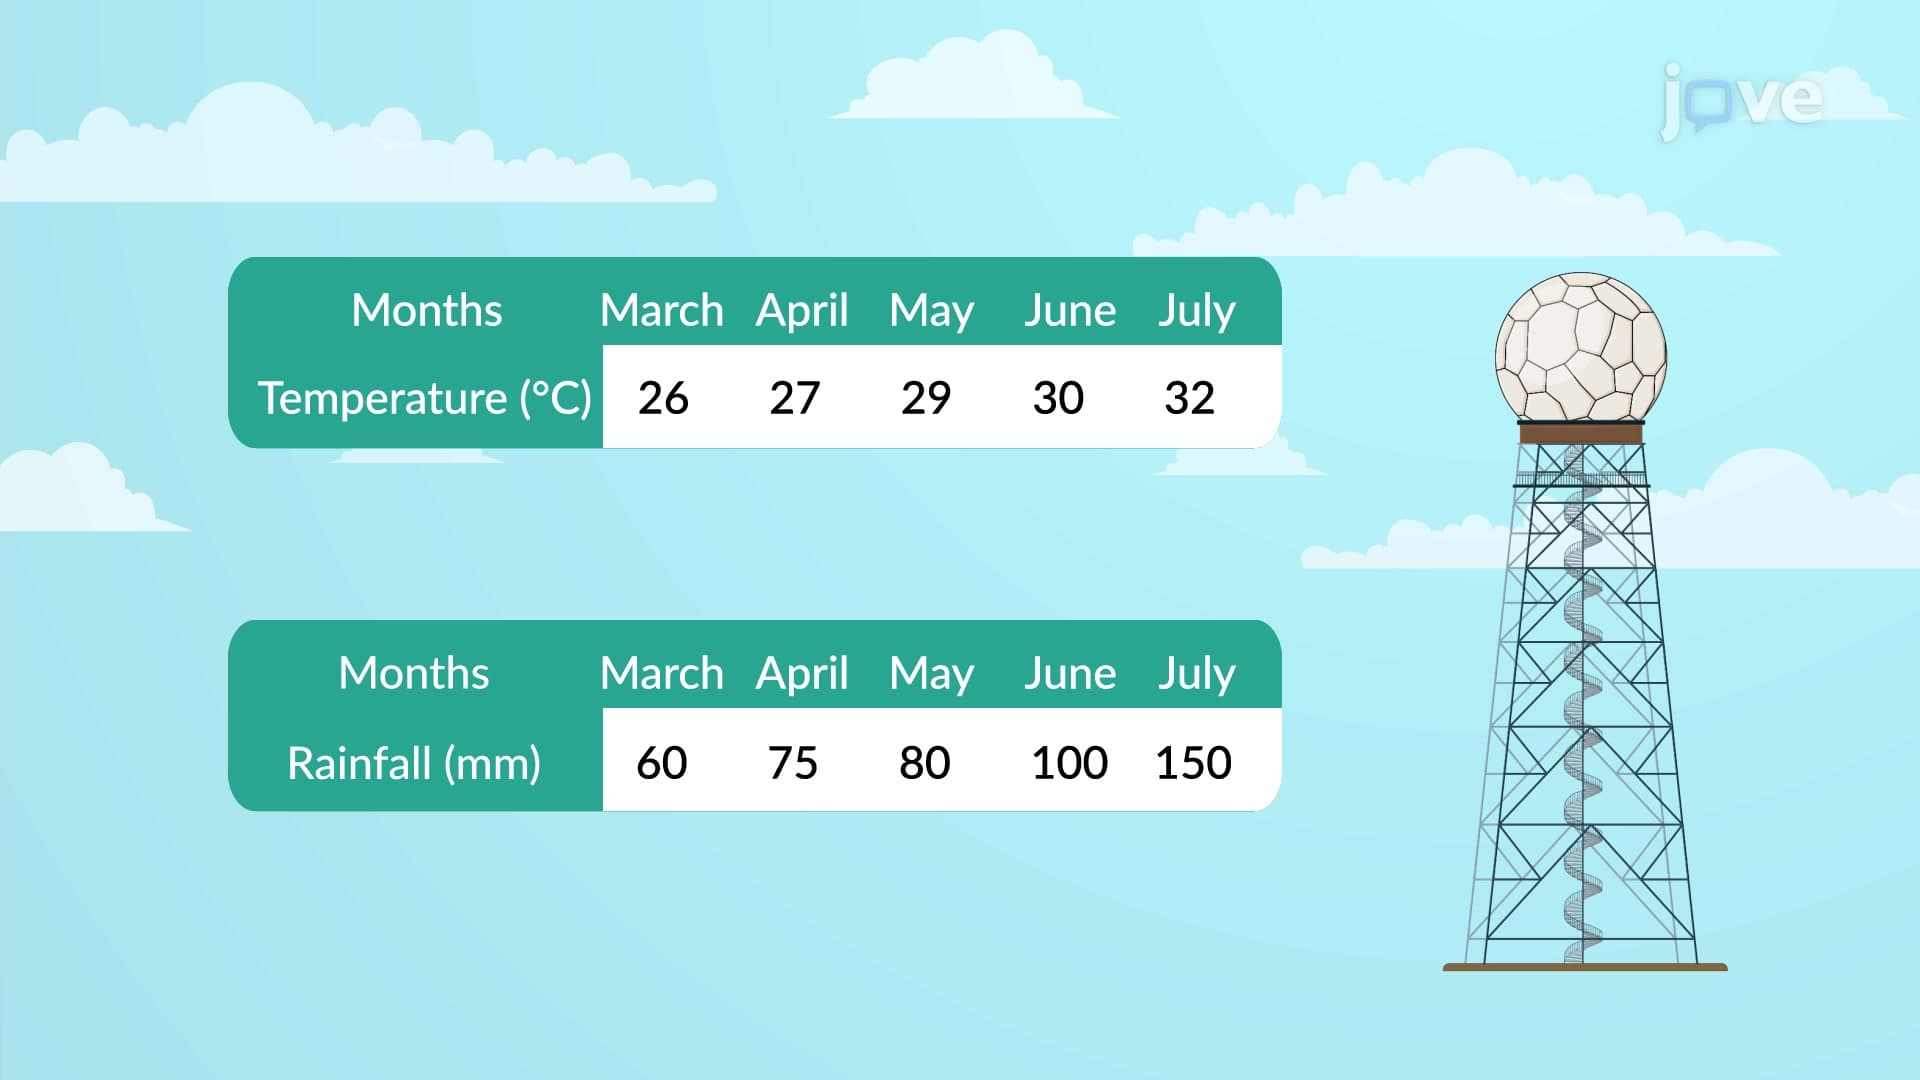
According to the range rule of thumb, any value above or below two standard deviations, 2σ from the mean, μ is considered unusual.
Maximum unusual value =...
 01:10
Coefficient of Variation
The coefficient of variation is a practical statistical tool in finance. It allows investors to assess the volatility or...