Related Experiment Video
Updated: Sep 2, 2025


Development of an Individual-Tree Basal Area Increment Model using a Linear Mixed-Effects Approach
Published on: July 3, 2020
Collinearity Issues in Autoregressive Models with Time-Varying Serially Dependent Covariates
Sigert Ariens1, Janne K Adolf1, Eva Ceulemans1
1Quantitative Psychology and Individual Differences, Faculty of Psychology and Educational Sciences, KU Leuven.

Abstract:
First-order autoregressive models are popular to assess the temporal dynamics of a univariate process. Researchers often extend these models to include time-varying covariates, such as contextual factors, to investigate how they moderate processes' dynamics. We demonstrate that doing so has implications for how well one can estimate the autoregressive and covariate effects, as serial dependence in the variables can imply predictor collinearity. This is a noteworthy contribution, since in current practice serial dependence in a time-varying covariate is rarely considered important. We first recapitulate the role of predictor collinearity for estimation precision in an ordinary least squares context, by discussing how it affects estimator variances, covariances and correlations. We then derive a general formula detailing how predictor collinearity in first-order autoregressive models is impacted by serial dependence in the covariate. We provide a simulation study to illustrate the implications of the formula for different types of covariates. The simulation results highlight when the collinearity issue becomes severe enough to hamper interpretation of the effects. We also show that the effect estimates can be biased in small samples (i.e., 50 time points). Implications for study design, the use of time as a predictor, and related model variants are discussed.
More Related Videos
Related Concept Videos
 01:25
Multiple Regression
Farmers can use multiple regression to determine the crop yield based on more than one factor, such as water availability, fertilizer, soil properties, etc. Here, the crop yield is the response or dependent variable as it depends on the other independent variables. The analysis requires the construction of a scatter plot...
 01:23
Linear time-invariant Systems
The input-output behavior of an LTI system can be fully defined by its response to an impulsive excitation at its input. Once this impulse response is known, the system's reaction to any other input can be...
 01:21
Friedman Two-way Analysis of Variance by Ranks
 01:09
Correlation
Two variables, for example, a and b, are said to be positively correlated if both variables move in the same direction. In other words, a positive correlation exists between two variables, a and b, if:
 00:53
Correlation and Regression
 01:12
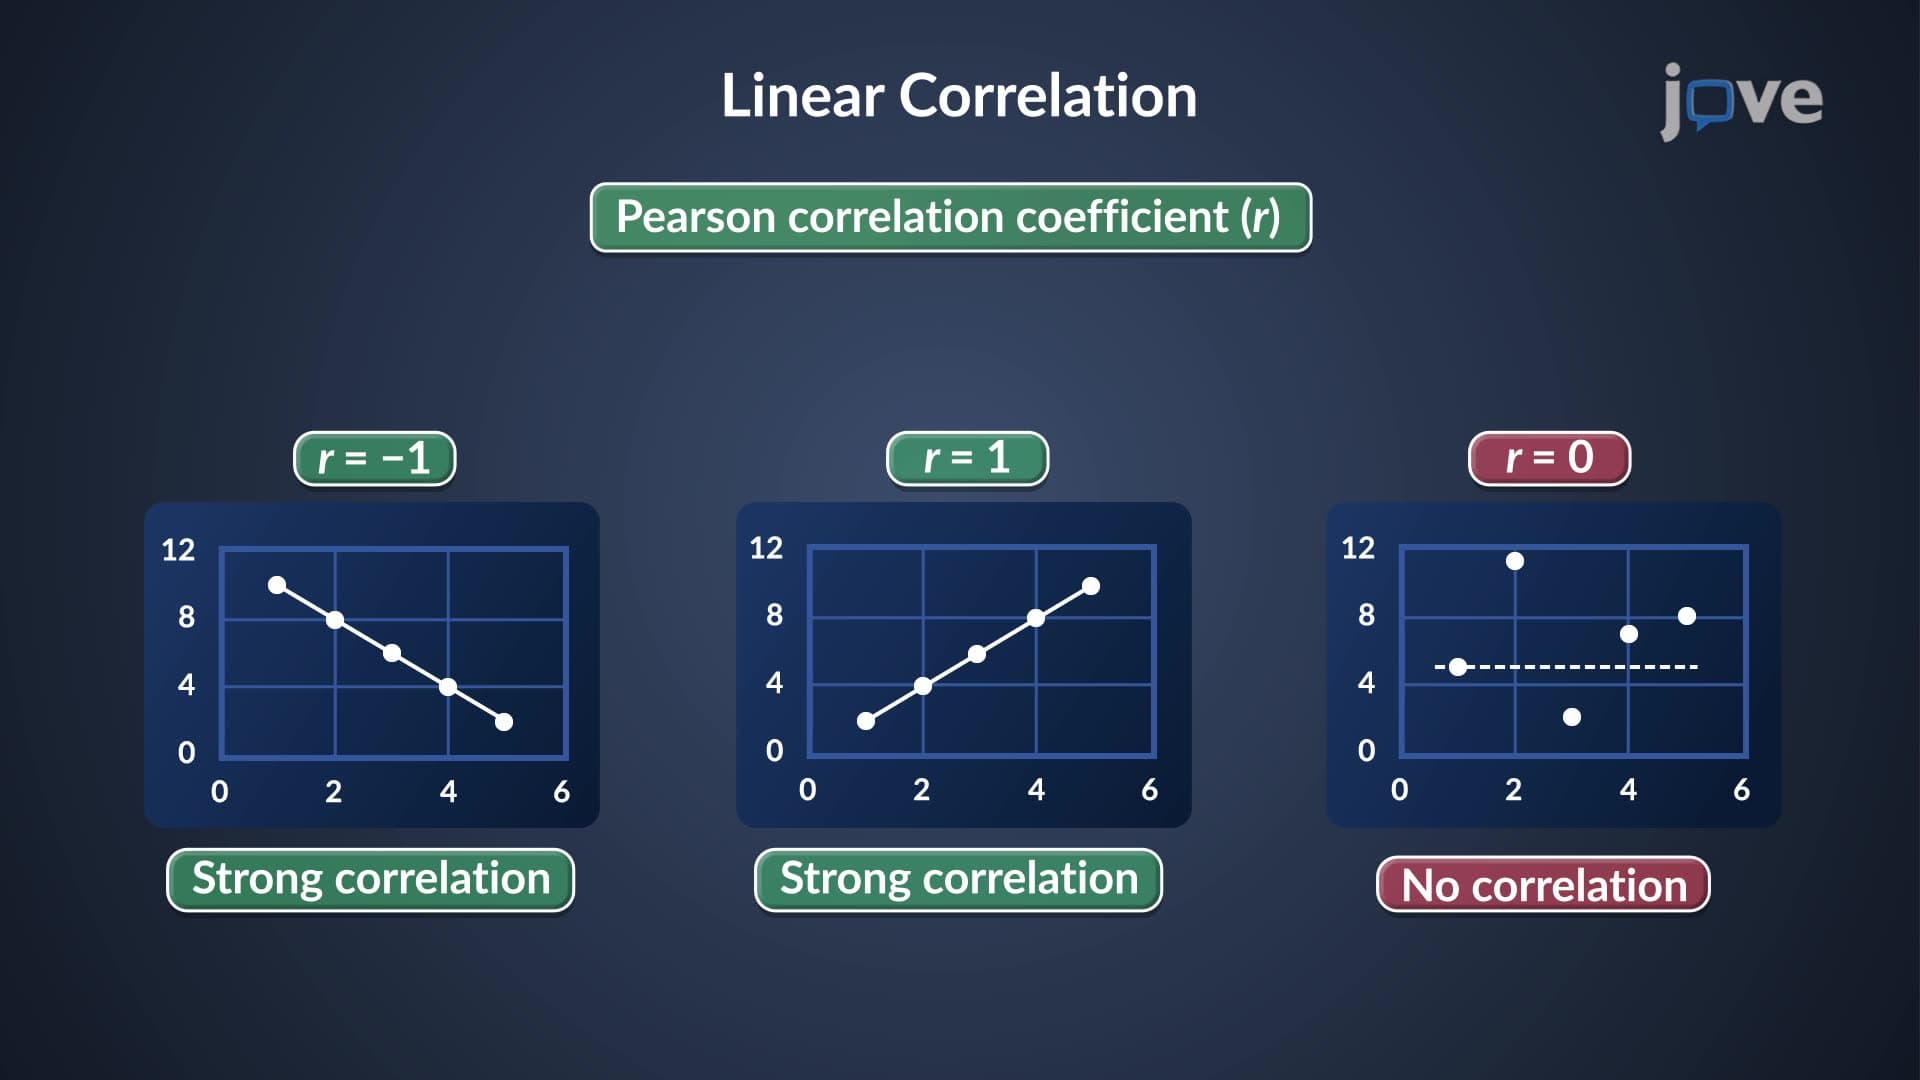
Coefficient of Correlation
If you suspect a linear relationship between x and y, then r can measure how strong the linear relationship is.
What the VALUE of r tells us:
The value of r is always between –1 and +1: –1 ≤ r ≤ 1.
The size of the correlation r indicates the...