Related Experiment Video
Updated: Sep 2, 2025

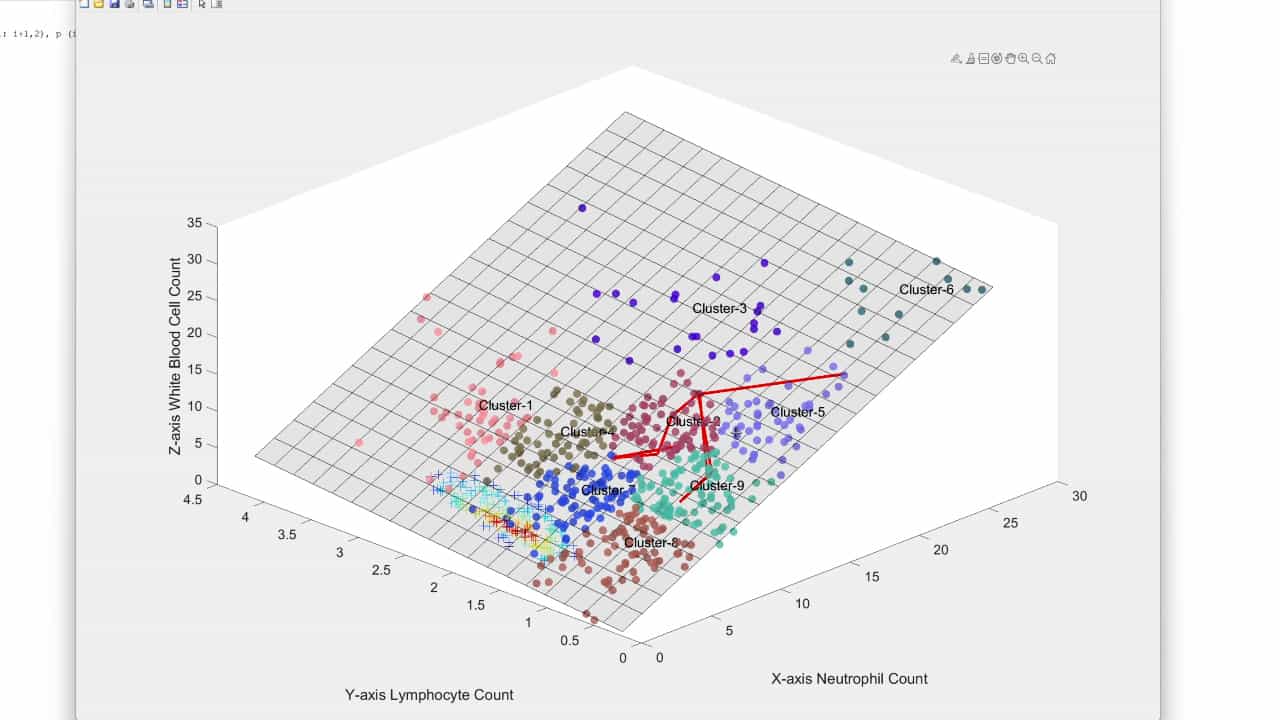
A Method of Trigonometric Modelling of Seasonal Variation Demonstrated with Multiple Sclerosis Relapse Data
Published on: December 9, 2015
Quantifying chaos in stock markets before and during COVID-19 pandemic from the phase space reconstruction
1Fundação de Apoio à Escola Técnica, Escola Técnica Estadual Visconde de Mauá, 21610-210 Rio de Janeiro - RJ, Brazil.

Abstract:
From a methodology in the reconstruction scheme, applicable to chaotic time series of economic indices, this paper presents an analysis of the underlying dynamics of stock markets of North America, Europe and Asia. The same global fit model and reconstruction parameters-employed to study the time evolution of S&P 500, NASDAQ Composite, IBEX 35, EURONEXT 100, Nikkei 225 and SSE Composite Index-led a convenient simplification in the analysis. The tools chosen to analyse the time dependence of the level of chaos concerning weeks of economic activity were scatter plots, histograms and sample Spearman correlation coefficients. The results permit to evaluate the impact of the pandemic in the underlying dynamics of different stock markets and to compare them to one another.

Related Concept Videos
 00:54
Uncertainty: Confidence Intervals
 01:13
Interpreting X̄ Charts
An x̄ chart plots the values of individual measurements over time against control limits calculated from historical data. The central line...
 01:12
Quantitative Analysis
In quantitative analysis, two key measurements are made: the sample quantity and a property proportional to the amount of the analyte (the substance being analyzed). This forms the basis of the...
 00:59
Uncertainty: Overview
 00:54
Time-Series Graph
 01:17
Probability Histograms