Related Experiment Video
Updated: Sep 1, 2025

The Collective Trust Game: An Online Group Adaptation of the Trust Game Based on the HoneyComb Paradigm
Published on: October 20, 2022
Illiquidity Comovement and Market Crisis
Qingduo Zeng1, Qiang Zhang2, Shancun Liu3
1School of Economics and Commerce, Guangdong University of Technology, Guangzhou, 510520 China.

Abstract:
This paper presents a rational expectation equilibrium model to explore how the financial contagion occurs between the unlinked markets that do not share common fundamentals. In the proposed model, the authors assume two of the three risky assets share no common fundamental factors, but are connected by one intermediate asset via cross fundamentals. Through this channel, investors transmit fundamental risk from one asset to another by dint of the cross fundamentals. This mechanism causes liquidity comovement and subsequently becomes a source of market crisis: Through the contagion mechanism, an initial liquidity shock in one asset can result in a drop tendency in liquidity and price informativeness for another asset. Such comovement in liquidity offers a new explanation for idiosyncratic assets in financial contagion.
Related Concept Videos
 02:20
Dynamic Equilibrium
 01:15
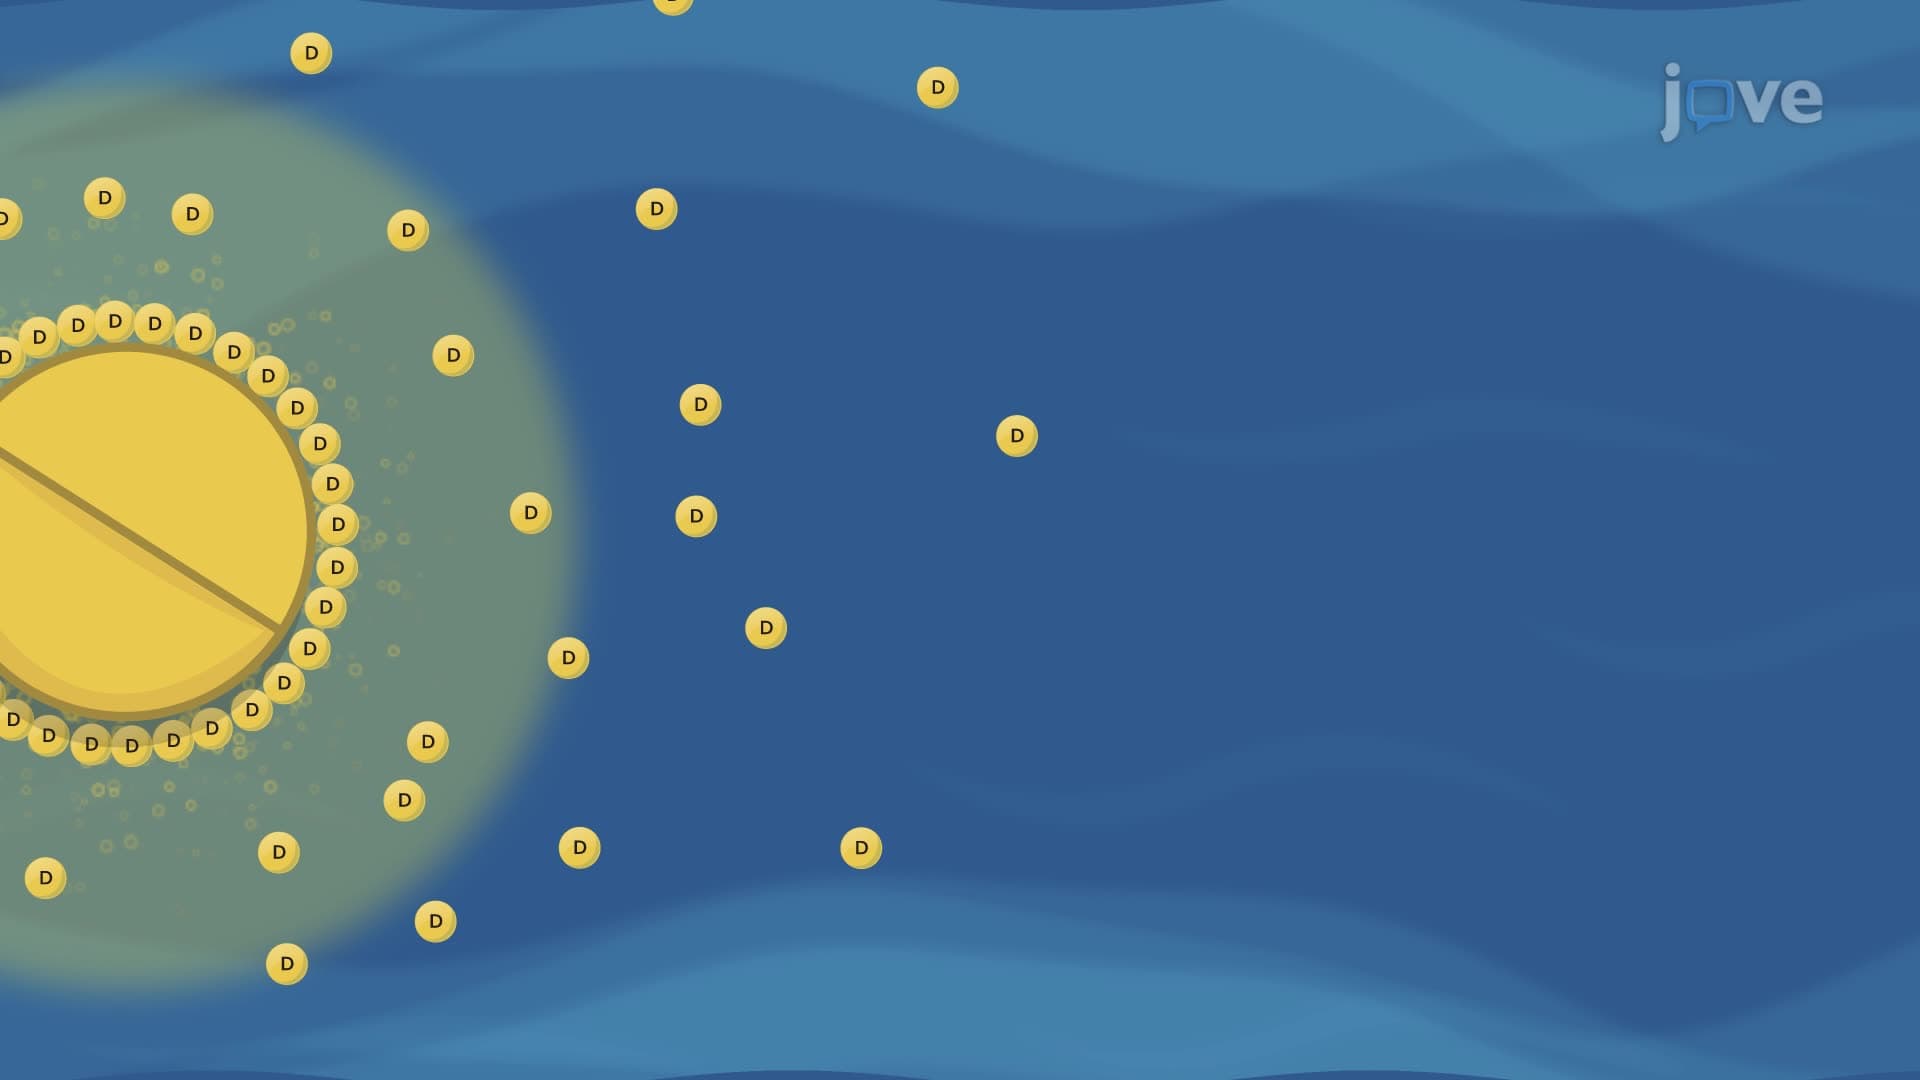
Theories of Dissolution: Diffusion Layer Model
This process starts with a thin layer, saturated with the drug, forming at the interface between the solid and liquid. The solute then diffuses from this layer into the main solution. The Noyes-Whitney equation suggests that the rate of dissolution relies on the diffusion...
 01:28
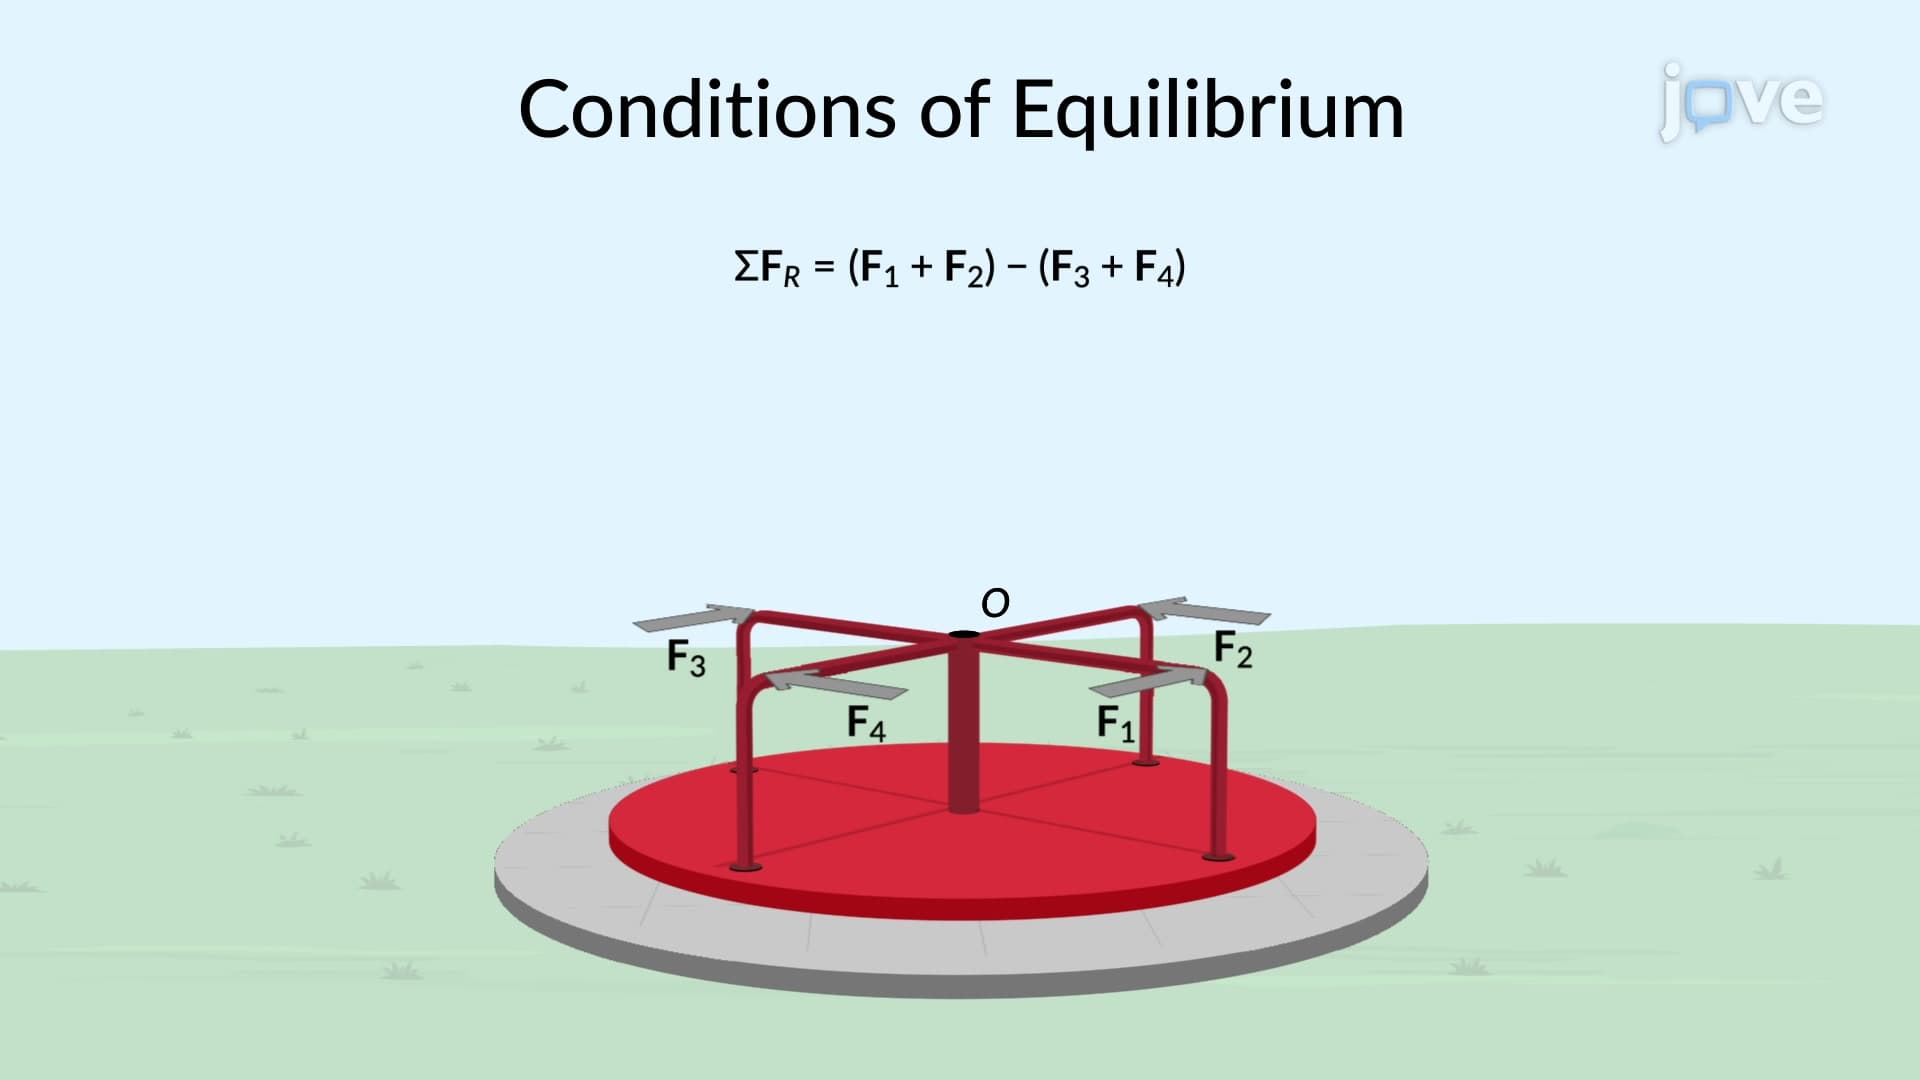
Conditions of Equilibrium
Internal forces are not considered for conditions of equilibrium because they occur in equal and opposite pairs within the body, effectively canceling each other. As a result,...
 02:17
Microtubule Instability
 01:26
Unsoundness of Aggregate due to Volume Change
 01:58
Cooperative Allosteric Transitions