Related Experiment Video
Updated: Aug 31, 2025
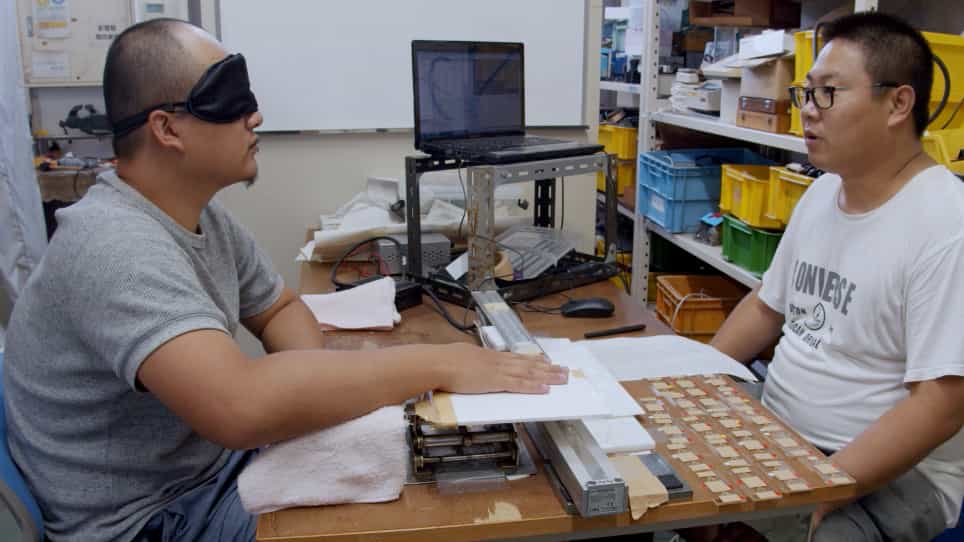
Tactile Semiautomatic Passive-Finger Angle Stimulator TSPAS
Published on: July 30, 2020
Penalized logistic regressions with technical indicators predict up and down trends
Huifeng Jiang1, Xuemei Hu2, Hong Jia1
1Research Center for Economy of Upper Reaches of the Yangtse River, Chongqing Technology and Business University, 19 Xuefu Avenue, Chongqing, 400067 China.

Abstract:
Correctly predicting up and down trends for stock prices is of immense important in the financial market. To further improve the prediction performance, in this paper we introduce five penalties: ridge, least absolute shrinkage and selection operator, elastic net, smoothly clipped absolute deviation and minimax concave penalty to logistic regressions with 19 technical indicators, and propose the five penalized logistic regressions to predict up and down trends for stock prices. Firstly, we translate the five penalized logistic log-likelihood functions into the five penalized weighted least squares functions and combine them with the tenfold cross-validation method to calculate the solution path to parameter estimators. Secondly, we combine the binomial deviation with cross-validation error as a risk measure to choose an appropriate tuning parameter for the penalty functions and apply the training set and the coordinate descent algorithm to obtain parameter estimators and probability estimators. Thirdly, we employ the testing set and the chosen optimal thresholds to construct two-class confusion matrices and receiver operating characteristic curves to assess the prediction performances to the five regressions. Finally, we compare the proposed five penalized logistic regressions with logistic regression, support vector machine and artificial neural network and found that the minimax concave penalty logistic regression performs the best in terms of the prediction performance to up and down trends for Google's stock prices. Therefore, in this paper we propose the five new prediction methods to improve the prediction accuracy of stock returns and bring economic benefits for investors.
Related Concept Videos
 01:11
Residuals and Least-Squares Property
If the observed data point lies above the line, the residual is positive, and the line underestimates the actual data value for y. If the observed data point lies below the line, the residual is negative, and the line overestimates the actual data value for y.
The process of fitting the best-fit...
 01:11
Regression Analysis
In regression analysis, a regression equation is determined based on the line of best fit– a line that best fits the data points plotted in a graph. This line is also called the regression line. The algebraic equation for the regression line is called the regression equation. It is represented as:
 01:52
Regression Toward the Mean
 01:18
Microsoft Excel: Regression Analysis
To perform regression...
 01:08
Outliers and Influential Points
 01:07
Residual Plots
When the residual values are plotted against the variable x, it is called a residual...