Related Experiment Video
Updated: Aug 29, 2025

Measuring the Subjective Value of Risky and Ambiguous Options using Experimental Economics and Functional MRI Methods
Published on: September 19, 2012
The effect of COVID-19 pandemic on return-volume and return-volatility relationships in cryptocurrency markets
Parisa Foroutan1, Salim Lahmiri1
1Department of Supply Chain and Business Technology Management, Concordia University, Montreal, Canada.

Abstract:
Understanding the dynamics of cryptocurrency markets during financial crises such as the recent one caused by the COVID-19 pandemic is crucial for policy makers and investors. In this study, the effect of COVID-19 pandemic on the return-volatility and return-volume relationships for the ten most traded cryptocurrencies, namely Tether, Bitcoin, Ethereum, Ripple, Litecoin, Bitcoin Cash, EOS, Chainlink, Cardano, and Monero is examined. Further, the behavior of cryptocurrencies during COVID-19 pandemic is compared with less volatile markets such as Gold, WTI, and BRENT crude oil markets. To study the effect of volatility on cryptocurrency return, an EGARCH-M model is employed while for the return-volume relationships the VAR model and Granger causality tests are utilized. Results show that the return-volatility relationships for Tether, Ethereum, Ripple, Bitcoin Cash, EOS, and Monero are significant during COVID-19 pandemic, while the same relationship is not significant prior to the pandemic for any of the studied cryptocurrencies. Our findings of the return-volume relationship support the availability of causal relations from return to trading volume changes for Chainlink and Monero in the pre-COVID-19 period and for Ethereum, Ripple, Litecoin, EOS, and Cardano during the COVID-19 period. However, considering the absolute values of returns, we found a significant relationship from cryptocurrencies' absolute returns to trading volume changes for both the prior and during COVID-19 periods. From a managerial perspective, gold can be considered a suitable asset for portfolio hedging during the pandemic period and trading volume can help traders and investors identify the effect of momentum and potential trend in cryptocurrencies on their investments.

Related Concept Videos
 01:26
Unsoundness of Aggregate due to Volume Change
 01:09
Correlation
Two variables, for example, a and b, are said to be positively correlated if both variables move in the same direction. In other words, a positive correlation exists between two variables, a and b, if:
 01:20
Volume of Distribution
 01:10
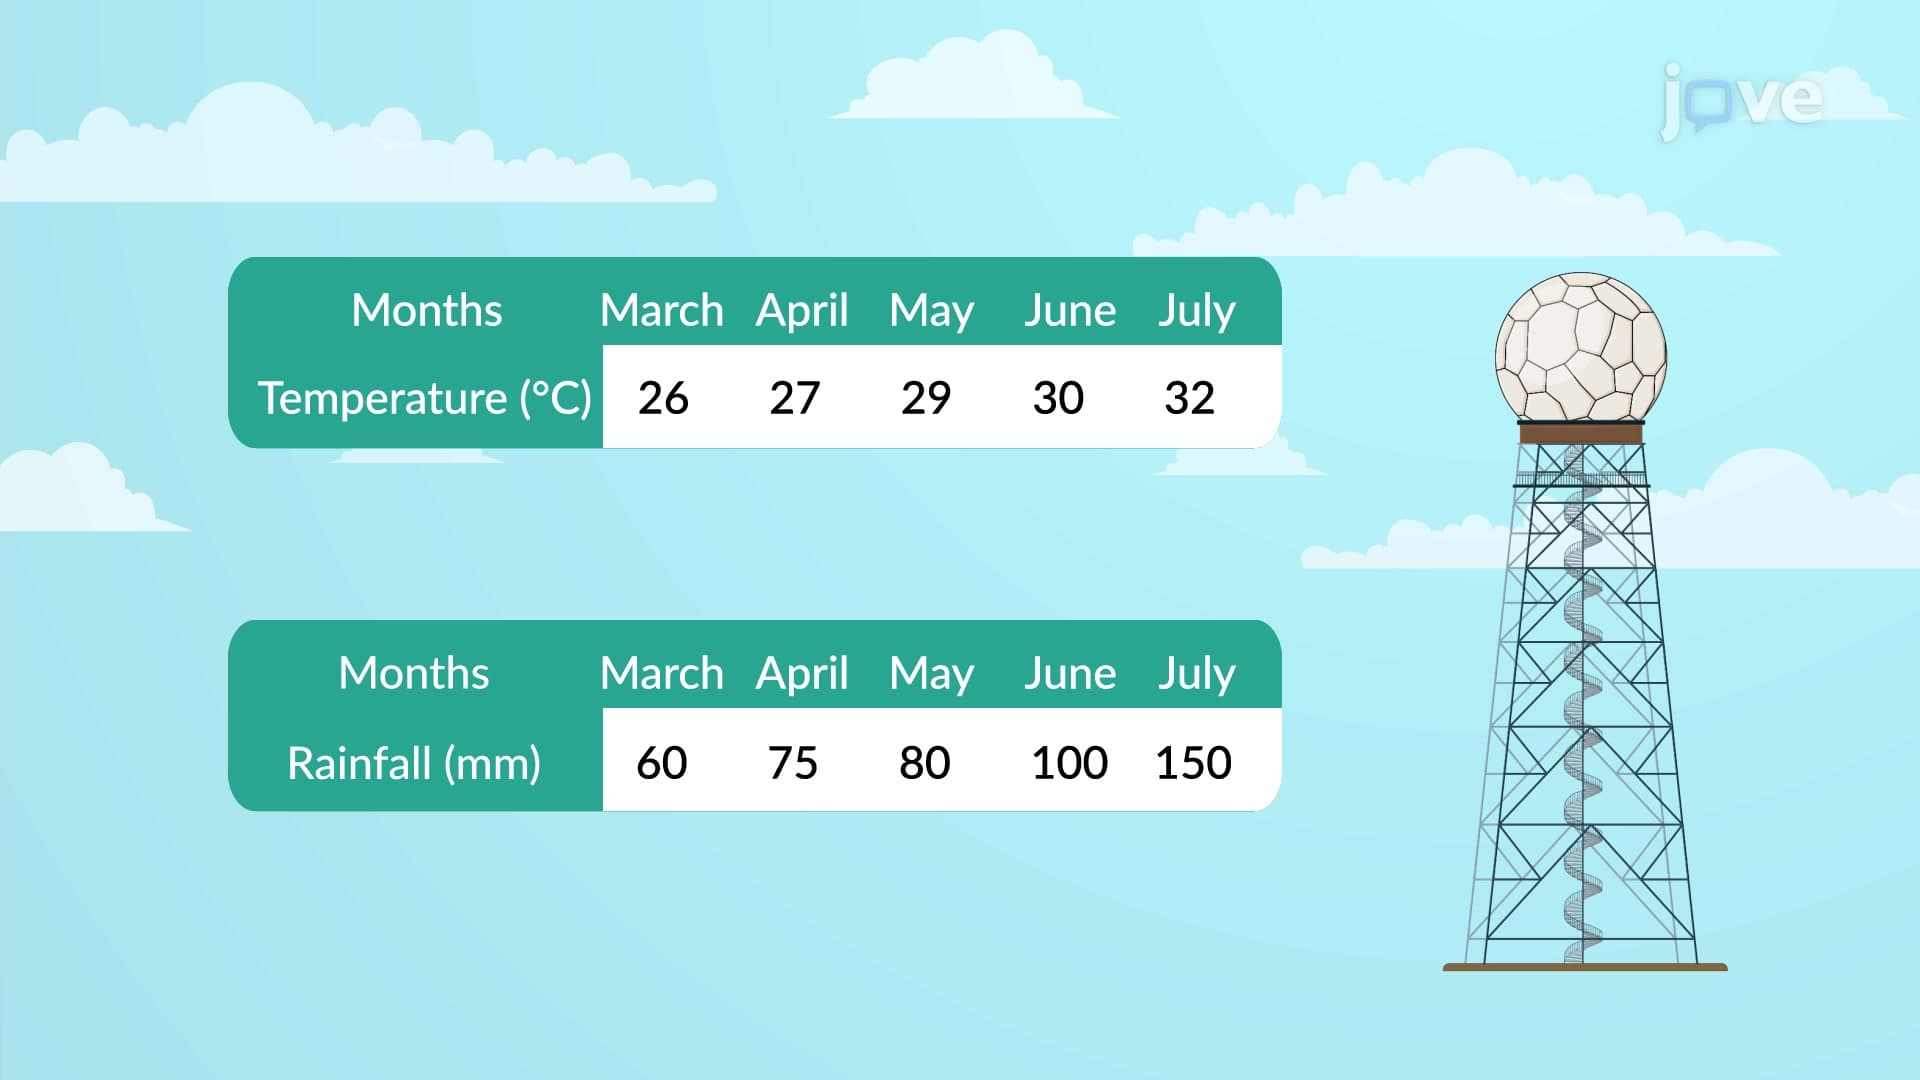
Coefficient of Variation
The coefficient of variation is a practical statistical tool in finance. It allows investors to assess the volatility or...
 01:11
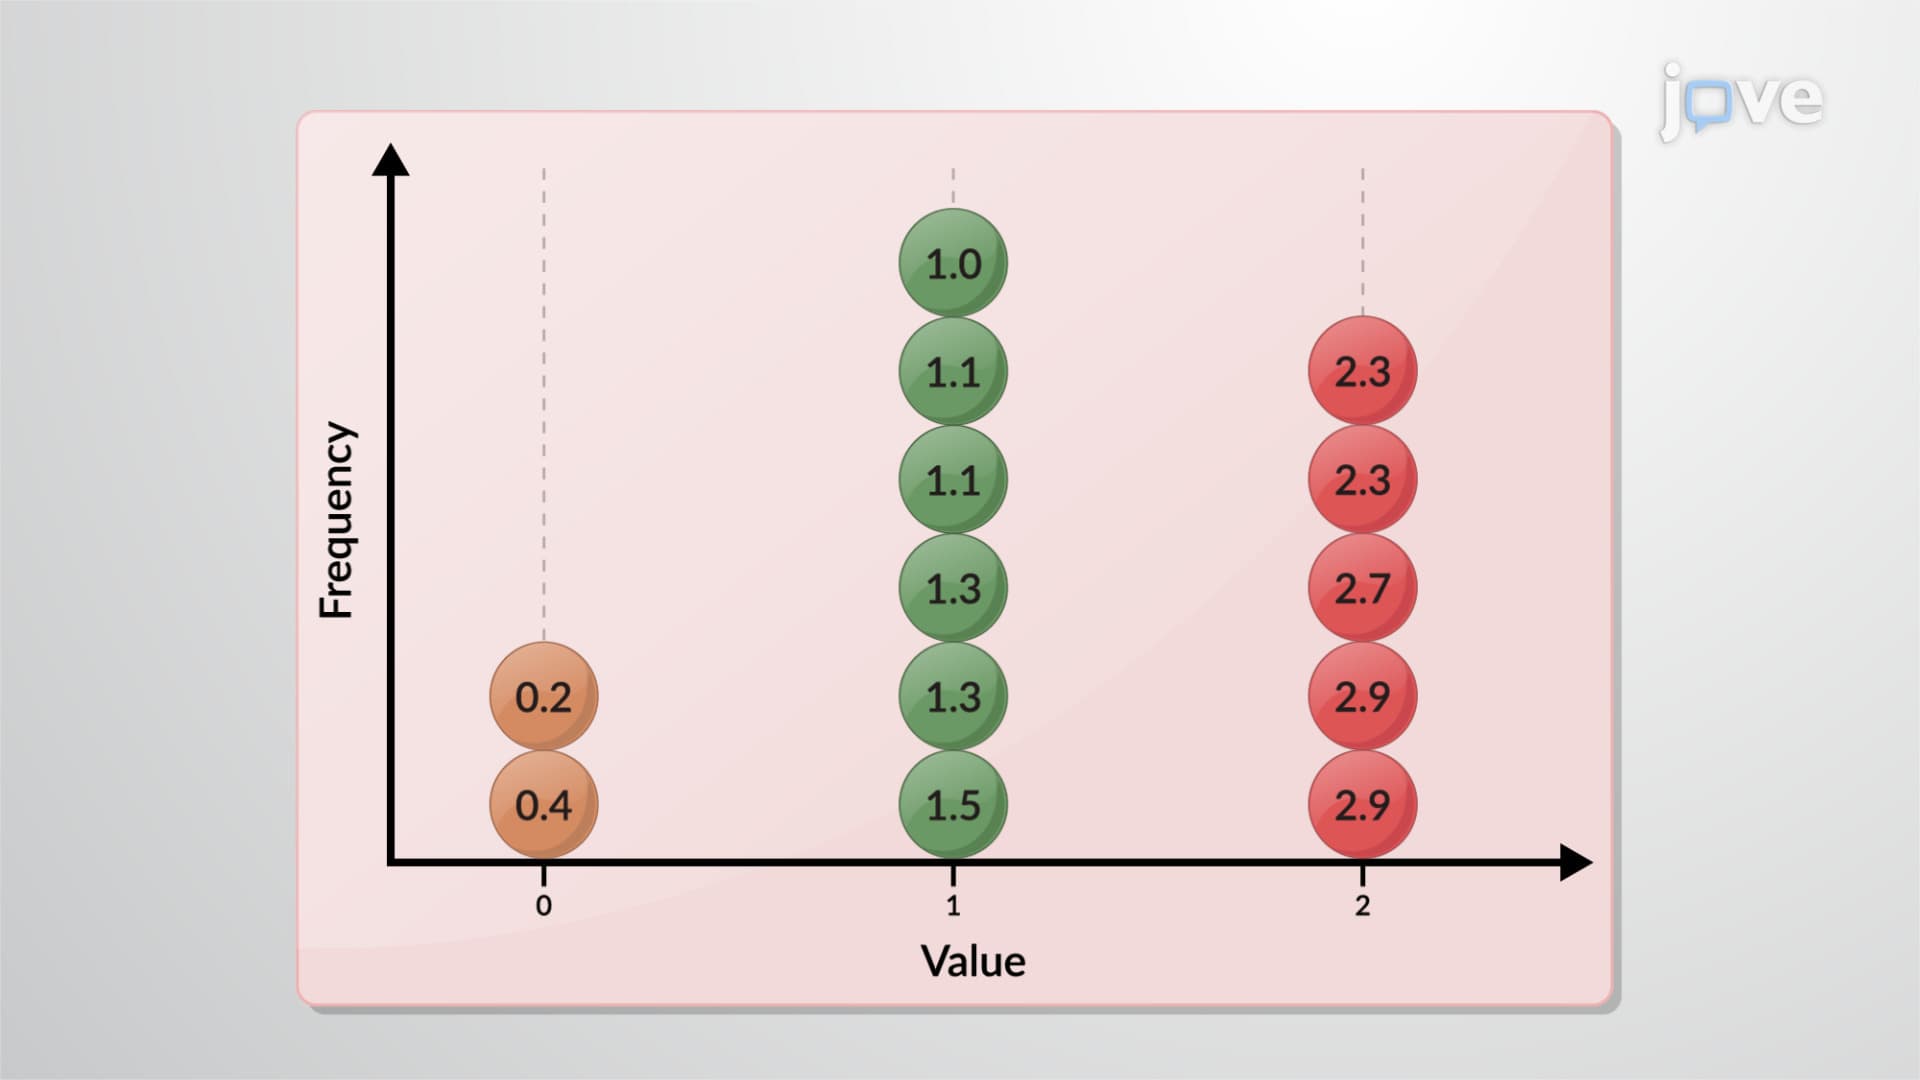
Variability: Analysis
The range is a simple measure of variability, indicating the difference between the highest and...
 01:04
Venous Return
What is Venous Return?
Venous return refers to the rate at which blood flows back to the heart from the body's peripheral veins. It's an integral part of the circulatory system...