Related Experiment Video
Updated: Aug 26, 2025

Measuring the Subjective Value of Risky and Ambiguous Options using Experimental Economics and Functional MRI Methods
Published on: September 19, 2012
Volatility Interdependence Between Cryptocurrencies, Equity, and Bond Markets
Etienne Harb1,2, Charbel Bassil3, Talie Kassamany4
1ESSCA School of Management, Angers, France.

Abstract:
This paper investigates (i) the return-volatility spillover between Bitcoin, Ethereum, Ripple, and Litecoin, (ii) the interdependence between cryptocurrencies' volatility and the US equity and bond markets' volatility, and (iii) the impact of the Covid-19 outbreak on the cryptocurrencies' return-volatility. A two-step estimation approach is considered where Univariate General Autoregressive Conditional Heteroskedastic models are estimated to model the volatility of the four cryptocurrencies then a Simultaneous Equation Model is estimated to model the interconnection between the cryptocurrency volatilities, the US equity and bond markets' volatility, and Covid-19 outbreak. We show that return-volatility spillovers exist among Bitcoin, Ethereum, and Litecoin while Ripple is the main transmitter of shocks. We find that the cryptocurrency market is detached from the US stock market but not from the US bond market. Finally, we show that a high economic and financial uncertainty in the US stock market due to pandemic outbreaks affects the price of Litecoin, Bitcoin, and Ethereum. However, shocks are short-lived. Our findings have practical implications; as the evidence of volatility spillovers among cryptocurrencies and their relative isolation from the majority of mainstream assets should be factored into the valuation and portfolio diversification strategies of investors. In crisis times such as those induced by Covid-19, investors who seek protection from downward movements in bond markets could benefit from taking a position in Ethereum. Policymakers can also rely on our findings to time their intervention to stabilize markets and control uncertainties inherent to stressful periods.

Related Concept Videos
 01:11
Variability: Analysis
The range is a simple measure of variability, indicating the difference between the highest and...
 01:10
Coefficient of Variation
The coefficient of variation is a practical statistical tool in finance. It allows investors to assess the volatility or...
 02:45
Valence Bond Theory
 01:22
Spin–Spin Coupling: Three-Bond Coupling (Vicinal Coupling)
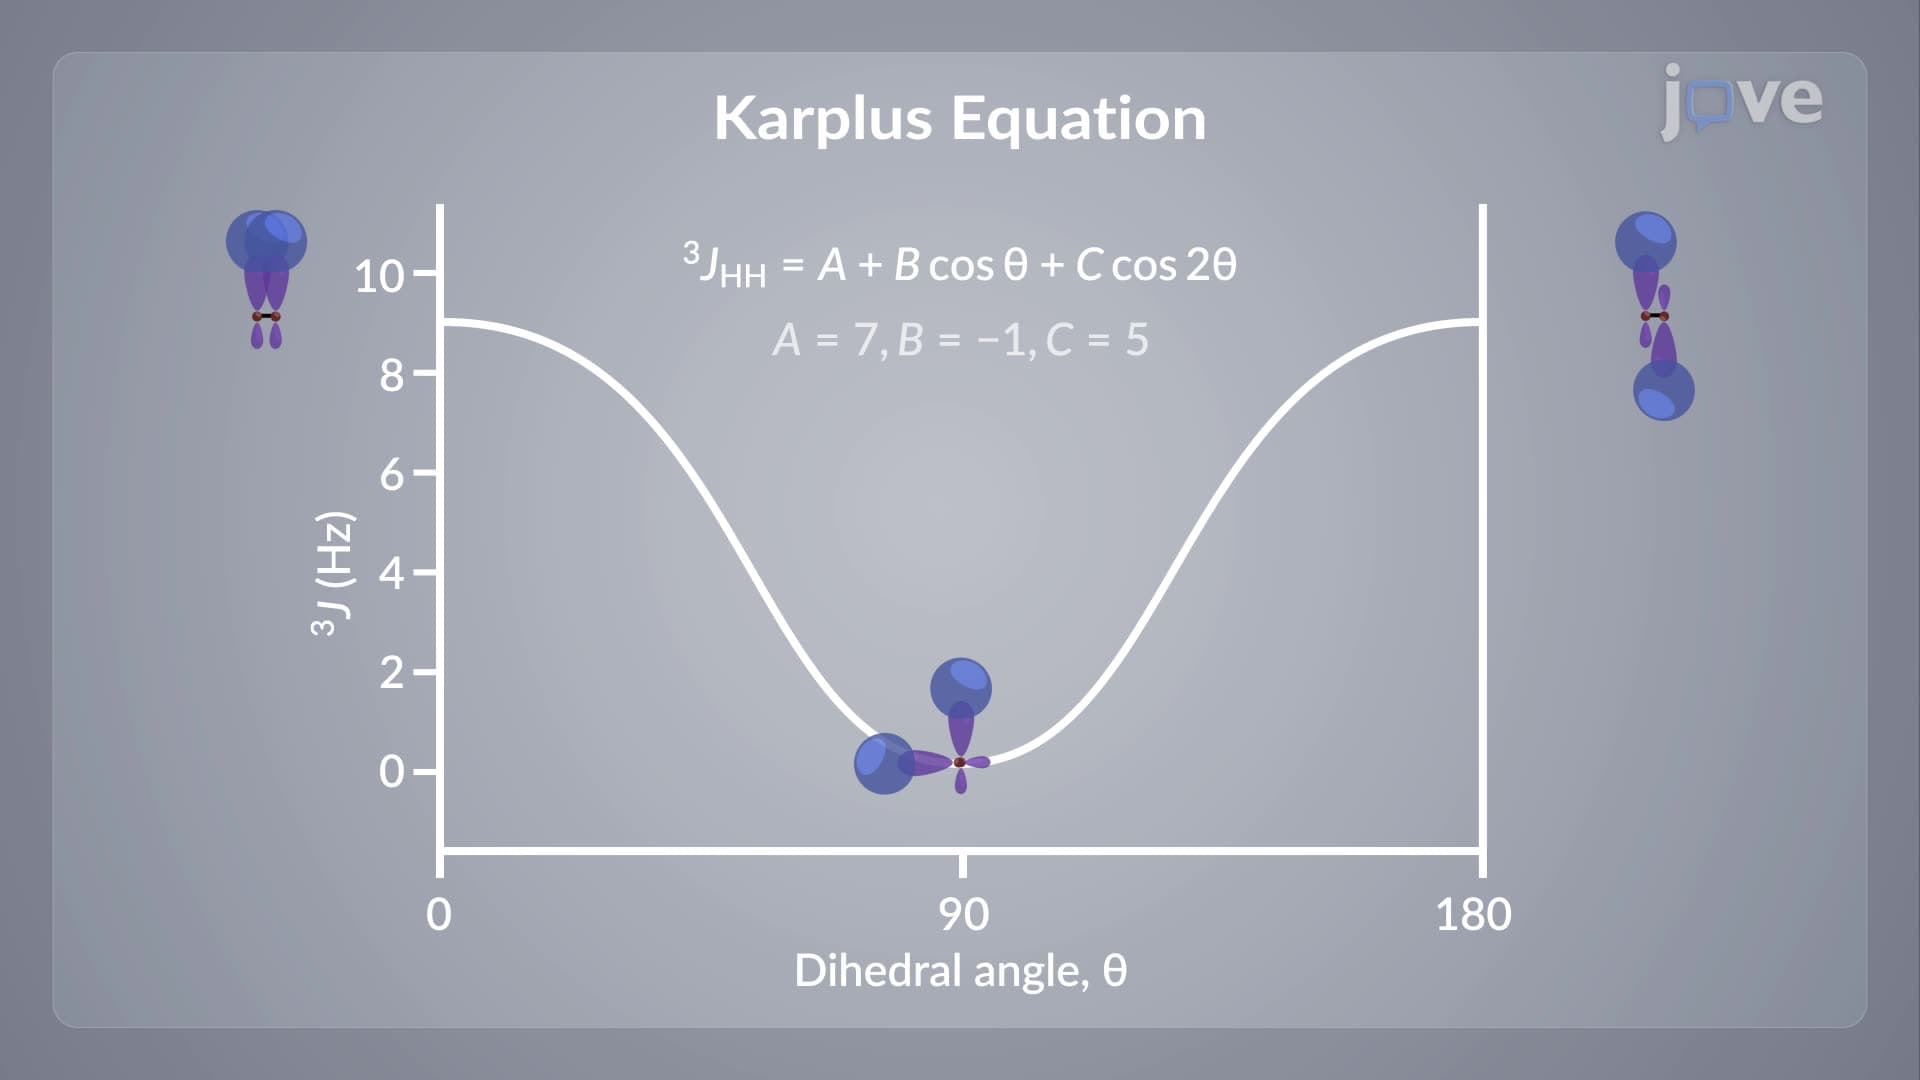
The extent of coupling depends on the C‑C bond length, the two H‑C‑C angles, any electron-withdrawing substituents, and the dihedral angle between the...
 00:59
Uncertainty: Overview
 00:54
Uncertainty: Confidence Intervals