Related Experiment Video
Updated: Aug 23, 2025

An R-Based Landscape Validation of a Competing Risk Model
Published on: September 16, 2022
Robust portfolio optimization for banking foundations: a CVaR approach for asset allocation with mandatory
Maria Cristina Arcuri1,2, Gino Gandolfi1,2, Fabrizio Laurini1
1Department of Economics and Management, University of Parma, Via J.F. Kennedy 6, 43125 Parma, Italy.

Abstract:
This paper focuses on an innovative asset allocation strategy for risk averse investors who operate on very long-time horizons, such as endowments and the Italian foundations of banking origin (FBOs). FBOs play a pivotal role in supporting economic, financial and sustainable growth in the long term. In the search for a model which optimizes FBO portfolio choices in the light of regulatory constraints on their sizeable investable portfolio, we highlight the risk-adjusted performances obtained using a robust conditional VaR (R-CVaR) approach-assuming different risk profiles-which corrects some of the Markowitz approach pitfalls and accounts for tail risk. We compare the two models using a buy and hold strategy: the R-CVaR delivers better returns than a Markowitz portfolio, even when those performances are measured with a mean-variance metric.
More Related Videos
 11:53
Spatial Multiobjective Optimization of Agricultural Conservation Practices using a SWAT Model and an Evolutionary Algorithm
Published on: December 9, 2012
 13:54
A Workflow for Lipid Nanoparticle LNP Formulation Optimization using Designed Mixture-Process Experiments and Self-Validated Ensemble Models SVEM
Published on: August 18, 2023
Related Concept Videos
 01:20
Actuarial Approach
Consider the example of a high-risk surgical procedure with significant early-stage mortality. A two-year clinical study is conducted,...
 01:16
Goodness-of-Fit Test
 01:29
Mechanistic Models: Compartment Models in Algorithms for Numerical Problem Solving
In individual population analyses, different algorithms are employed, such as Cauchy's method, which uses a...
 01:19
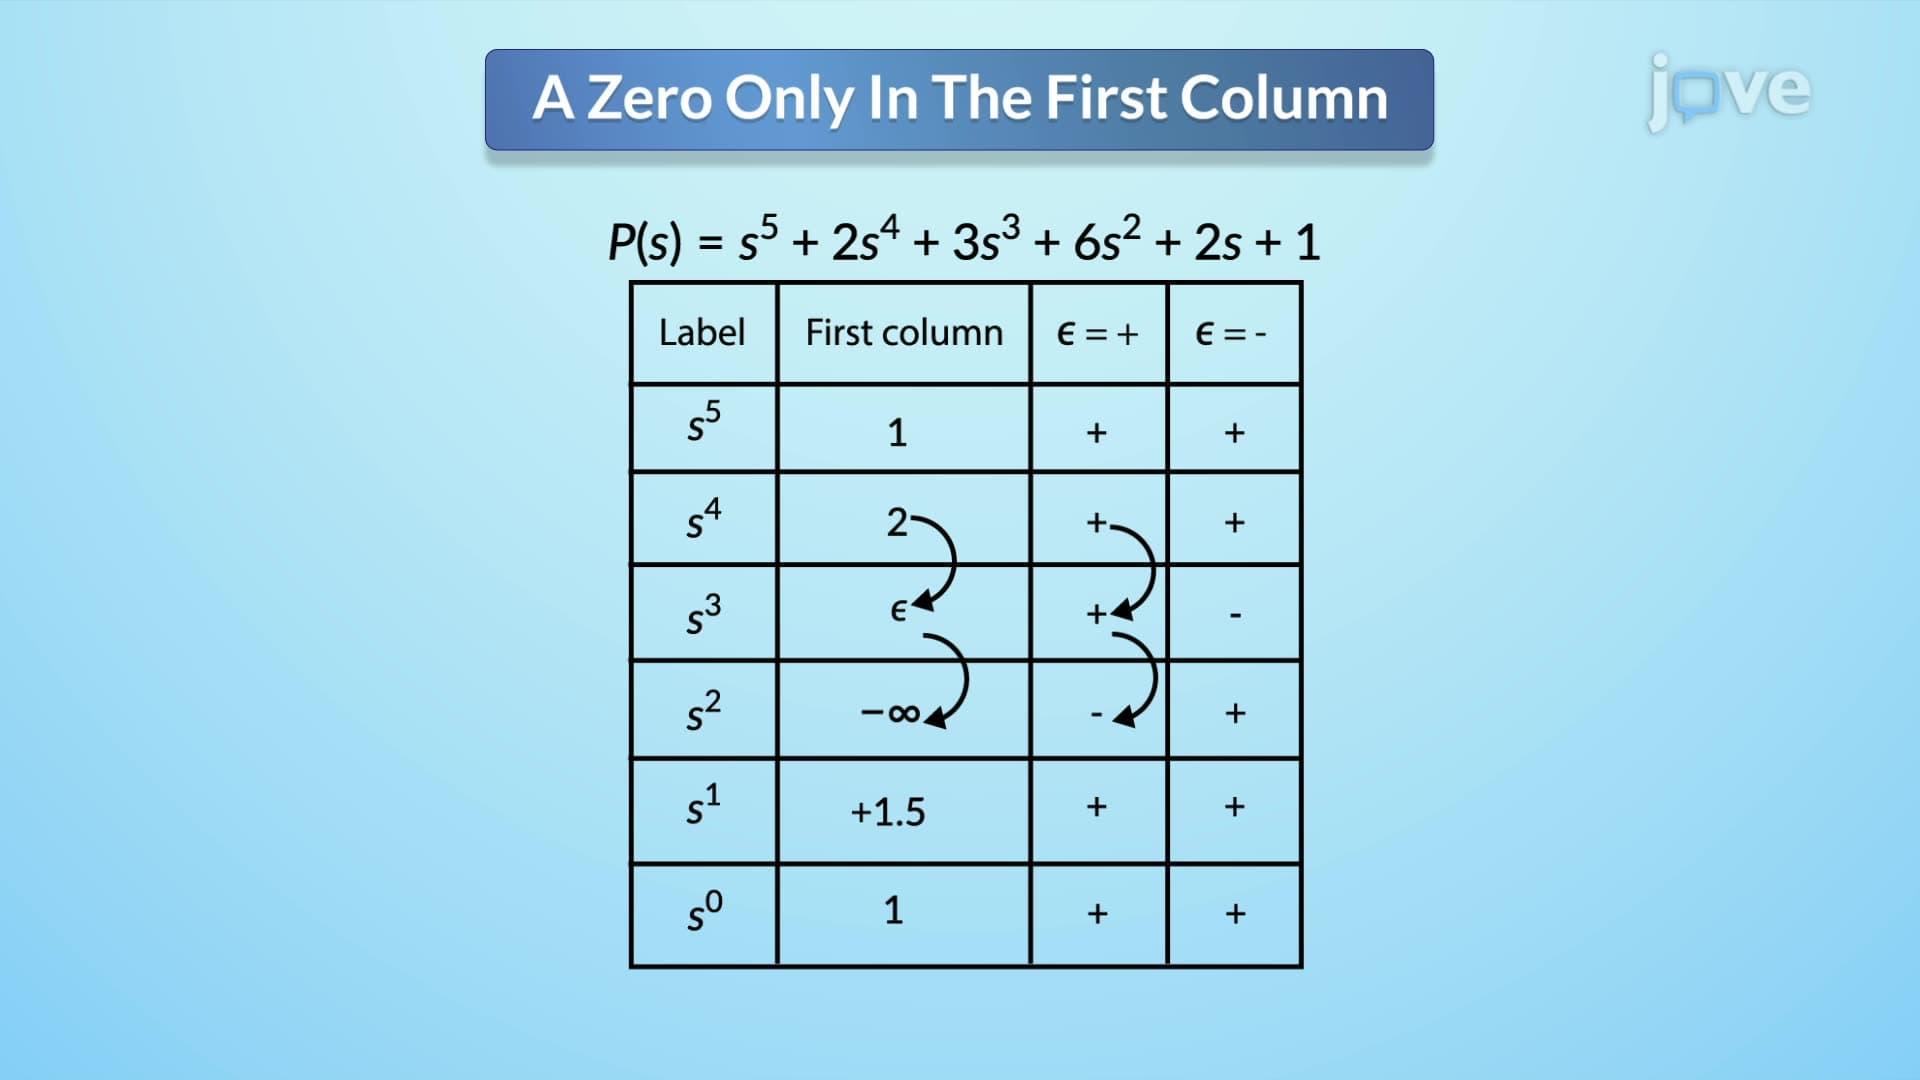
Routh-Hurwitz Criterion II
The first scenario occurs when a singular zero appears in the first column of the Routh table. This situation creates a division by zero issues. To resolve this, a small positive or negative number, denoted as epsilon (∈), is substituted for the zero. The stability analysis proceeds by assuming a sign for ∈. If ∈ is positive, any sign change in the first...
 01:09
Decision Making: P-value Method
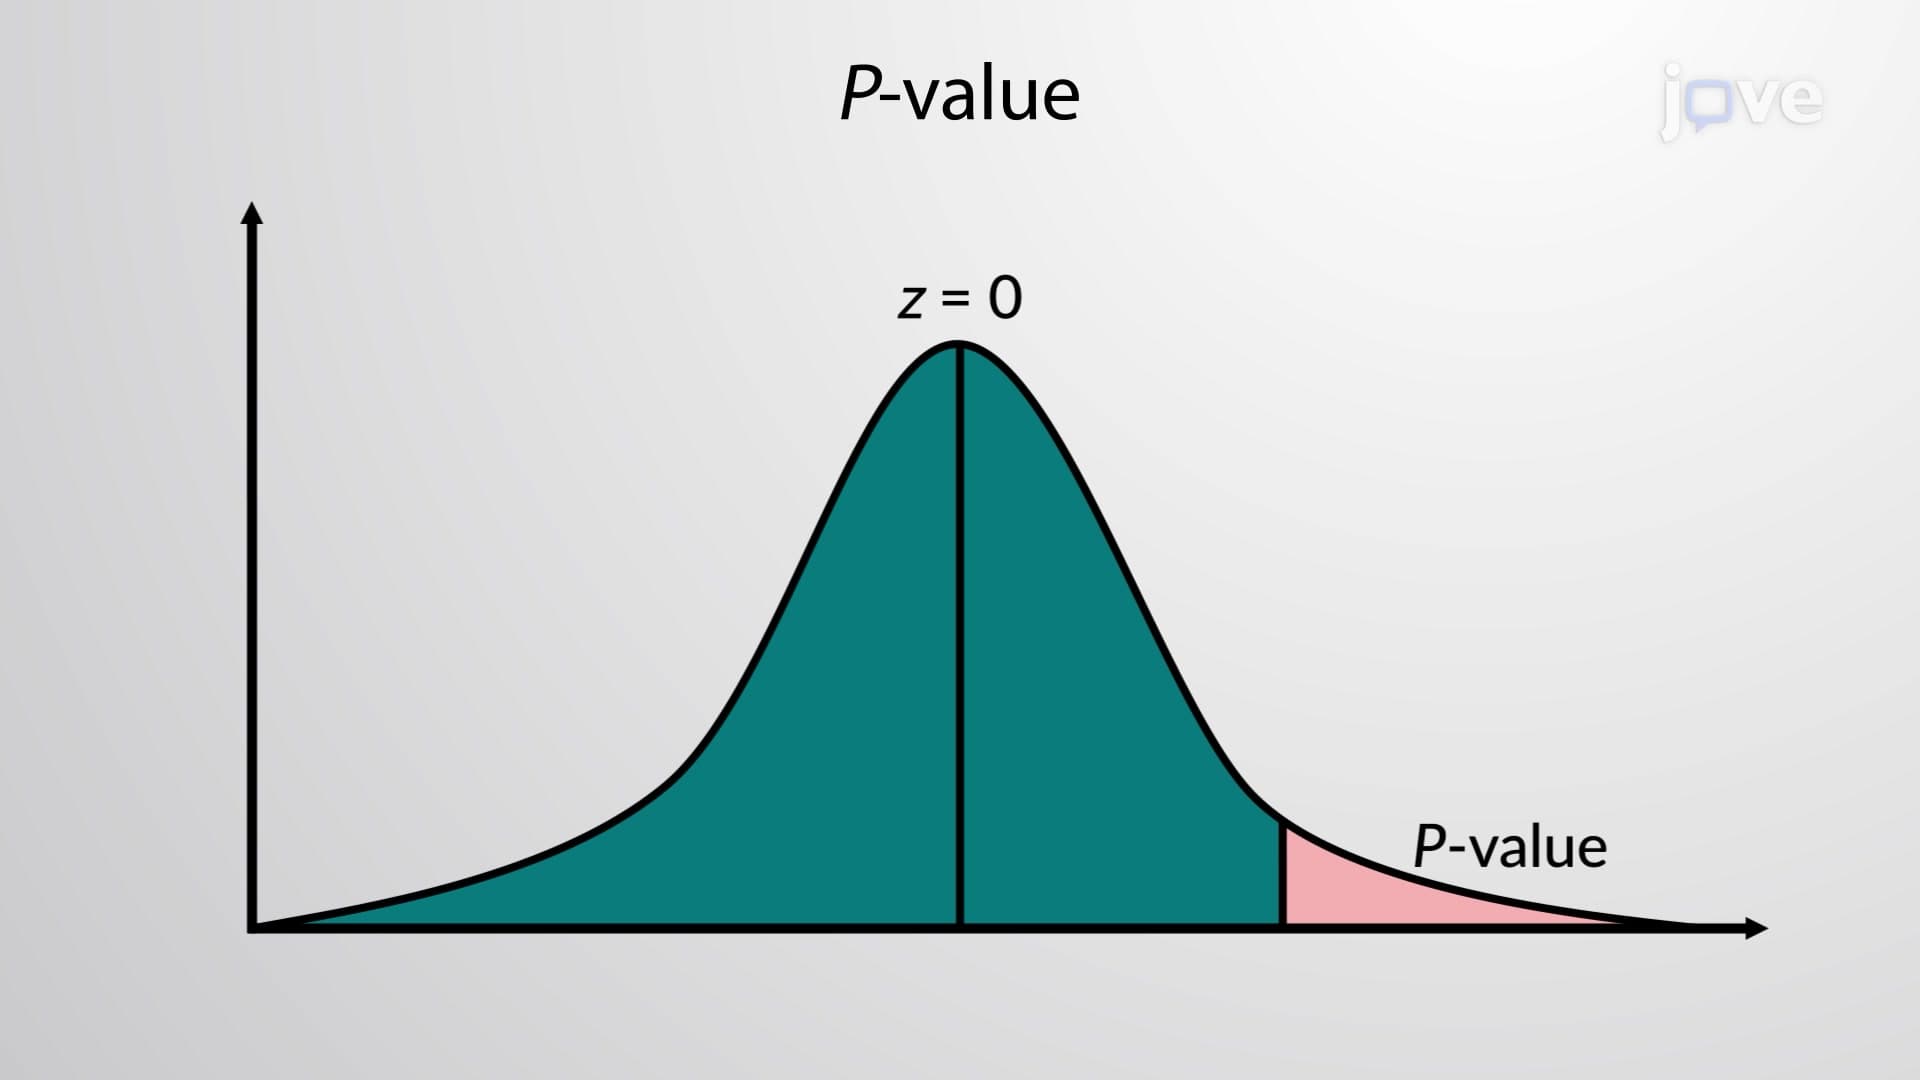
First, a specific claim about the population parameter is proposed. The claim is based on the research question and is stated in a simple form. Further, an opposing statement to the claim is also stated. These statements can act as null and alternative hypotheses: a null hypothesis would be a neutral statement while the alternative hypothesis can...
 01:15
Routh-Hurwitz Criterion I
To apply the Routh-Hurwitz criterion, a Routh table is constructed. The table's rows are labeled with powers of the complex frequency variable s, starting from the...