Related Experiment Video
Updated: Aug 20, 2025
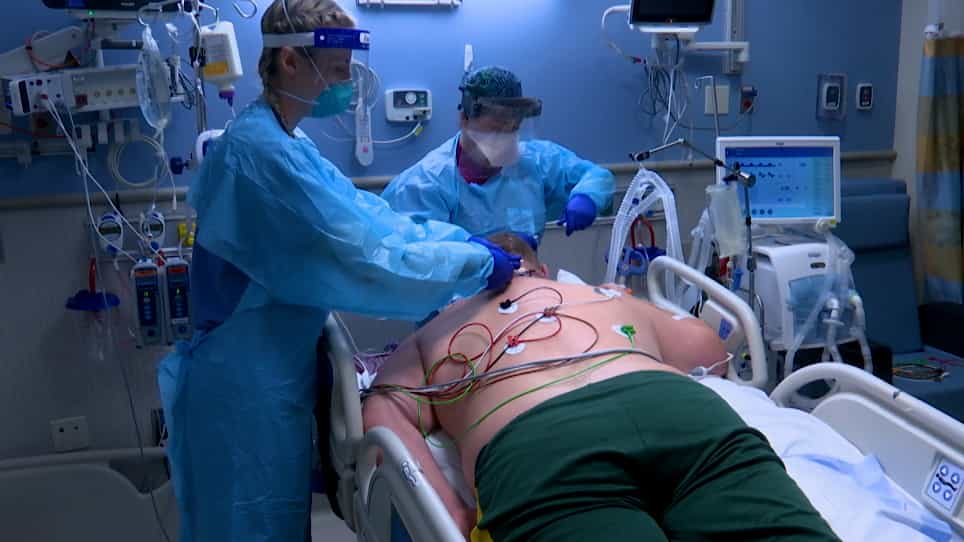
An Educational Video Demonstration of How to Prone a Critically Ill Intubated Patient
Published on: November 30, 2022
Pricing extreme mortality risk in the wake of the COVID-19 pandemic

Abstract:
In pricing extreme mortality risk, it is commonly assumed that interest rate and mortality rate are independent. However, the COVID-19 pandemic calls this assumption into question. In this paper, we employ a bivariate affine jump-diffusion model to describe the joint dynamics of interest rate and excess mortality, allowing for both correlated diffusions and joint jumps. Utilizing the latest U.S. mortality and interest rate data, we find a significant negative correlation between interest rate and excess mortality, and a much higher jump intensity when the pandemic experience is considered. Moreover, we construct a risk-neutral pricing measure that accounts for both diffusion and jump risk premia, and we solve for the market prices of risk based on mortality bond prices. Our results show that the pandemic experience can drastically change investors' perception of the mortality risk market in the post-pandemic era.
Related Concept Videos
 01:12
Relative Risk
 01:20
Actuarial Approach
Consider the example of a high-risk surgical procedure with significant early-stage mortality. A two-year clinical study is conducted,...
 01:27
Psychoneuroimmunology: Cardiovascular Disease
A key area of focus in PNI is the relationship between stress and coronary...
 01:12
Hazard Ratio
For example, in a clinical trial...
 01:17
Measurement of Blood Pressure
 01:29
Bias in Epidemiological Studies