Related Experiment Video
Updated: Aug 19, 2025

Author Spotlight: Emerging Technologies and Advanced Tools for Decoding Metabolomics Data Analysis
Published on: November 10, 2023
Portfolio Selection Based on EMD Denoising with Correlation Coefficient Test Criterion
Kuangxi Su1, Yinhong Yao2, Chengli Zheng3
1School of Mathematics and Statistics, Xinyang Normal University, Xinyang, China.

Abstract:
Noise is an important factor affecting portfolio performance, how to construct an effective denoising strategy is becoming increasingly important for investors. In this study, we theoretically explain the impact of noise on portfolio and argue the necessity of denoising. Next, the empirical mode decomposition (EMD) denoising strategy based on the correlation coefficient test criterion is proposed to improve portfolio performance. In detail, EMD is used to decompose the noisy price, then, a series of correlation coefficient tests are performed to determine which intrinsic mode functions (IMFs) are noise. In the empirical analysis, we apply the proposed method to denoise the SSE 50 index's constituents, and further test the out-of-sample performance under the mean-variance framework. The empirical results show that the proposed denoising method outperforms four common EMD, Ensemble EMD (EEMD) and wavelet denoising methods in return-risk ratio. The proposed method is the optimal denoising strategy, which can help investors improve portfolio performance to the greatest extent.


Related Concept Videos
 01:12
Coefficient of Correlation
If you suspect a linear relationship between x and y, then r can measure how strong the linear relationship is.
What the VALUE of r tells us:
The value of r is always between –1 and +1: –1 ≤ r ≤ 1.
The size of the correlation r indicates the...
 01:19
Expected Frequencies in Goodness-of-Fit Tests
 01:02
Quantifying and Rejecting Outliers: The Grubbs Test
 01:16
Goodness-of-Fit Test
 02:20
Correlations
 00:53
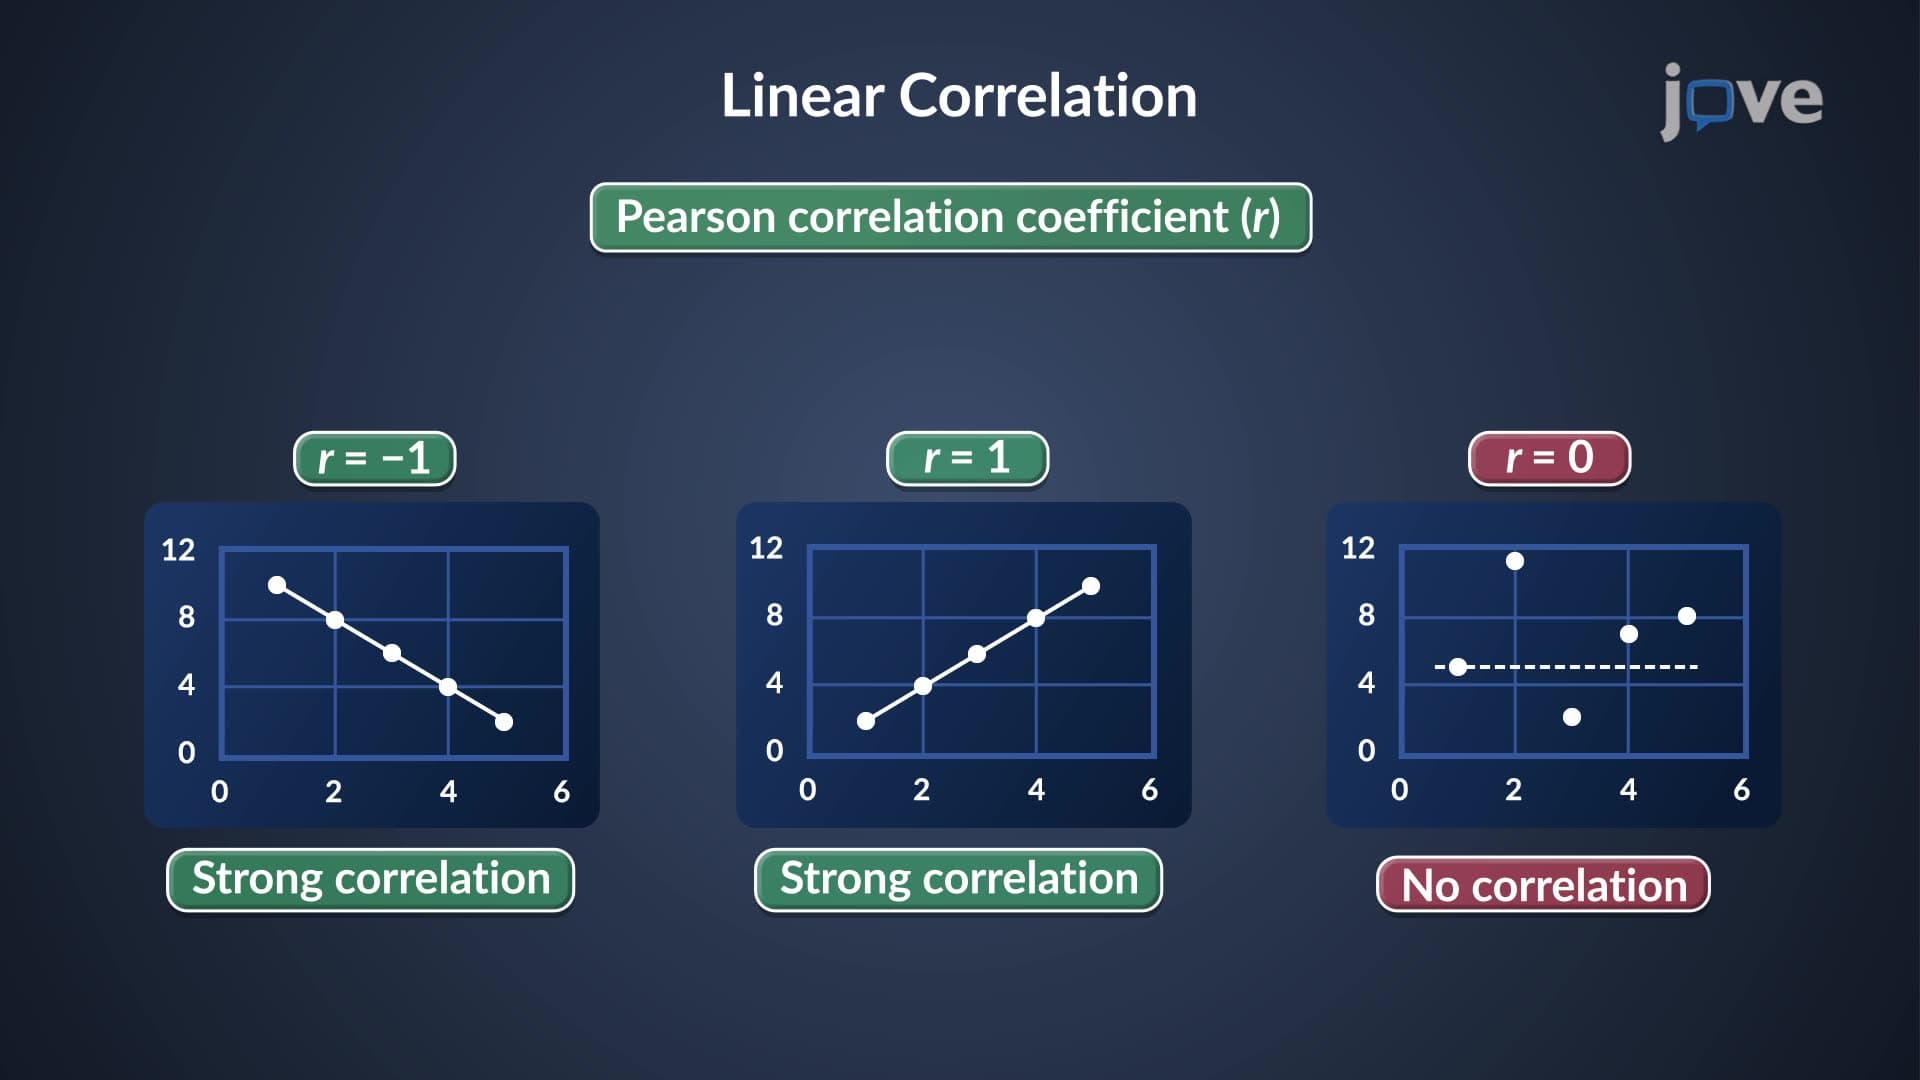
Correlation and Regression