Related Experiment Video
Updated: Aug 18, 2025
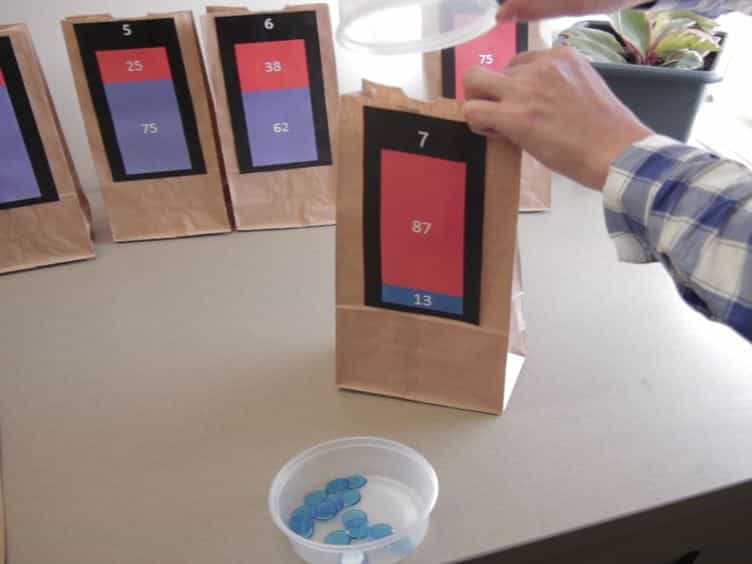

Measuring the Subjective Value of Risky and Ambiguous Options using Experimental Economics and Functional MRI Methods
Published on: September 19, 2012
Impact of management's irrational expectations on corporate tax avoidance: A mediating effect based on level of
1School of Management, Shanghai University of Engineering Science, Shanghai, China.

Abstract:
Frequent tax avoidance incidents have caused huge losses to corporate reputation and corporate value. Research is required on whether and how the irrational judgment of management, a powerful factor in corporate decision-making, affects corporate tax avoidance behavior. Taking all A-share listed companies from 2006 to 2020 as a sample, this paper empirically tests the relationships among management's irrational expectations, level of corporate risk-taking, and level of corporate tax avoidance using an fixed effects regression model (FEM). The results of the three-stage regression model and Sobel test suggest that the level of corporate risk-taking plays a mediating role between managers' irrational expectations and Corporate tax avoidance. The managers' stockholding plays a moderating role in this process. This study also finds evidence that the irrational expectations of management lead to an increase in levels of research and development manipulation, which indirectly increases the level of corporate tax avoidance. Therefore, to control the risk caused by managers' risky decisions, such as R&D manipulation and tax avoidance, it is necessary to lessen the effects of irrational expectations of management, and the management equity incentive plan has been identified as a reliable method in the risk reduction process.
Related Concept Videos
 01:52
Regression Toward the Mean
 01:23
Types of Biopharmaceutical Studies: Controlled and Non-Controlled Approaches
Non-controlled studies, commonly employed for initial exploration, lack a control group, rendering them susceptible to biases and external influences. In contrast,...
 01:14
Fundamental Attribution Error
 01:20
Lazarus's Cognitive Appraisal Theory
Primary Appraisal:...
 02:45
Self-Discrepancy Theory
 03:26
Framing Effects