Related Experiment Video
Updated: Aug 18, 2025

Experimental Investigation of Secondary Flow Structures Downstream of a Model Type IV Stent Failure in a 180° Curved Artery Test Section
Published on: July 19, 2016
Hybrid fuzzy inference rules of descent method and wavelet function for volatility forecasting
Abdullah H Alenezy1,2, Mohd Tahir Ismail2, Jamil J Jaber3
1Department of mathematics, College of Science, University of Ha'il, Hail, Kingdom of Saudi Arabia.

Abstract:
This research employs the gradient descent learning (FIR.DM) approach as a learning process in a nonlinear spectral model of maximum overlapping discrete wavelet transform (MODWT) to improve volatility prediction of daily stock market prices using Saudi Arabia's stock exchange (Tadawul) data. The MODWT comprises five mathematical functions and fuzzy inference rules. The inputs are the oil price (Loil) and repo rate (Repo) according to multiple regression correlation, and the Engle and Granger Causality test Engle RF, (1987). The logarithm of the stock market price (LSCS) in Tadawul reflects the output variable. The correlation matrix reveals that there is no collinearity between the input variables, and the causality test demonstrates that the input variables significantly influence the outcome variable. According to the multiple regression, there is a substantial negative influence between Loil and LSCS but a significant positive effect between Repo and output. For the 80% dataset under ME (0.000005), MAE (0.003214), and MAPE (0.064497), the MODWT-LA8 (ARIMA(1,1,0) with drift) for the LSCS variable performs better than other WT functions. In the novel hybrid model MODWT-FIR.DM, each function's approximation coefficient (LSCS) is applied with input variables (Loil and Repo). We evaluate the performance of the proposed model (MODWT-LA8-FIR.DM) using different statistical measures (ME, RMSE, MAE, MPE) and compare it to two established models: the original FIR.DM and other MODWT-FIR.DM functions for forecasting 20% of datasets. The outcomes show that the MODWT-LA8-FIR.DM performs better than the traditional models based on lower ME (3.167586), RMSE (3.167638), MAE (3.167586), and MPE (80.860849). The proposed hybrid model may be a potential stock market forecasting model.
More Related Videos
 08:27
Author Spotlight: Efficient Image Recognition Using Directional Gradient Histogram Technique and Support Vector Machines
Published on: January 5, 2024
 08:42
Measurement of the Directional Information Flow in fNIRS-Hyperscanning Data using the Partial Wavelet Transform Coherence Method
Published on: September 3, 2021
Related Concept Videos
 01:03
Prediction Intervals
However, the point estimate is most likely not the exact value of the population parameter, but close to it. After calculating point estimates, we construct interval estimates, called confidence intervals or prediction intervals. This prediction interval comprises a range of values unlike the point estimate and is a better predictor of the observed sample value, y.
 01:30
Classification of Signals
A continuous-time signal holds a value at every instant in time, representing information seamlessly. In contrast, a discrete-time signal holds values only at specific moments, often denoted as x(n), where...
 01:22
Multi-input and Multi-variable systems
In the absence...
 01:09
Empirical Method to Interpret Standard Deviation
This rule is used widely in statistics to calculate the proportion of data values...
 01:17
Design Example: Analyzing Capacity Contours for Flood Risk Assessment
 01:13
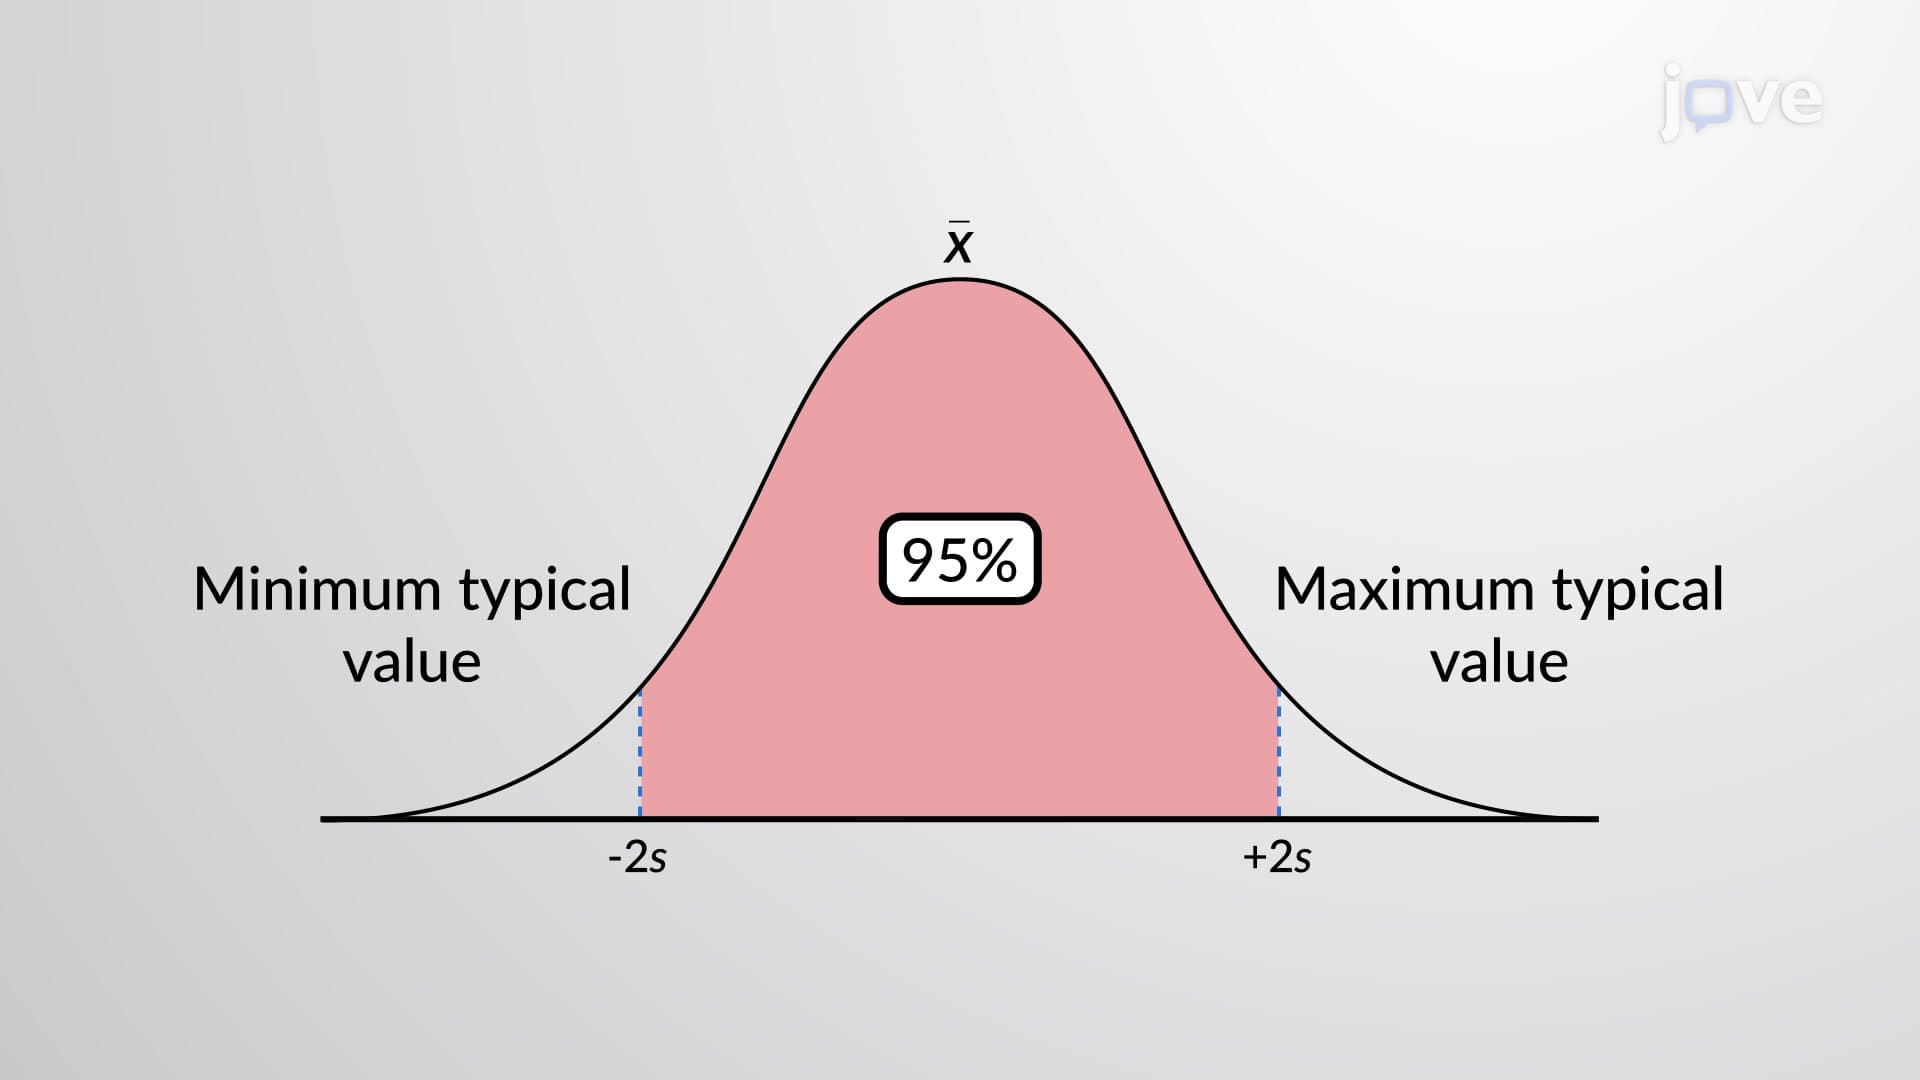
Range Rule of Thumb to Interpret Standard Deviation
For instance, the range rule of thumb can be used to find the tallest and the shortest student in a class, given the mean student height and standard deviation. If the mean student height is 1.6 m and the standard deviation, s is 0.05 m, the height...