Related Experiment Video
Updated: Aug 16, 2025

An R-Based Landscape Validation of a Competing Risk Model
Published on: September 16, 2022
The impact of Covid-19 on G7 stock markets volatility: Evidence from a ST-HAR model
Marwan Izzeldin1, Yaz Gülnur Muradoğlu2, Vasileios Pappas3
1Lancaster University, Lancaster, LA1 4YW, UK.

Abstract:
We investigate the impact of Covid-19 on stock markets across G7 countries and their business sectors. We highlight the synchronicity and severity of this unprecedented crisis. We find strong transition evidence to a crisis regime in all countries and sectors, yet crisis intensity and timings vary. The Health Care and Consumer services sectors were the most severely affected; a reflection of the Covid-19 drug-race and international travel restrictions. The Technology sector was hit the latest and least severely, as imposed lockdown measures forced people to explore various web-based entertainment and distraction options. Country-wise the UK and the US were the most affected with the highest heterogeneity in their business sectors' response; a possible reflection of the ambiguity in the initial response and adoption of lockdown measures. Financial markets' response to Covid-19 is akin to response in previous financial crisis rather than previous pandemics. A series of robustness checks confirms our findings.
Related Concept Videos
 01:29
Econometric Views (EViews)
 01:13
Stress Concentrations
The stress...
 01:14
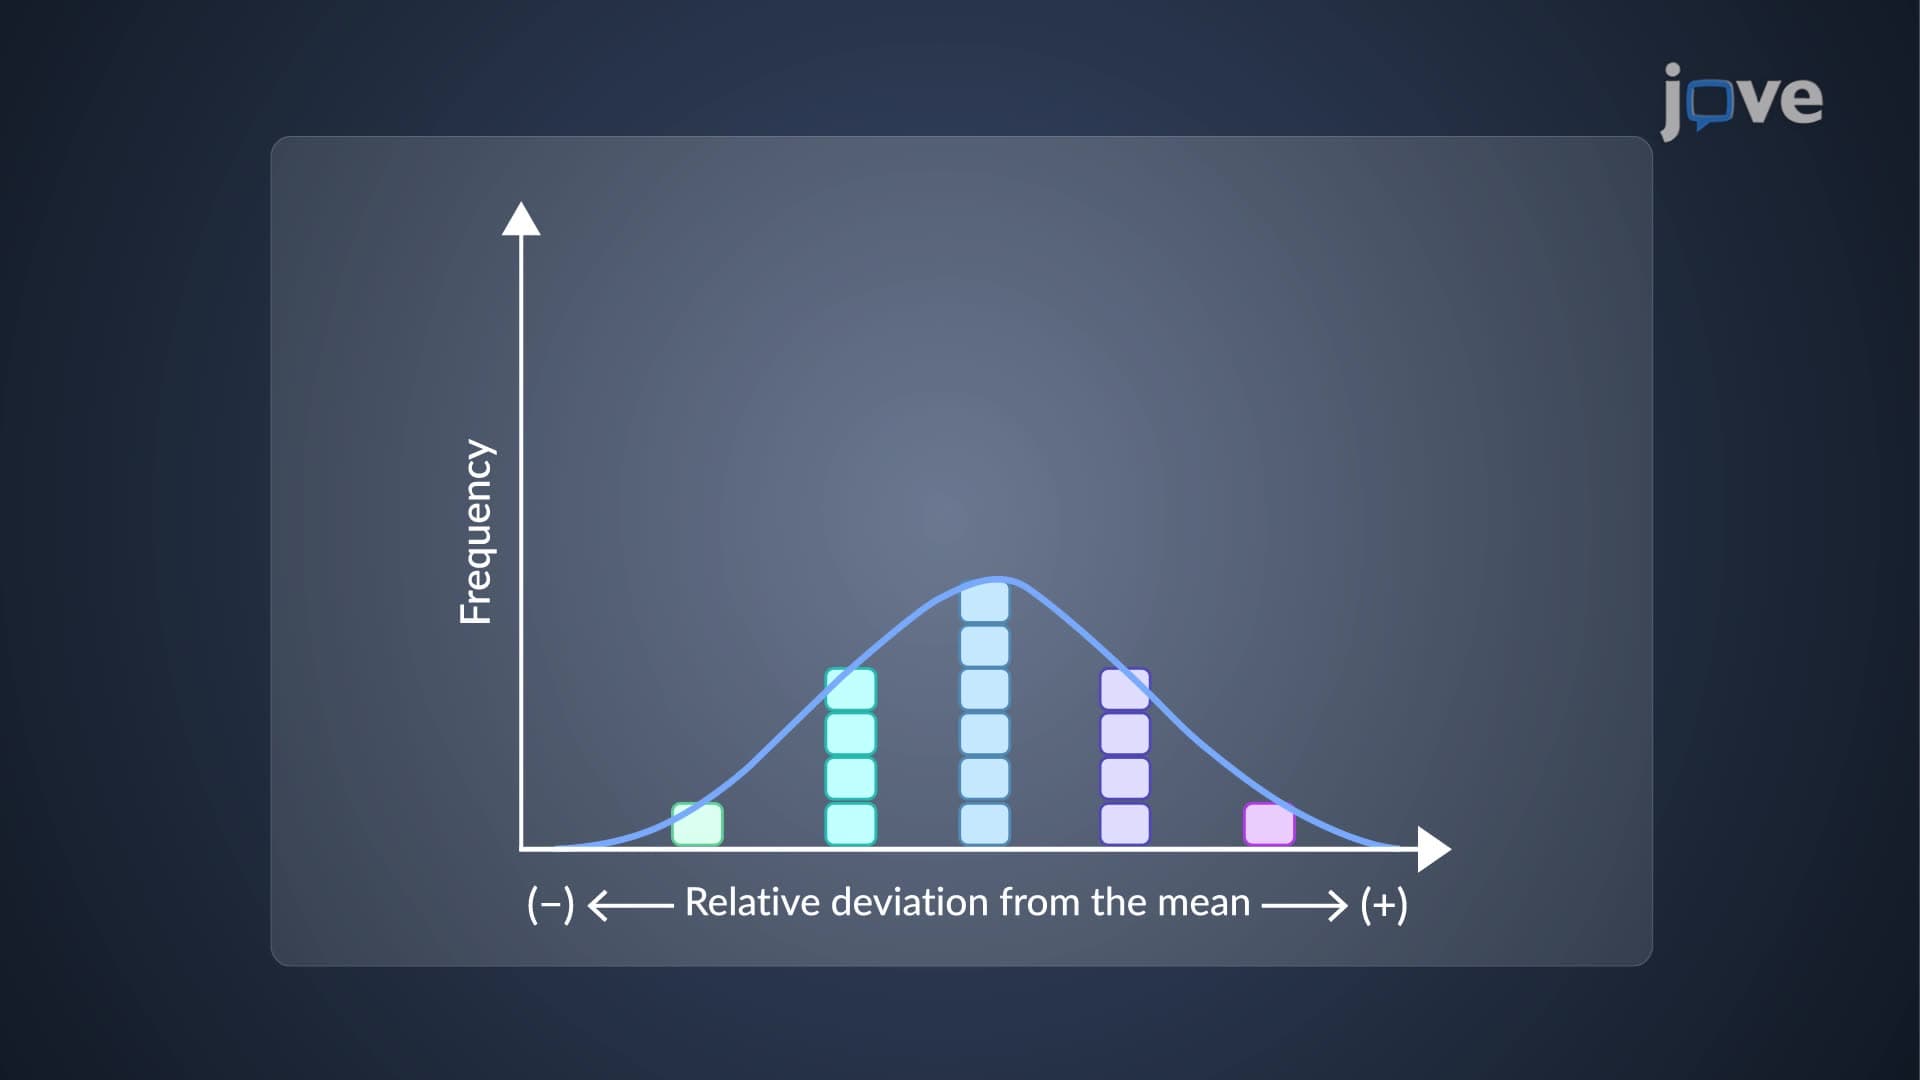
Standard Deviation of Calculated Results
A broad Gaussian distribution curve has a wider standard deviation, representing a data set with...
 01:12
Hazard Ratio
For example, in a clinical trial...
 01:09
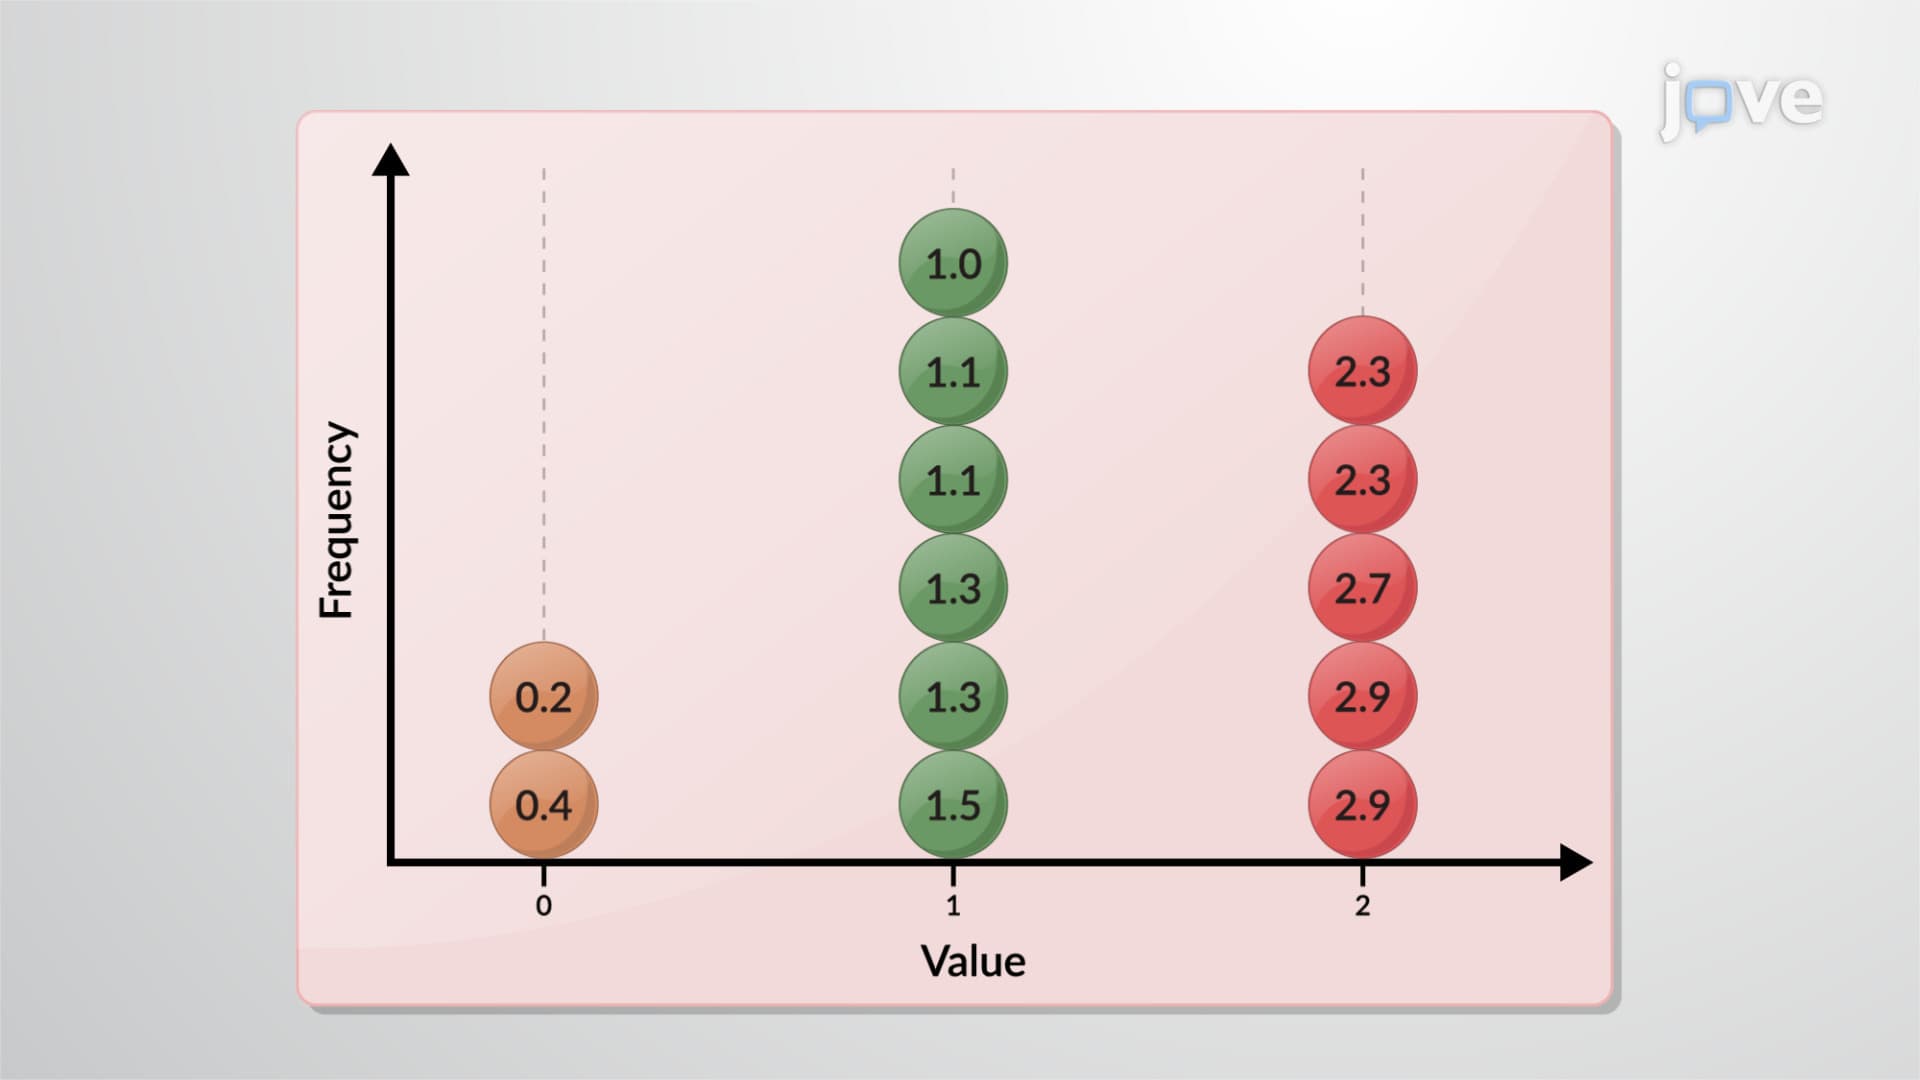
Empirical Method to Interpret Standard Deviation
This rule is used widely in statistics to calculate the proportion of data values...
 01:11
Variability: Analysis
The range is a simple measure of variability, indicating the difference between the highest and...