Related Experiment Video
Updated: Aug 12, 2025

A Method of Trigonometric Modelling of Seasonal Variation Demonstrated with Multiple Sclerosis Relapse Data
Published on: December 9, 2015
Time series momentum: Evidence from the European equity market
Darko B Vukovic1,2, Salvatore Ingenito3, Moinak Maiti4
1International Laboratory for Finance and Financial Markets, Faculty of Economics, People's Friendship University of Russia (RUDN University), 6 Miklukho-Maklaya str., 117198, Moscow, Russia.

Abstract:
This study empirically analyzes time series momentum (TSM) in the European equity market between 2000 & 2020. The study produces additional evidence on TSM where a significant and persistent market price anomaly enables investors to earn abnormal returns. To achieve this goal the present study implements a pooled autoregressive model to test the predictability power of European equity indices of future returns. The results indicate that strategies based on TSM are in line with the discussed literature and enable market agents to earn returns above the market (0.71% per month) by using a six-factor model.
More Related Videos
 11:15
Applications of EEG Neuroimaging Data: Event-related Potentials, Spectral Power, and Multiscale Entropy
Published on: June 27, 2013
 11:06
Bilateral Assessment of the Corticospinal Pathways of the Ankle Muscles Using Navigated Transcranial Magnetic Stimulation
Published on: February 19, 2019
Related Concept Videos
 00:54
Time-Series Graph
 01:09
Moment-of-Momentum Equation
 00:56
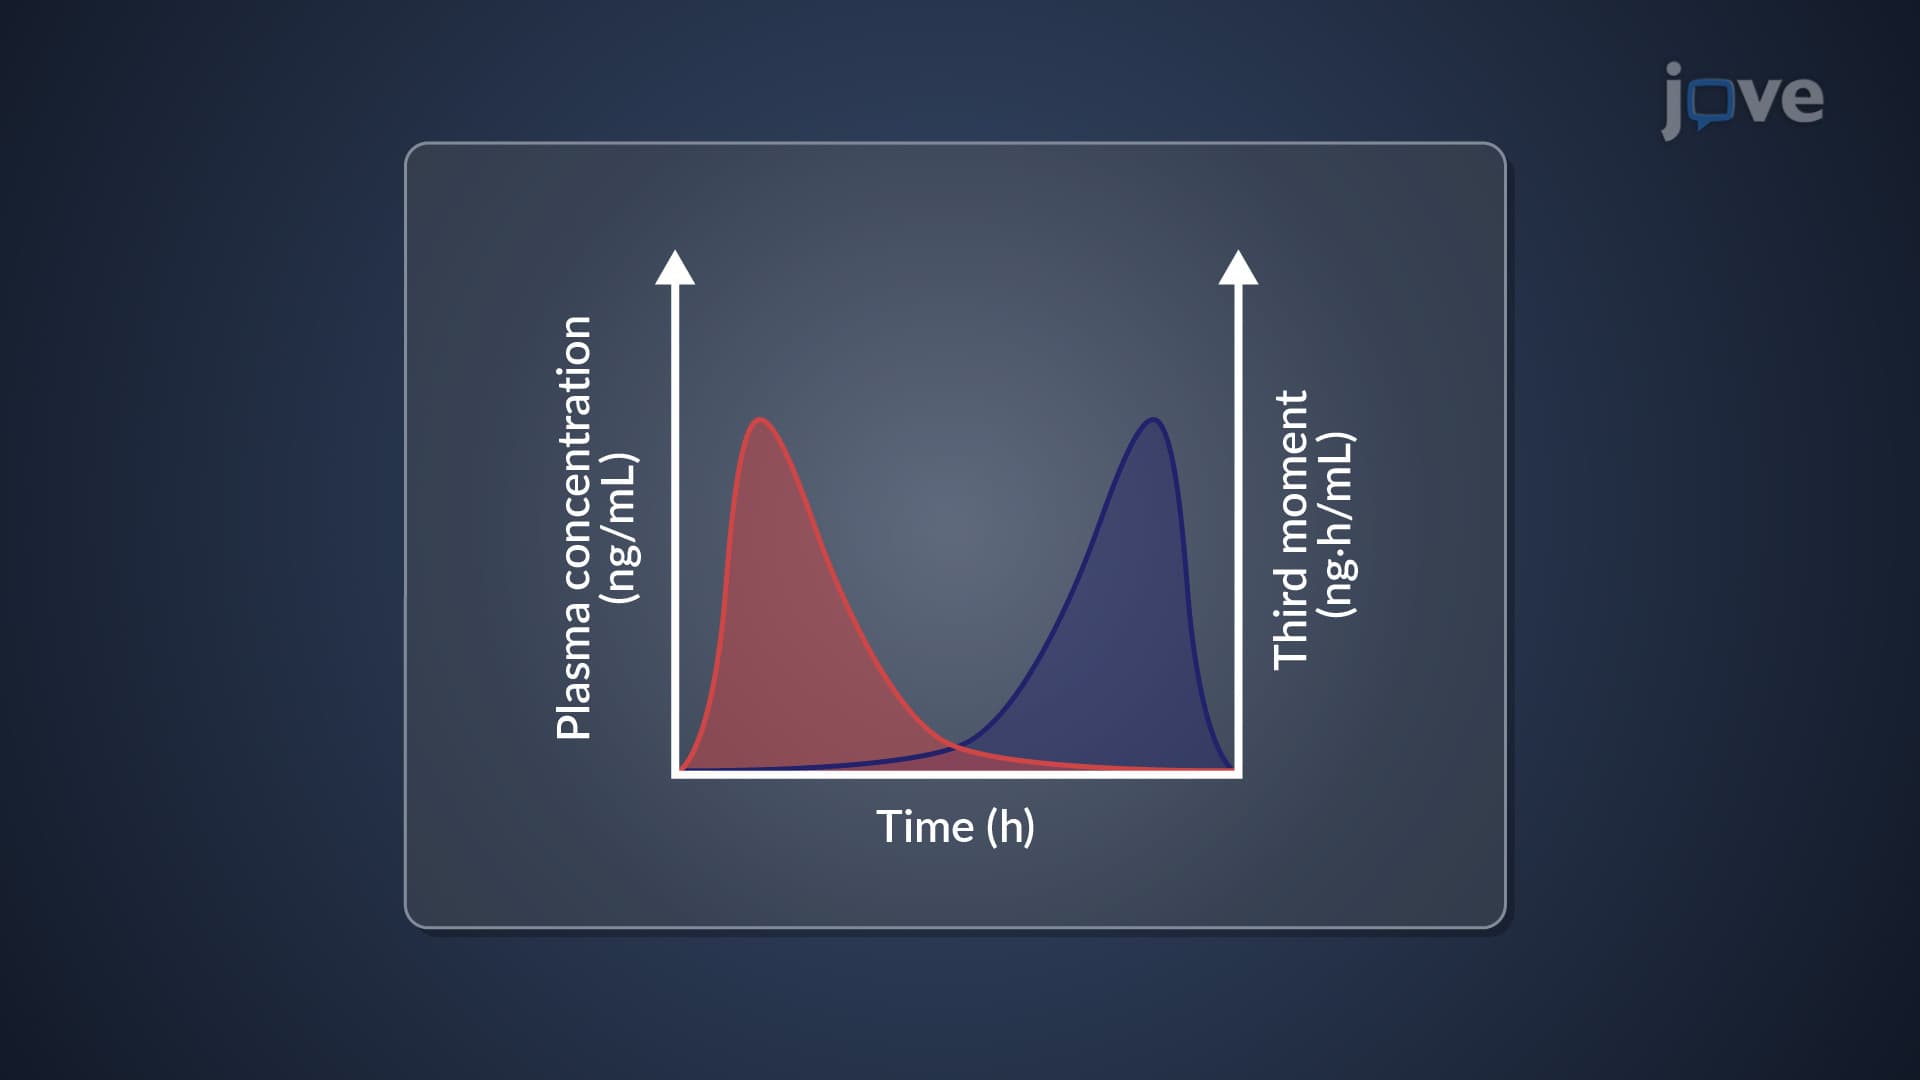
Noncompartmental Analysis: Statistical Moment Theory
 00:55
Linear Momentum
 01:13
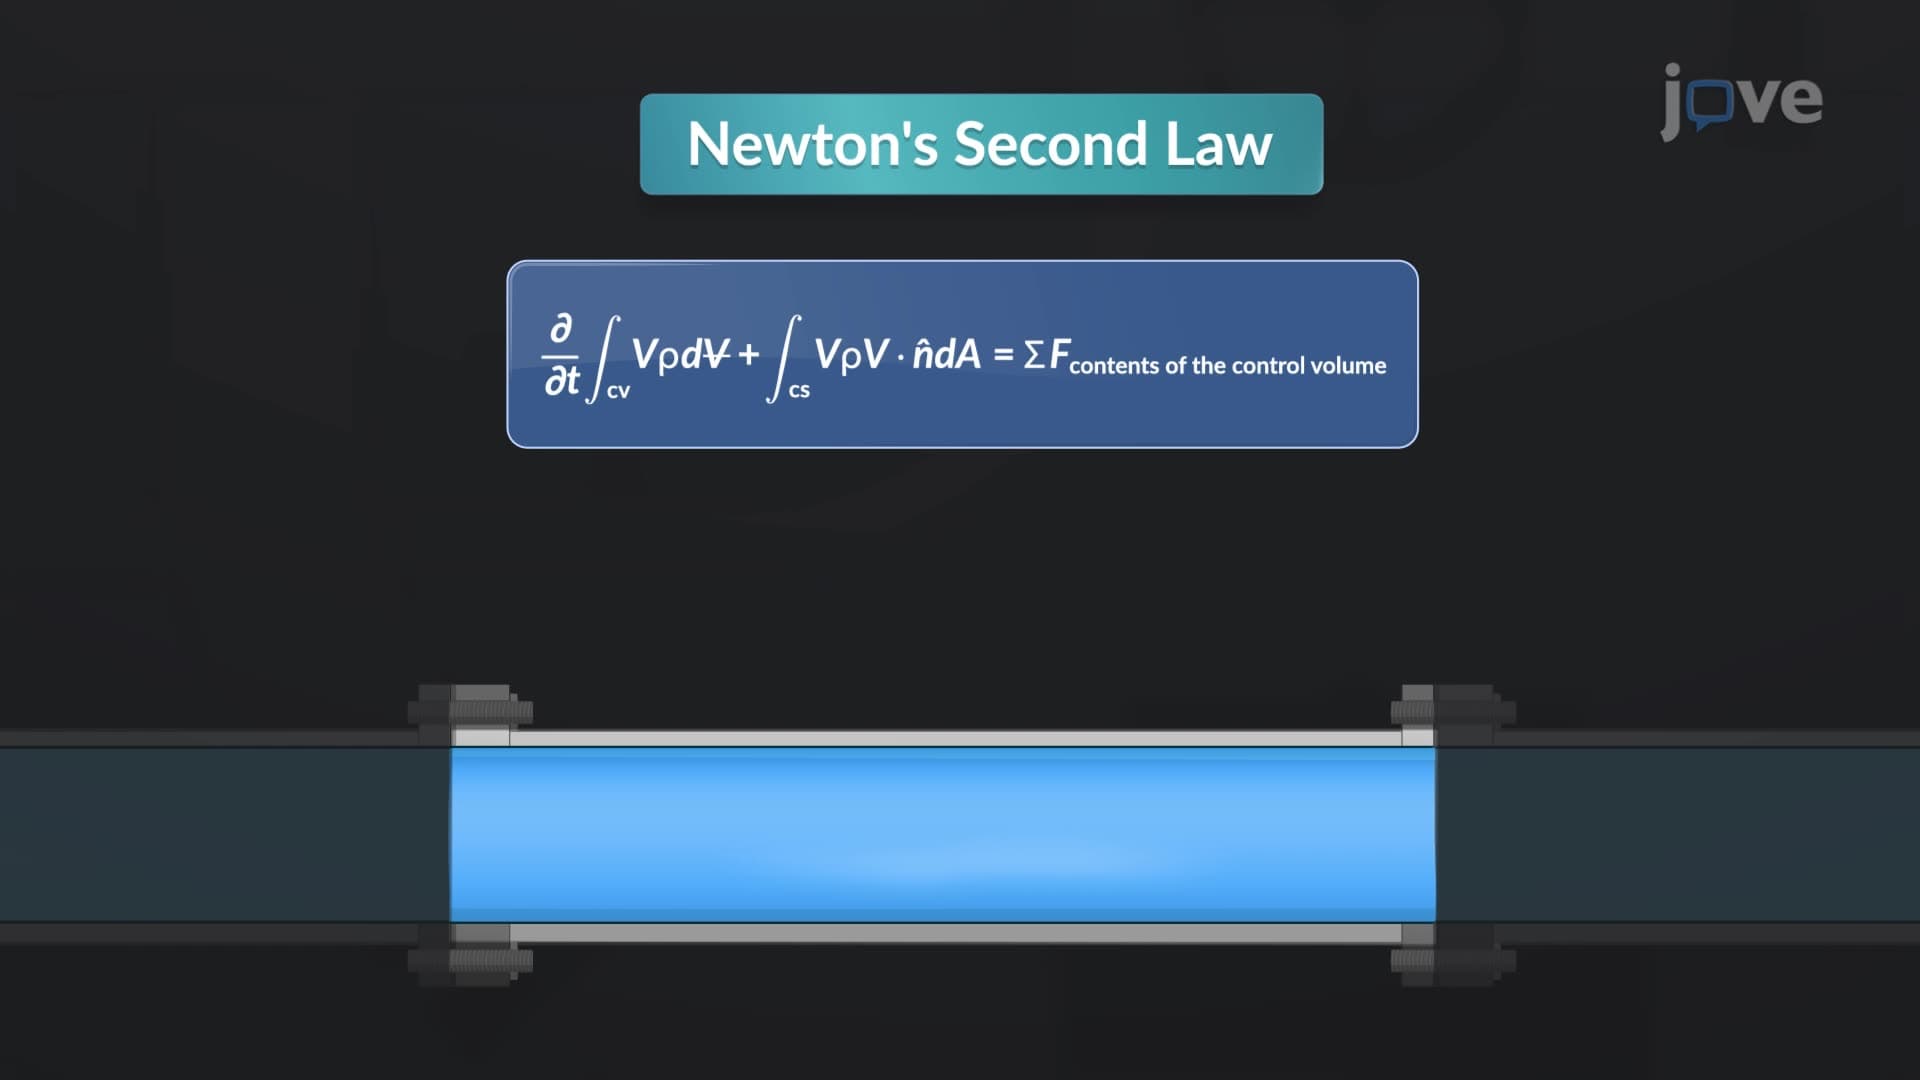
Linear Momentum in Control Volume
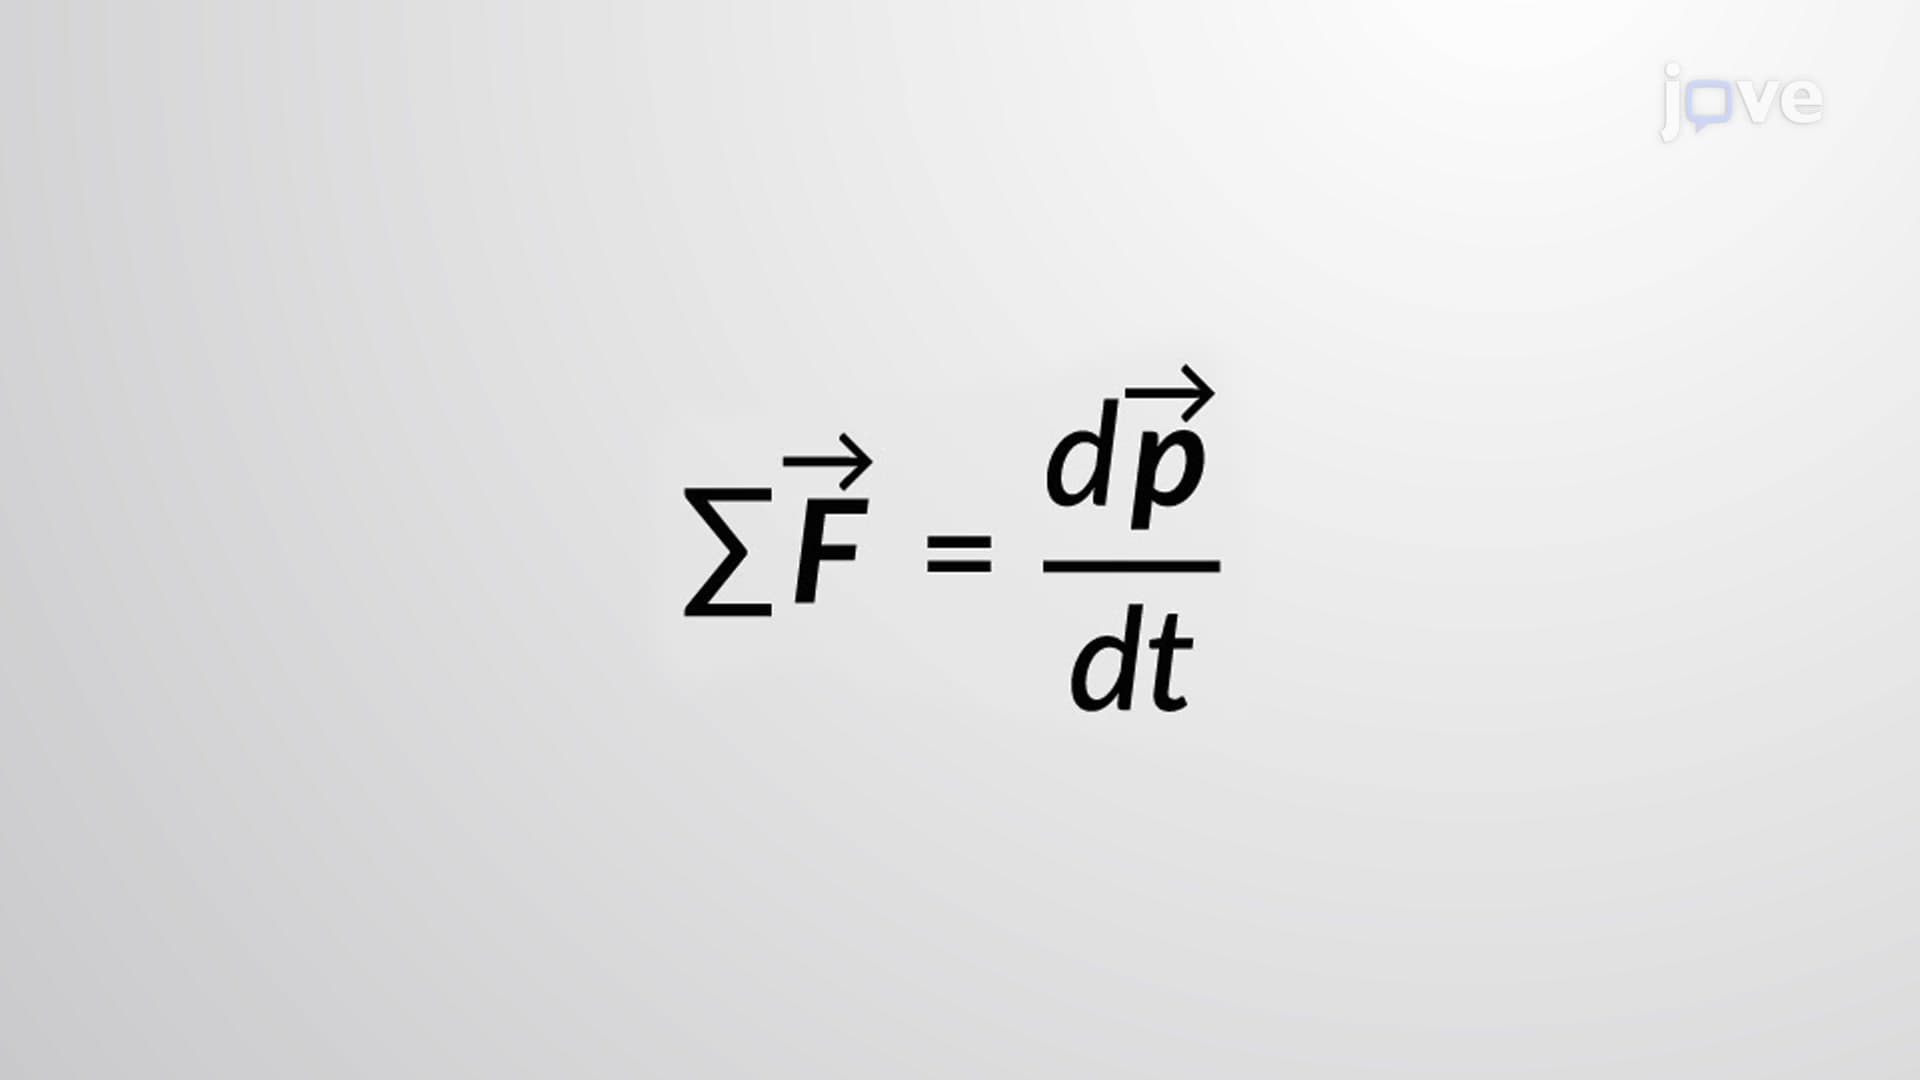 01:17
Force and Momentum