Related Experiment Video
Updated: Aug 7, 2025

Measuring the Subjective Value of Risky and Ambiguous Options using Experimental Economics and Functional MRI Methods
Published on: September 19, 2012
The predictive power of Bitcoin prices for the realized volatility of US stock sector returns
Elie Bouri1, Afees A Salisu2,3, Rangan Gupta3
1School of Business, Lebanese American University, Byblos, Lebanon.

Abstract:
This paper is motivated by Bitcoin's rapid ascension into mainstream finance and recent evidence of a strong relationship between Bitcoin and US stock markets. It is also motivated by a lack of empirical studies on whether Bitcoin prices contain useful information for the volatility of US stock returns, particularly at the sectoral level of data. We specifically assess Bitcoin prices' ability to predict the volatility of US composite and sectoral stock indices using both in-sample and out-of-sample analyses over multiple forecast horizons, based on daily data from November 22, 2017, to December, 30, 2021. The findings show that Bitcoin prices have significant predictive power for US stock volatility, with an inverse relationship between Bitcoin prices and stock sector volatility. Regardless of the stock sectors or number of forecast horizons, the model that includes Bitcoin prices consistently outperforms the benchmark historical average model. These findings are independent of the volatility measure used. Using Bitcoin prices as a predictor yields higher economic gains. These findings emphasize the importance and utility of tracking Bitcoin prices when forecasting the volatility of US stock sectors, which is important for practitioners and policymakers.
More Related Videos
 10:46
A Method of Trigonometric Modelling of Seasonal Variation Demonstrated with Multiple Sclerosis Relapse Data
Published on: December 9, 2015
 08:27
Author Spotlight: Efficient Image Recognition Using Directional Gradient Histogram Technique and Support Vector Machines
Published on: January 5, 2024
Related Concept Videos
 01:03
Prediction Intervals
However, the point estimate is most likely not the exact value of the population parameter, but close to it. After calculating point estimates, we construct interval estimates, called confidence intervals or prediction intervals. This prediction interval comprises a range of values unlike the point estimate and is a better predictor of the observed sample value, y.
 01:19
Testing a Claim about Standard Deviation
The hypothesis testing for the claim of population standard deviation (or variance) requires the data and samples to be random and unbiased. The population distribution also must be normal. There is no specific requirement on the sample size as the estimation is based on the chi-square distribution.
As a first step, the hypothesis (null and alternative) concerning the claim about...
 01:15
Expected Value
 01:09
Empirical Method to Interpret Standard Deviation
This rule is used widely in statistics to calculate the proportion of data values...
 01:11
Residuals and Least-Squares Property
If the observed data point lies above the line, the residual is positive, and the line underestimates the actual data value for y. If the observed data point lies below the line, the residual is negative, and the line overestimates the actual data value for y.
The process of fitting the best-fit...
 01:10
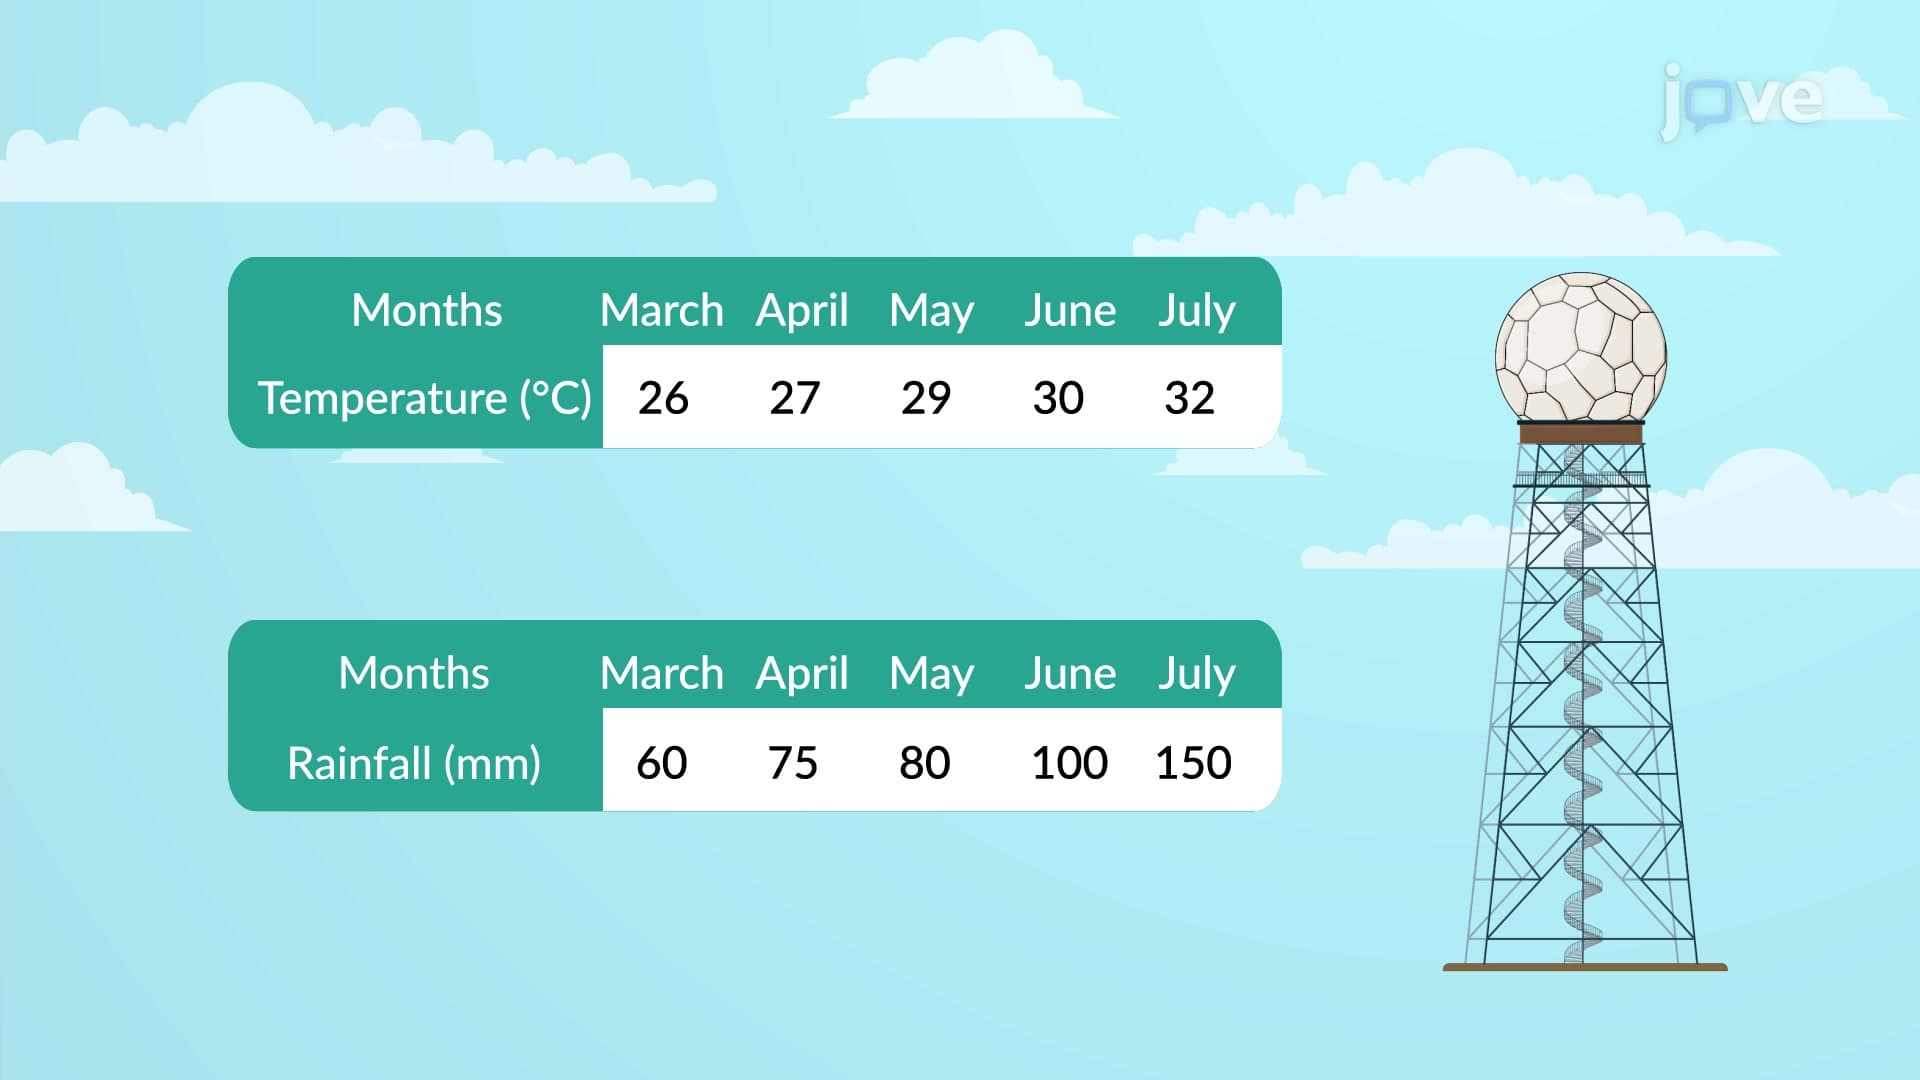
Coefficient of Variation
The coefficient of variation is a practical statistical tool in finance. It allows investors to assess the volatility or...