Turn-of-the-candle effect in bitcoin returns
Related Experiment Video
Updated: Aug 6, 2025
Observation and Analysis of Blinking Surface-enhanced Raman Scattering
Published on: January 11, 2018
Savva Shanaev1, Mikhail Vasenin1, Roman Stepanov1
1University of Northumbria at Newcastle, United Kingdom, NE8 1ST, UK.

Abstract:
This study discovers a statistically and economically significant intraday anomaly on Bitcoin markets. Positive returns of 0.58 bps per minute are disproportionately concentrated at the turn of 15-min candles (in minutes 0, 15, 30, and 45 of each trading hour). Average returns in other trading minutes are negative. The effect is consistent across Bitcoin exchanges, in quantile regression models, and TGARCH-M estimations with heavy tails, and persist in out-of-sample tests. A high-frequency strategy that exploits this "turn-of-the-candle" effect can be net-outperforming with initial investment as low as $5,000. The anomaly is detected in the data starting from mid-to-late 2020, is potentially associated with algorithmic trading relying on the arrival of 15-min candle information, and its discovery contributes significantly to the understanding of cryptocurrency adaptive market efficiency.
Related Concept Videos
 01:07
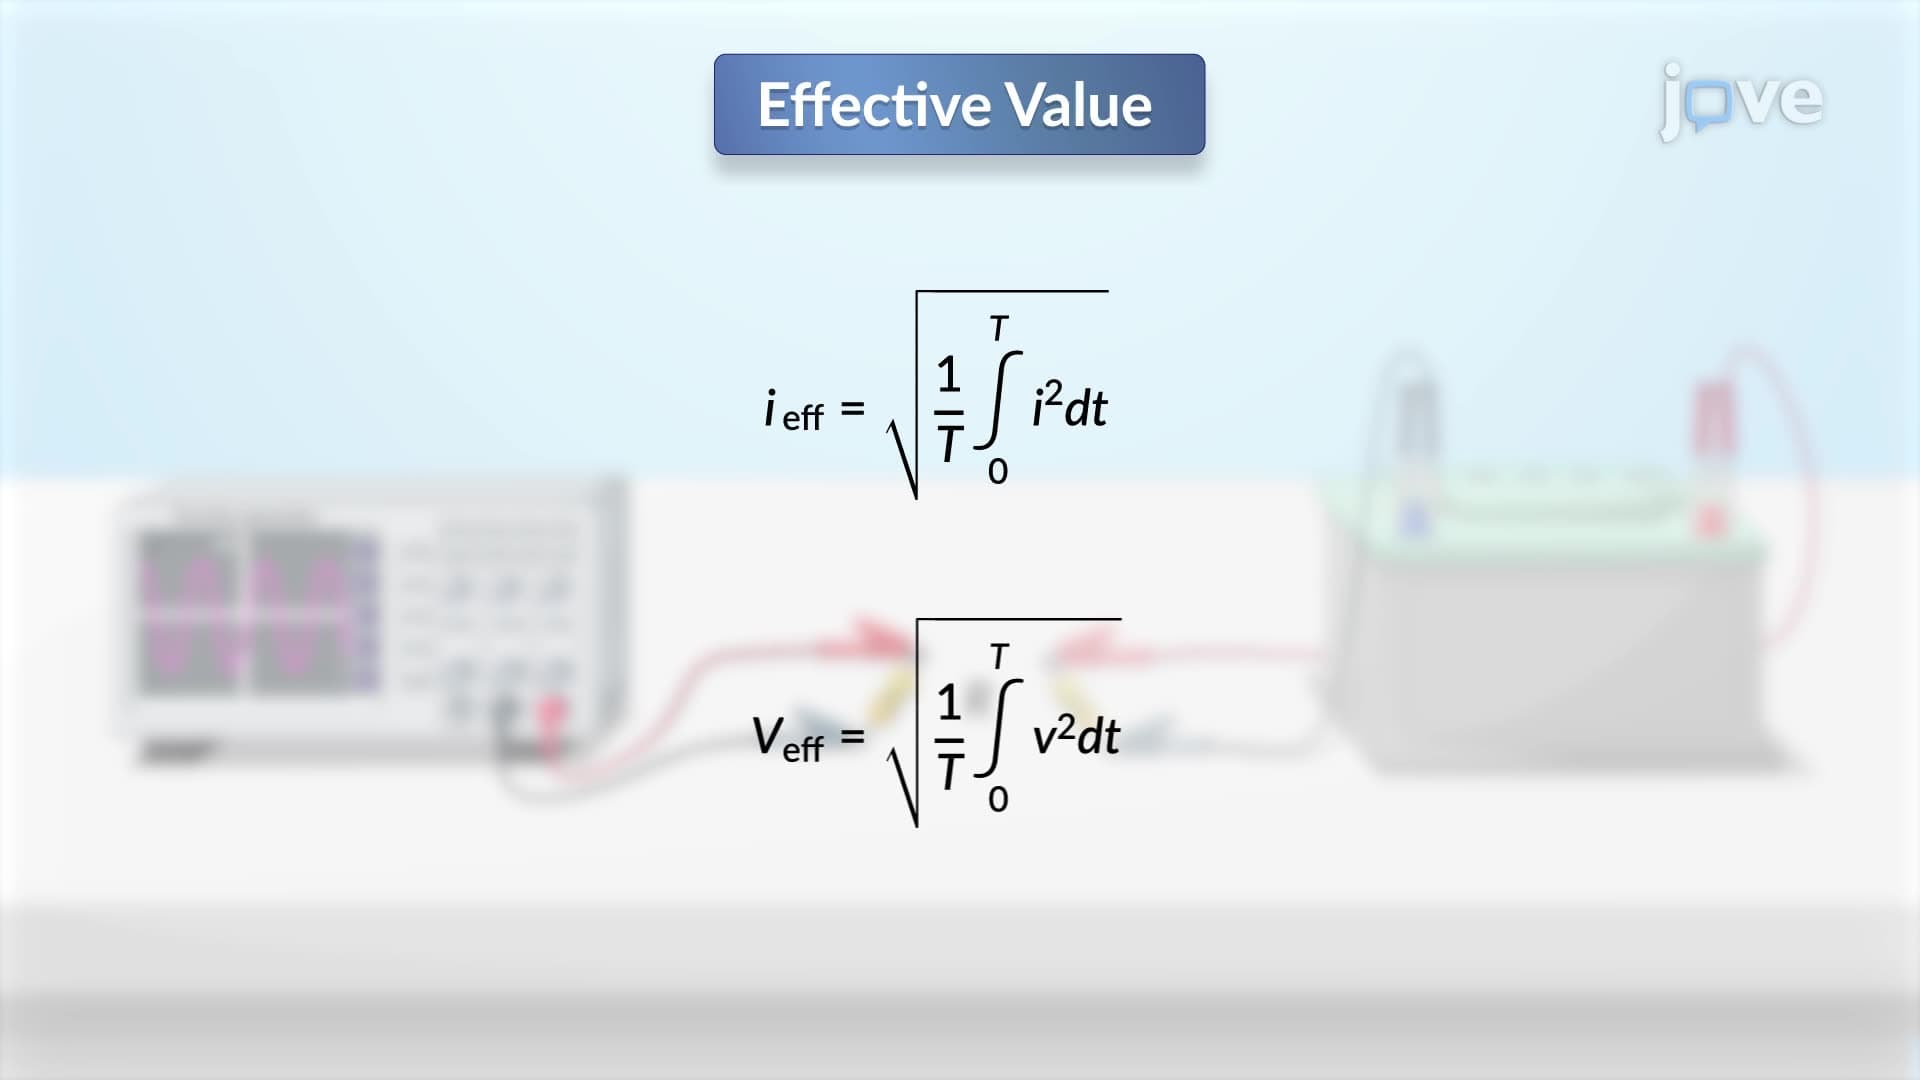
Effective Value of a Periodic Waveform
The effective value of a periodic current represents the direct current (DC) that conveys the same average power to a resistor as the periodic current itself. This concept is crucial when assessing AC circuits. To determine the...
 00:58
Significant Figures in Calculations
 01:18
Benzene to 1,4-Cyclohexadiene: Birch Reduction Mechanism
 02:35
Clausius-Clapeyron Equation
 01:28
Reduction of Benzene to Cyclohexane: Catalytic Hydrogenation
 01:16
Basic Discrete Time Signals
The unit impulse or sample sequence is mathematically expressed as zero for all n values except at n=0, where it is one. The unit impulse sequence, denoted by δ(n), is the first difference of the unit step sequence, while the unit step sequence u(n) is...