Related Experiment Video
Updated: Jul 30, 2025
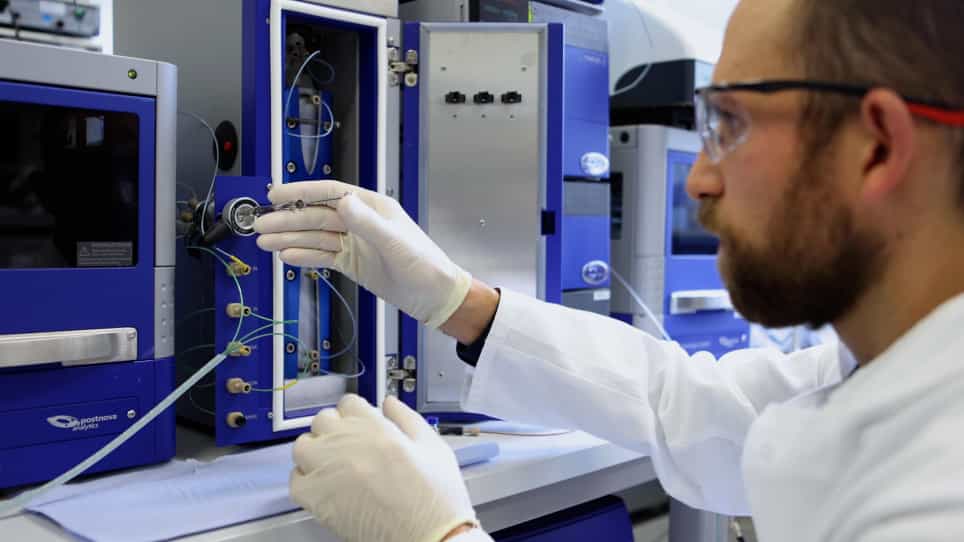

Asymmetrical Flow Field-Flow Fractionation for Sizing of Gold Nanoparticles in Suspension
Published on: September 11, 2020
Tail spillover effects between cryptocurrencies and uncertainty in the gold, oil, and stock markets
Walid Mensi1,2, Mariya Gubareva3, Hee-Un Ko4
1Department of Economics and Finance, College of Economics and Political Science, Sultan Qaboos University, Muscat, Oman.

Abstract:
This study investigates tail dependence among five major cryptocurrencies, namely Bitcoin, Ethereum, Litecoin, Ripple, and Bitcoin Cash, and uncertainties in the gold, oil, and equity markets. Using the cross-quantilogram method and quantile connectedness approach, we identify cross-quantile interdependence between the analyzed variables. Our results show that the spillover between cryptocurrencies and volatility indices for the major traditional markets varies substantially across quantiles, implying that diversification benefits for these assets may differ widely across normal and extreme market conditions. Under normal market conditions, the total connectedness index is moderate and falls below the elevated values observed under bearish and bullish market conditions. Moreover, we show that under all market conditions, cryptocurrencies have a leadership influence over the volatility indices. Our results have important policy implications for enhancing financial stability and deliver valuable insights for deploying volatility-based financial instruments that can potentially provide cryptocurrency investors with suitable hedges, as we show that cryptocurrency and volatility markets are insignificantly (weakly) connected under normal (extreme) market conditions.
More Related Videos
Related Concept Videos
 00:59
Uncertainty: Overview
 00:59
Propagation of Uncertainty from Random Error
 01:07
Residual Plots
When the residual values are plotted against the variable x, it is called a residual...
 01:10
Propagation of Uncertainty from Systematic Error
 00:54
Uncertainty: Confidence Intervals
 01:53
Cause and Effect