Related Experiment Video
Updated: Jul 30, 2025

Measuring the Subjective Value of Risky and Ambiguous Options using Experimental Economics and Functional MRI Methods
Published on: September 19, 2012
Upside and downside correlated jump risk premia of currency options and expected returns
Jie-Cao He1, Hsing-Hua Chang1, Ting-Fu Chen2
1Department of Money and Banking, National Chengchi University, Taipei, Taiwan.

Abstract:
This research explores upside and downside jumps in the dynamic processes of three rates: domestic interest rates, foreign interest rates, and exchange rates. To fill the gap between the asymmetric jump in the currency market and the current models, a correlated asymmetric jump model is proposed to capture the co-movement of the correlated jump risks for the three rates and identify the correlated jump risk premia. The likelihood ratio test results show that the new model performs best in 1-, 3-, 6-, and 12-month maturities. The in- and out-of-sample test results indicate that the new model can capture more risk factors with relatively small pricing errors. Finally, the risk factors captured by the new model can explain the exchange rate fluctuations for various economic events.

Related Concept Videos
 01:15
Expected Value
 01:09
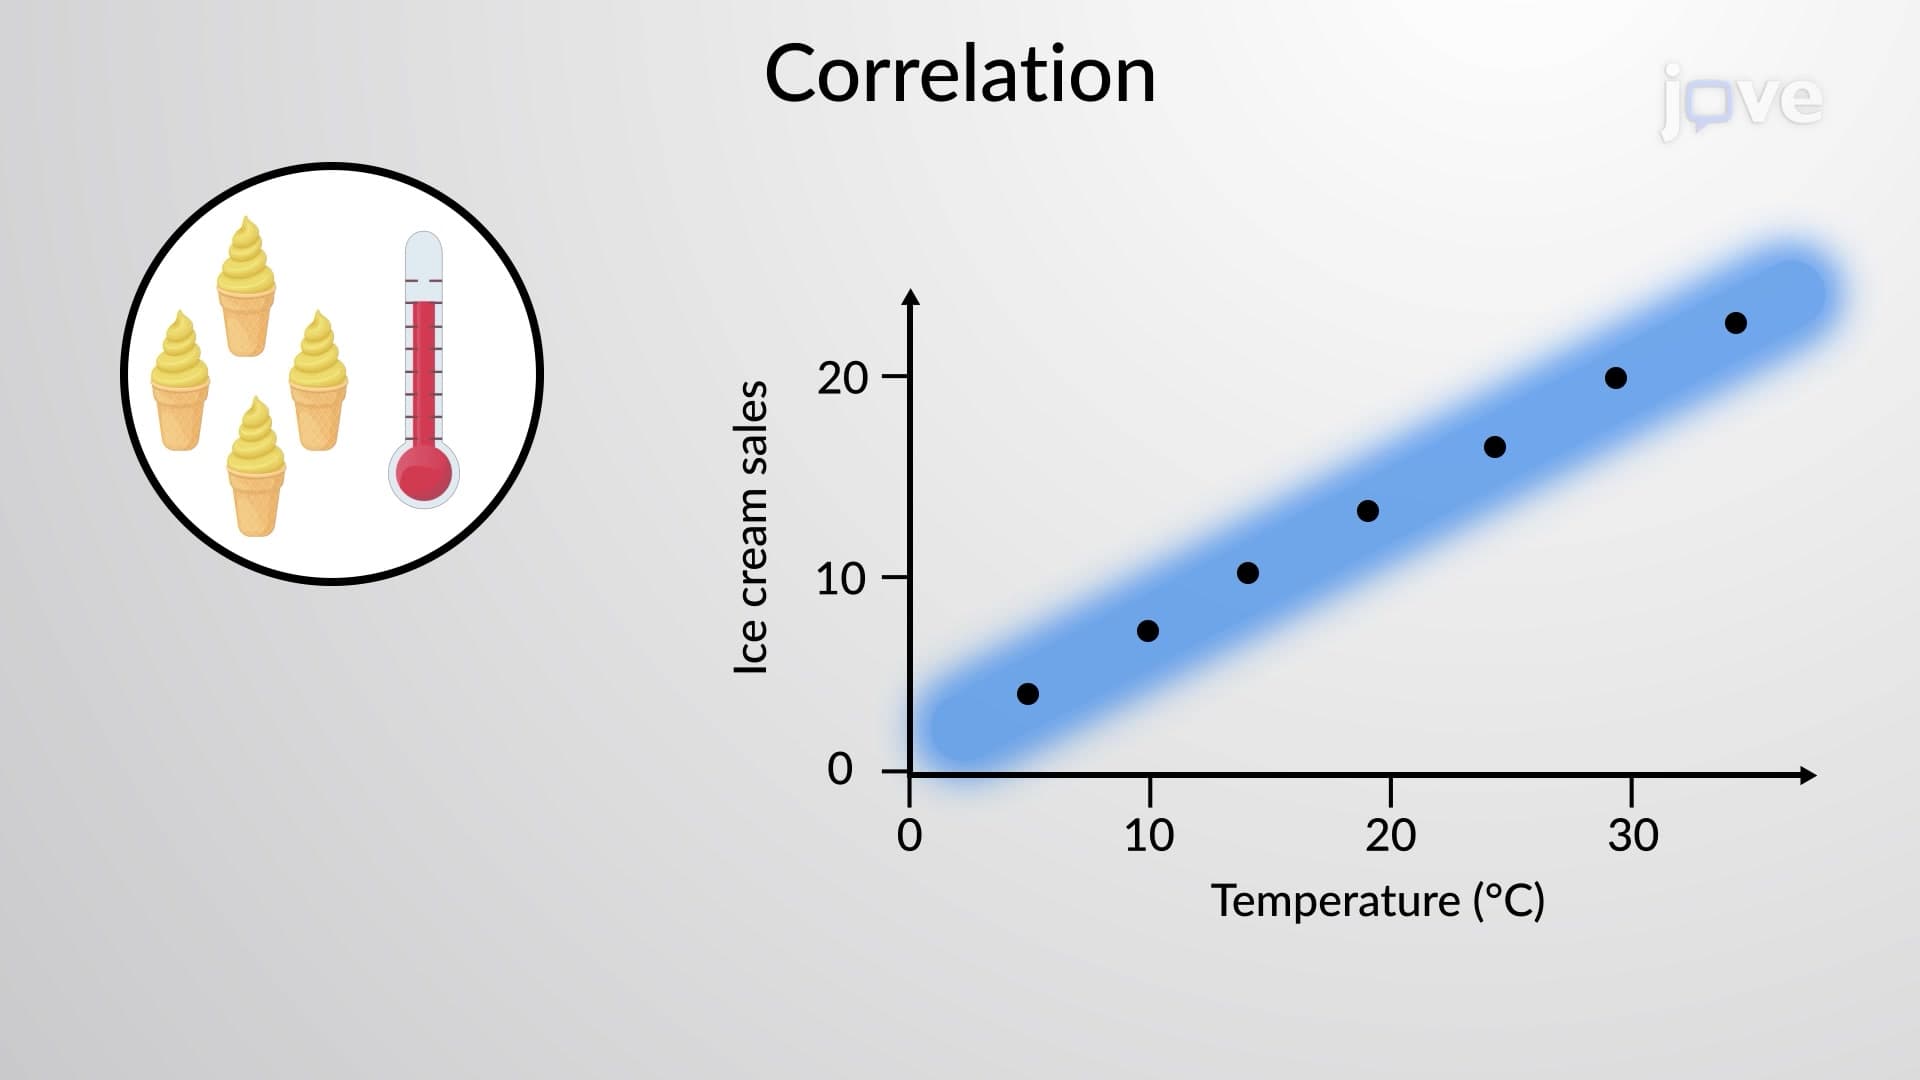
Correlation
Two variables, for example, a and b, are said to be positively correlated if both variables move in the same direction. In other words, a positive correlation exists between two variables, a and b, if:
 01:12
Relative Risk
 01:27
Margin of Error
 00:59
Propagation of Uncertainty from Random Error
 01:32
Probability Distributions
A discrete probability distribution is a probability distribution of discrete random variables. It can be categorized into binomial probability distribution and Poisson...