Related Experiment Video
Updated: Jul 25, 2025
An R-Based Landscape Validation of a Competing Risk Model
Published on: September 16, 2022
Structural credit risk model driven by Lévy process under knight uncertainty
Zhenyu Tang1, Bin Zhong1, Liang Zhou2
1Gannan University of science and technology, Jiangxi University of science and technology, Ganzhou, 341000 JiangXi China.

Abstract:
As per the projections of conventional credit risk structured model, the risky asset values tend to adhere to the geometric Brownian motion. On the contrary, the risky asset values remain a non-continuous and dynamic ones and jump based on the conditions. Is not possible to measure the real Knight Uncertainty risks in financial markets with the help of a single probability measure. In this background, the current research work analyzes a structural credit risk model that belongs to Levy market under Knight Uncertainty. With the help of Lévy-Laplace exponent, the authors developed a dynamic pricing model in this study and acquired the price intervals for default probability, stock value and the bond value of enterprise. To be specific, the study intended to establish explicit solutions for three value processes, discussed earlier, with an assumption that the jump process follows a log-normal distribution. At the end, the study also conducted numerical analysis to understand the crucial role played by Knight Uncertainty upon the pricing of default probability and the stock value of the enterprise.
Related Concept Videos
 01:19
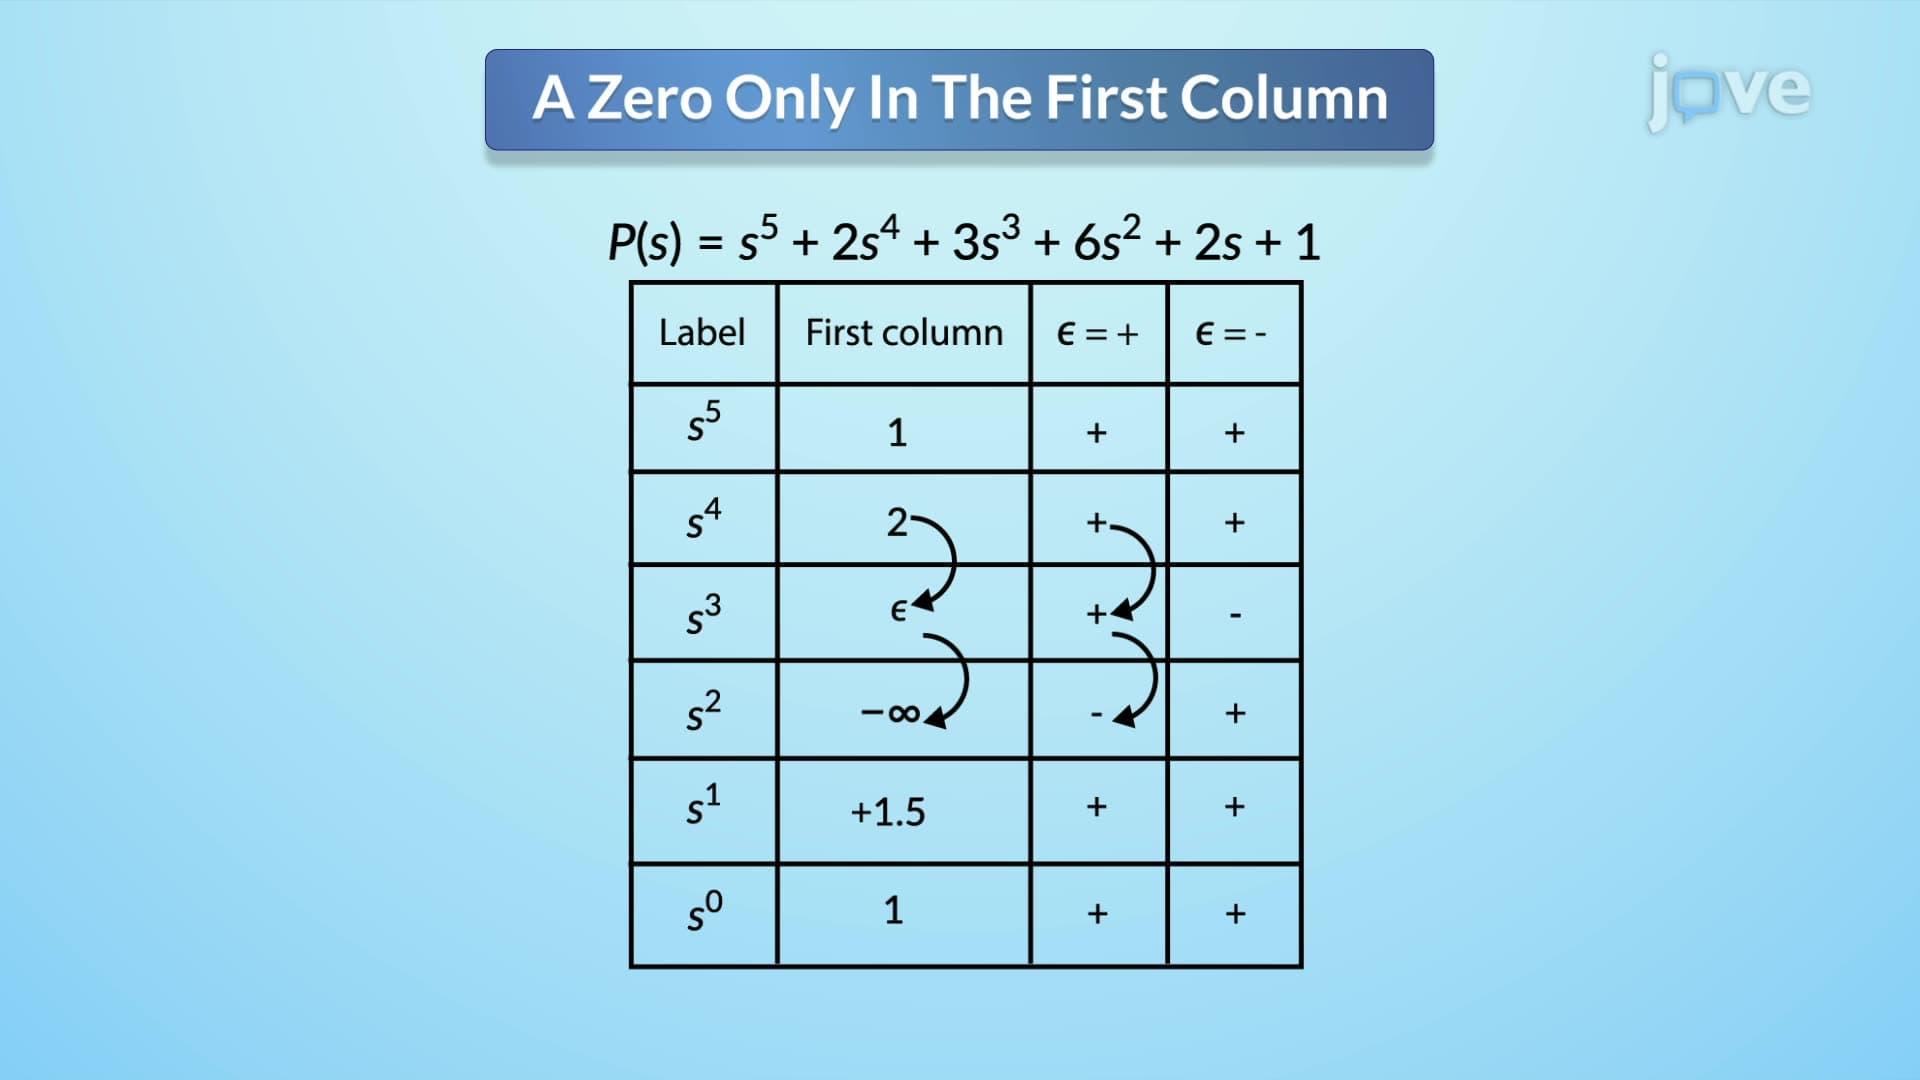
Routh-Hurwitz Criterion II
The first scenario occurs when a singular zero appears in the first column of the Routh table. This situation creates a division by zero issues. To resolve this, a small positive or negative number, denoted as epsilon (∈), is substituted for the zero. The stability analysis proceeds by assuming a sign for ∈. If ∈ is positive, any sign change in the first...
 01:15
Routh-Hurwitz Criterion I
To apply the Routh-Hurwitz criterion, a Routh table is constructed. The table's rows are labeled with powers of the complex frequency variable s, starting from the...
 01:20
Actuarial Approach
Consider the example of a high-risk surgical procedure with significant early-stage mortality. A two-year clinical study is conducted,...
 01:49
Probability Laws
 00:59
Bernoulli's Equation
 00:59
Propagation of Uncertainty from Random Error