Related Experiment Video
Updated: Jul 24, 2025

Application of Granger Causality Analysis of the Directed Functional Connection in Alzheimer's Disease and Mild Cognitive Impairment
Published on: August 7, 2017
Transfer Entropy Granger Causality between News Indices and Stock Markets in U.S. and Latin America during the
Semei Coronado1, Jose N Martinez2, Victor Gualajara3
1Palomar College, San Marcos, CA 92069, USA.

Abstract:
The relationship between three different groups of COVID-19 news series and stock market volatility for several Latin American countries and the U.S. are analyzed. To confirm the relationship between these series, a maximal overlap discrete wavelet transform (MODWT) was applied to determine the specific periods wherein each pair of series is significantly correlated. To determine if the news series cause Latin American stock markets' volatility, a one-sided Granger causality test based on transfer entropy (GC-TE) was applied. The results confirm that the U.S. and Latin American stock markets react differently to COVID-19 news. Some of the most statistically significant results were obtained from the reporting case index (RCI), A-COVID index, and uncertainty index, in that order, which are statistically significant for the majority of Latin American stock markets. Altogether, the results suggest these COVID-19 news indices could be used to forecast stock market volatility in the U.S. and Latin America.
Related Concept Videos
 01:21
Causality in Epidemiology
 01:27
Correlation and Causation
Correlation versus Causation
If the dependent variable increases or decreases when the independent variable increases, there is a positive or negative...
 00:52
Pareto Chart
The Pareto chart is named after the Italian economist Vilfredo Pareto, who described the Pareto...
 01:29
Econometric Views (EViews)
 01:09
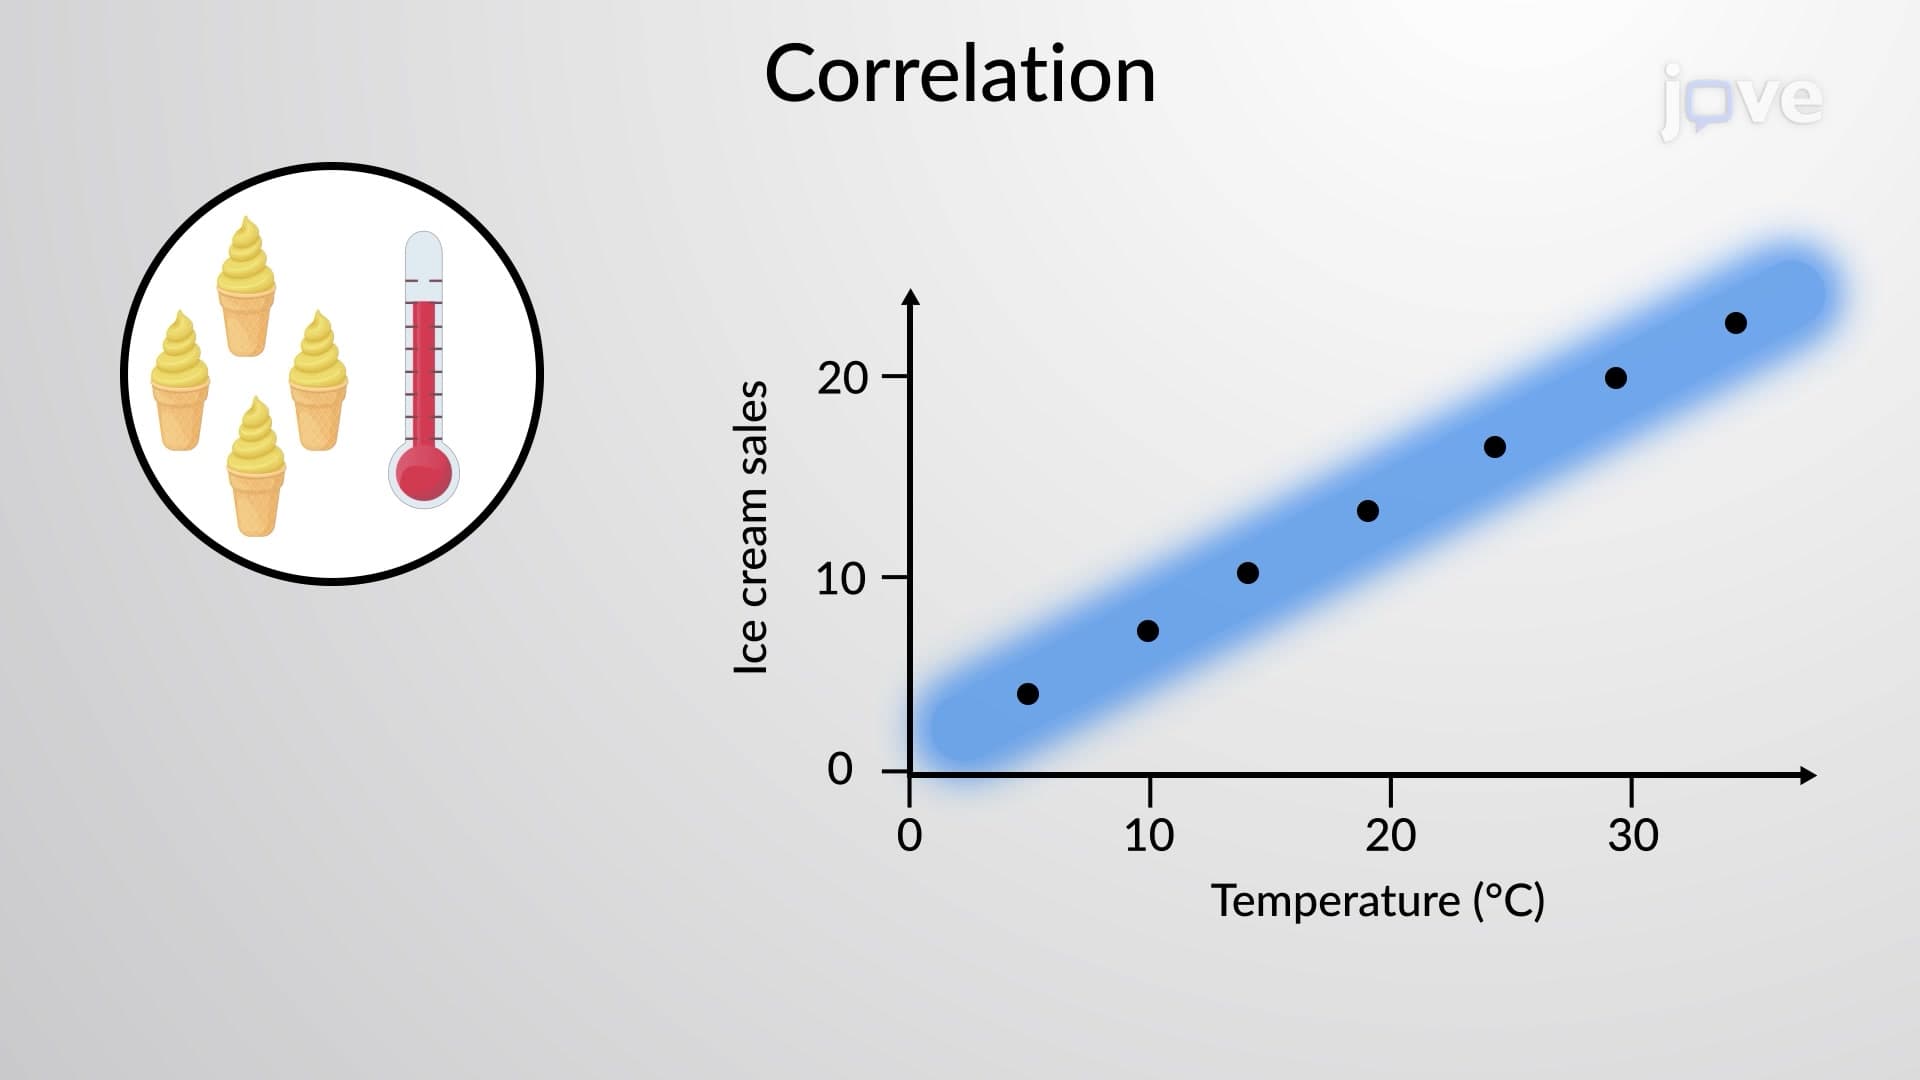
Correlation
Two variables, for example, a and b, are said to be positively correlated if both variables move in the same direction. In other words, a positive correlation exists between two variables, a and b, if:
 02:20
Correlations