Related Experiment Video
Updated: Jul 18, 2025

Analysis of SEC-SAXS data via EFA deconvolution and Scatter
Published on: January 28, 2021
Deciphering equity style returns: An analysis of size and value anomalies in the Pakistani stock exchange
Muhammad Kashif1, Sumaira Chamadia1, Farhan Ahmed2
1Faculty of Management Sciences, SZABIST University, Pakistan.

Abstract:
This study aims to identify the underlying causes of variation in the time series and cross-sectional equity style returns in the emerging stock market of Pakistan. We use asset pricing models and incorporate variables reflecting business cycle fluctuations to assess the time-varying size and value premiums. The methodology of this paper involves constructing style portfolios based on firm-specific characteristics such as market capitalization, price to earnings ratio, book-to-market equity ratio, momentum, and asset growth. We find that the style portfolios earn abnormal returns consistently which cannot be explained either through asset pricing models or business cycles variables. However, the size and value premiums are found to be subsided during the troughs of economic cycles. The results suggest that the abnormal returns for style portfolios are likely driven by firm-specific characteristics rather than macroeconomic factors. Overall, this study contributes to the literature on style investing by providing insights into the profitability of equity style portfolios in the Pakistani equity market. Our findings have implications for stock picking, investment management and risk factor analysis.
Related Concept Videos
 01:16
Unusual Results
According to the range rule of thumb, any value above or below two standard deviations, 2σ from the mean, μ is considered unusual.
Maximum unusual value =...
 01:04
5-Number Summary
In a box plot, the minimum and maximum data values represent the lower and upper whiskers in the graph, and the median is designated as the center of the box in the chart. The first quartile and third...
 01:02
Quantifying and Rejecting Outliers: The Grubbs Test
 00:57
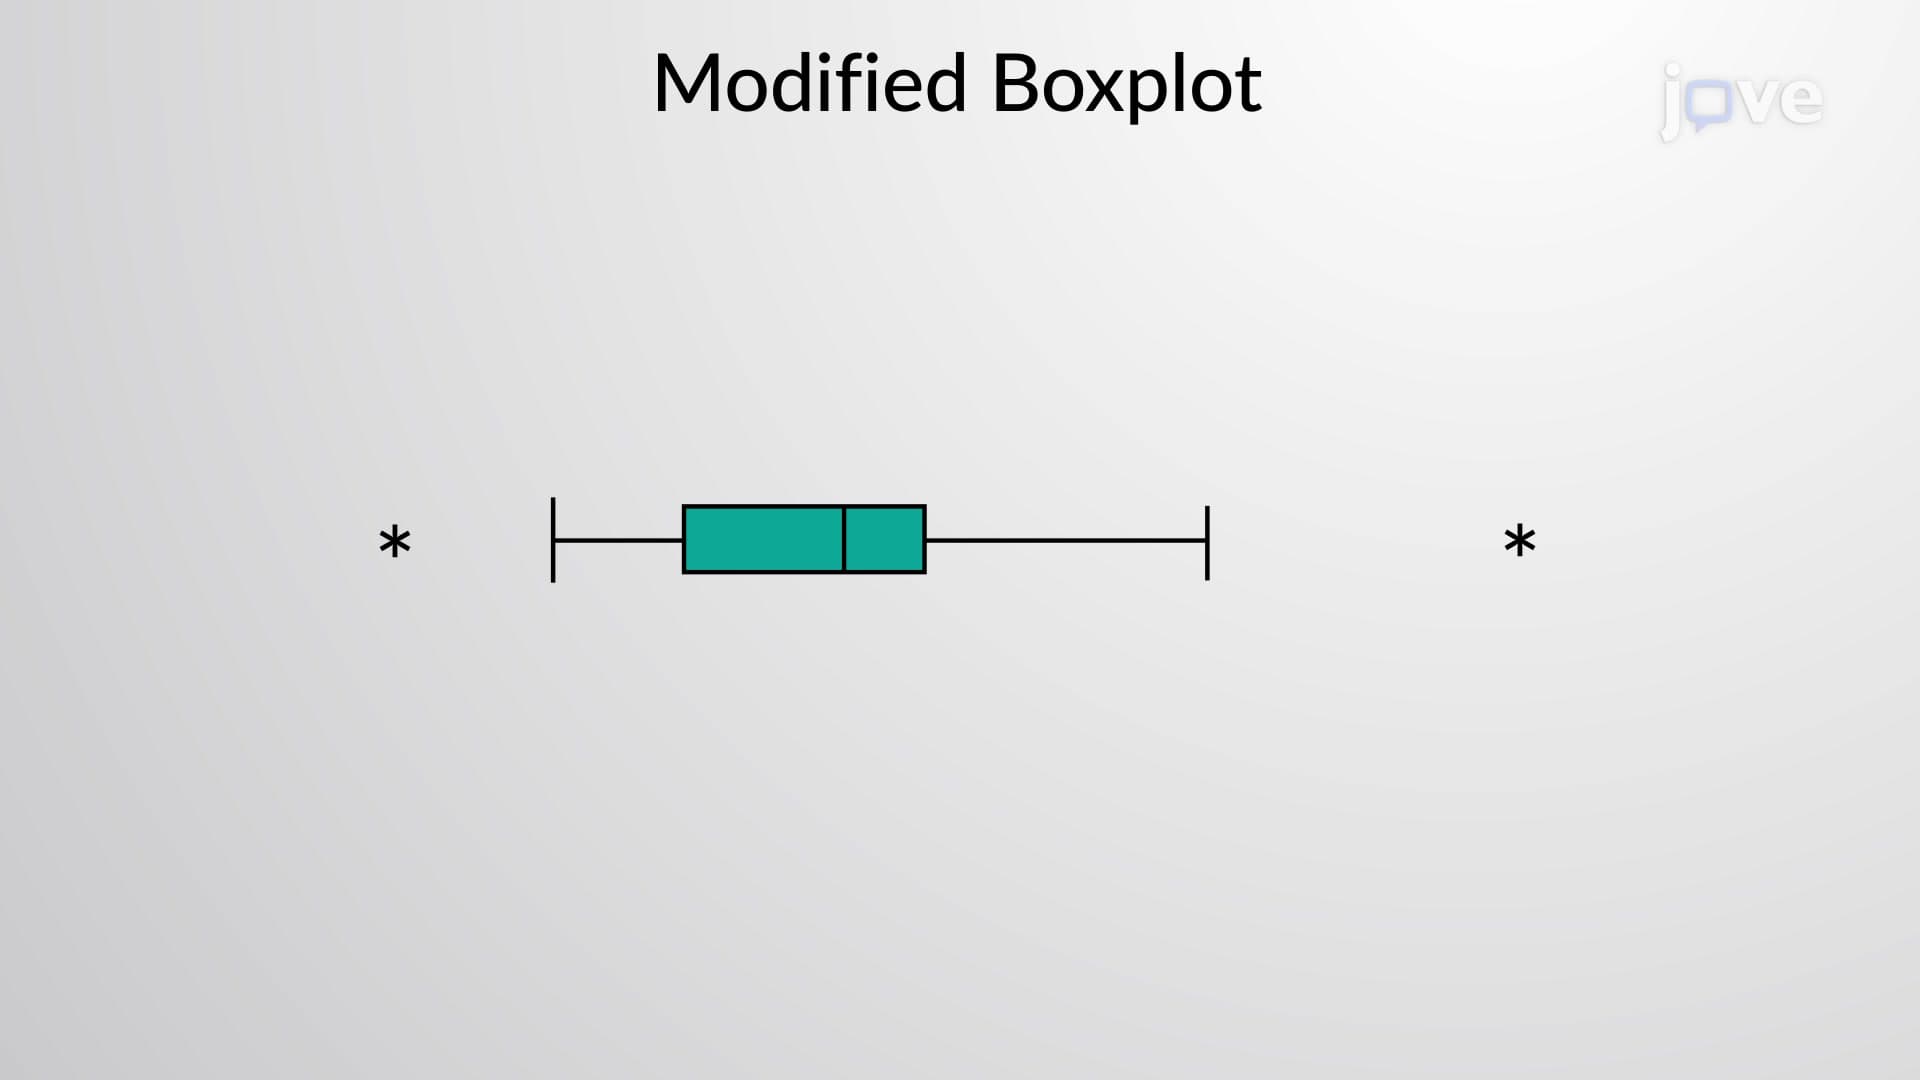
Modified Boxplots
However, the box plot does not tell the reader about outliers - values that lie far from the center of the data. We can modify the standard box and whisker plot to identify the outliers and visualize the actual spread of the data in a sample.
Initially, we calculate the adjusted...
 01:00
Detection of Gross Error: The Q Test
 01:12
Boxplot