Related Experiment Video
Updated: Jul 10, 2025
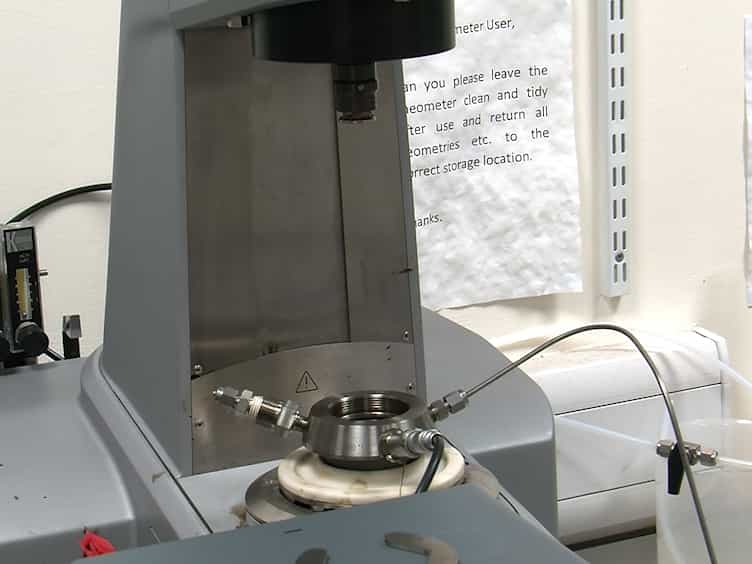

Measurement of the Rheology of Crude Oil in Equilibrium with CO2 at Reservoir Conditions
Published on: June 6, 2017
On the relationship between oil market and European stock returns
Cosimo Magazzino1, Muhammad Shahbaz2,3, Massimiliano Adamo4
1Department of Political Science, Roma Tre University, Rome, Italy. cosimo.magazzino@uniroma3.it.

Abstract:
This paper investigates the dynamic relationship between the oil market and European stock market returns using monthly data from May 2007 to April 2022 for 27 European Union member countries. A novel approach is adopted by using the time-varying Granger causality test and the structural vector auto-regression model to examine the causal links. Empirical results reveal strong evidence of time-varying causation between the variables, considering the oil market from both the supply-side and demand-side perspectives. In light of these findings, numerous policy considerations emerge, including refining risk management strategies for investors, reformulating economic and energy policies, the potential impact on monetary policy decisions, the need for ad hoc market regulations, facilitating investor education initiatives, promoting international cooperation, and advancing the transition to sustainable energy sources.
More Related Videos
Related Concept Videos
 01:07
Residual Plots
When the residual values are plotted against the variable x, it is called a residual...
 01:18
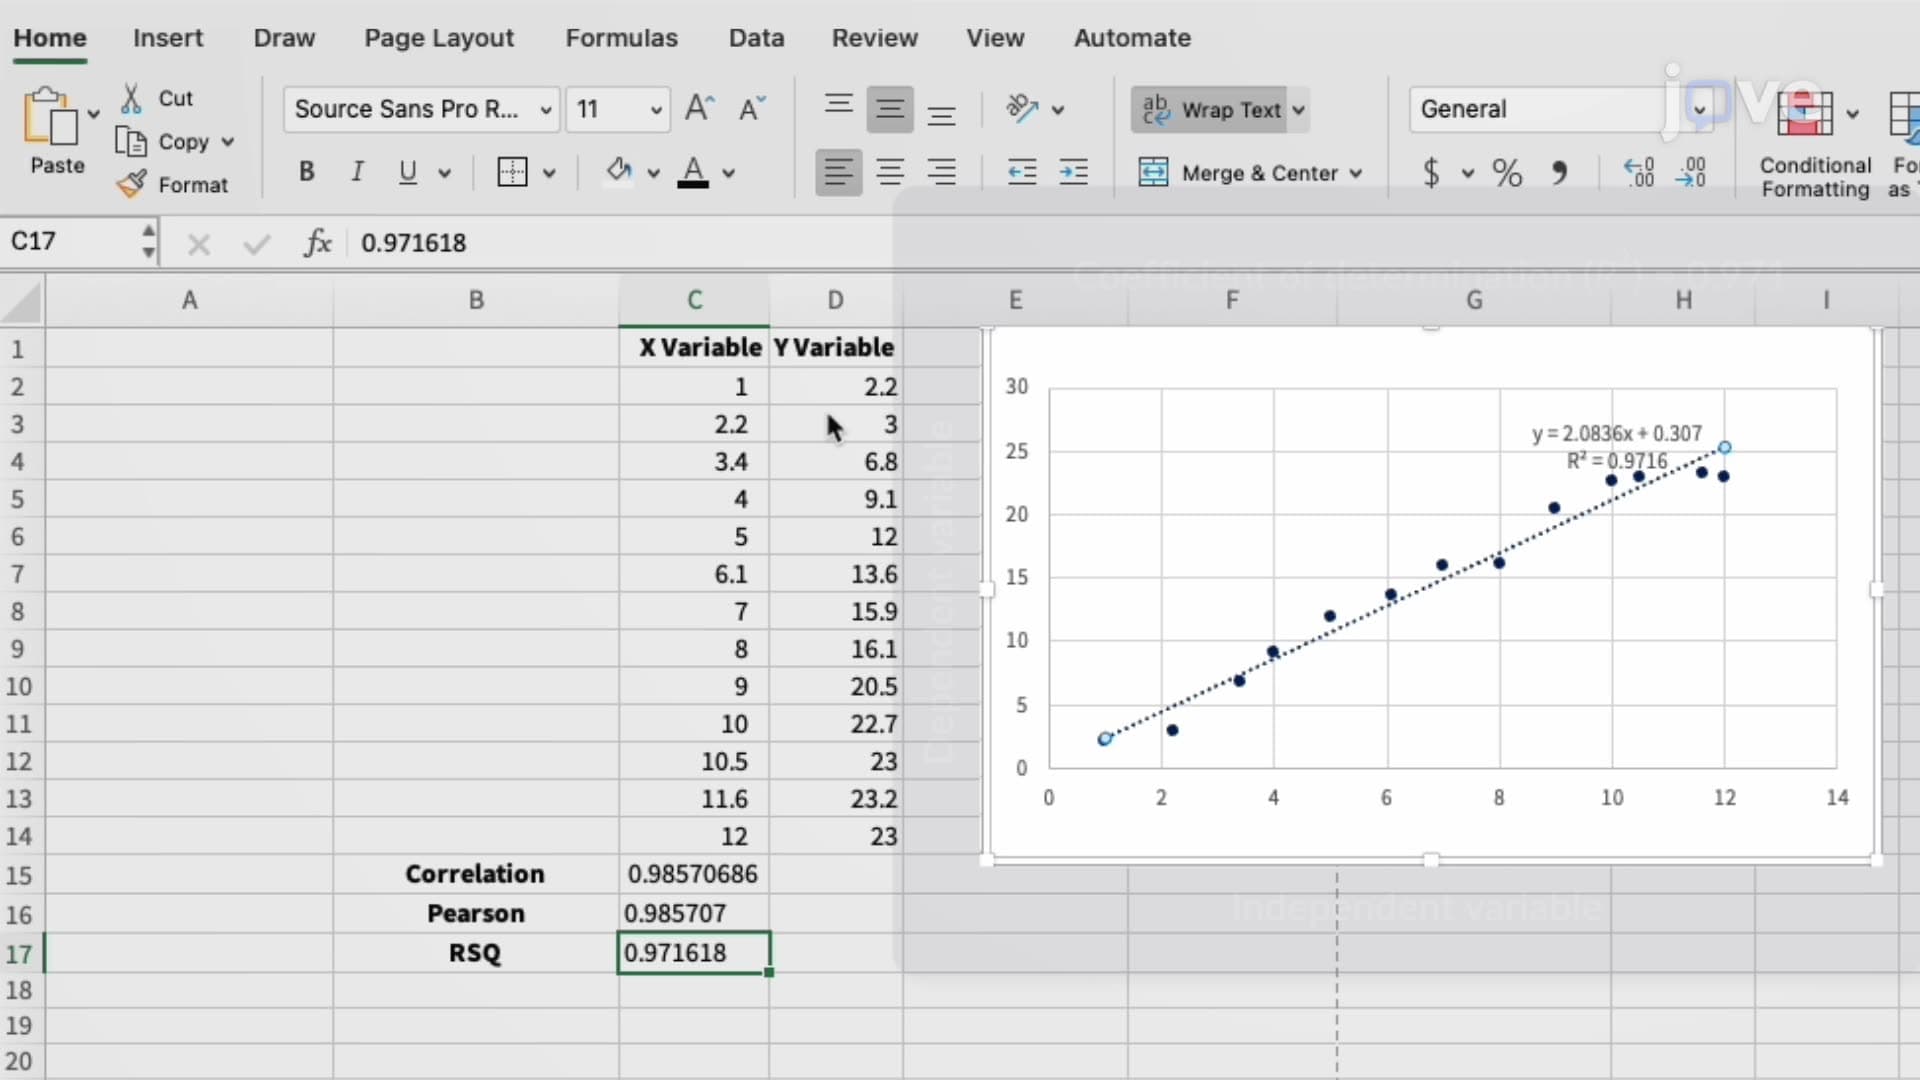
Microsoft Excel: Pearson's Correlation
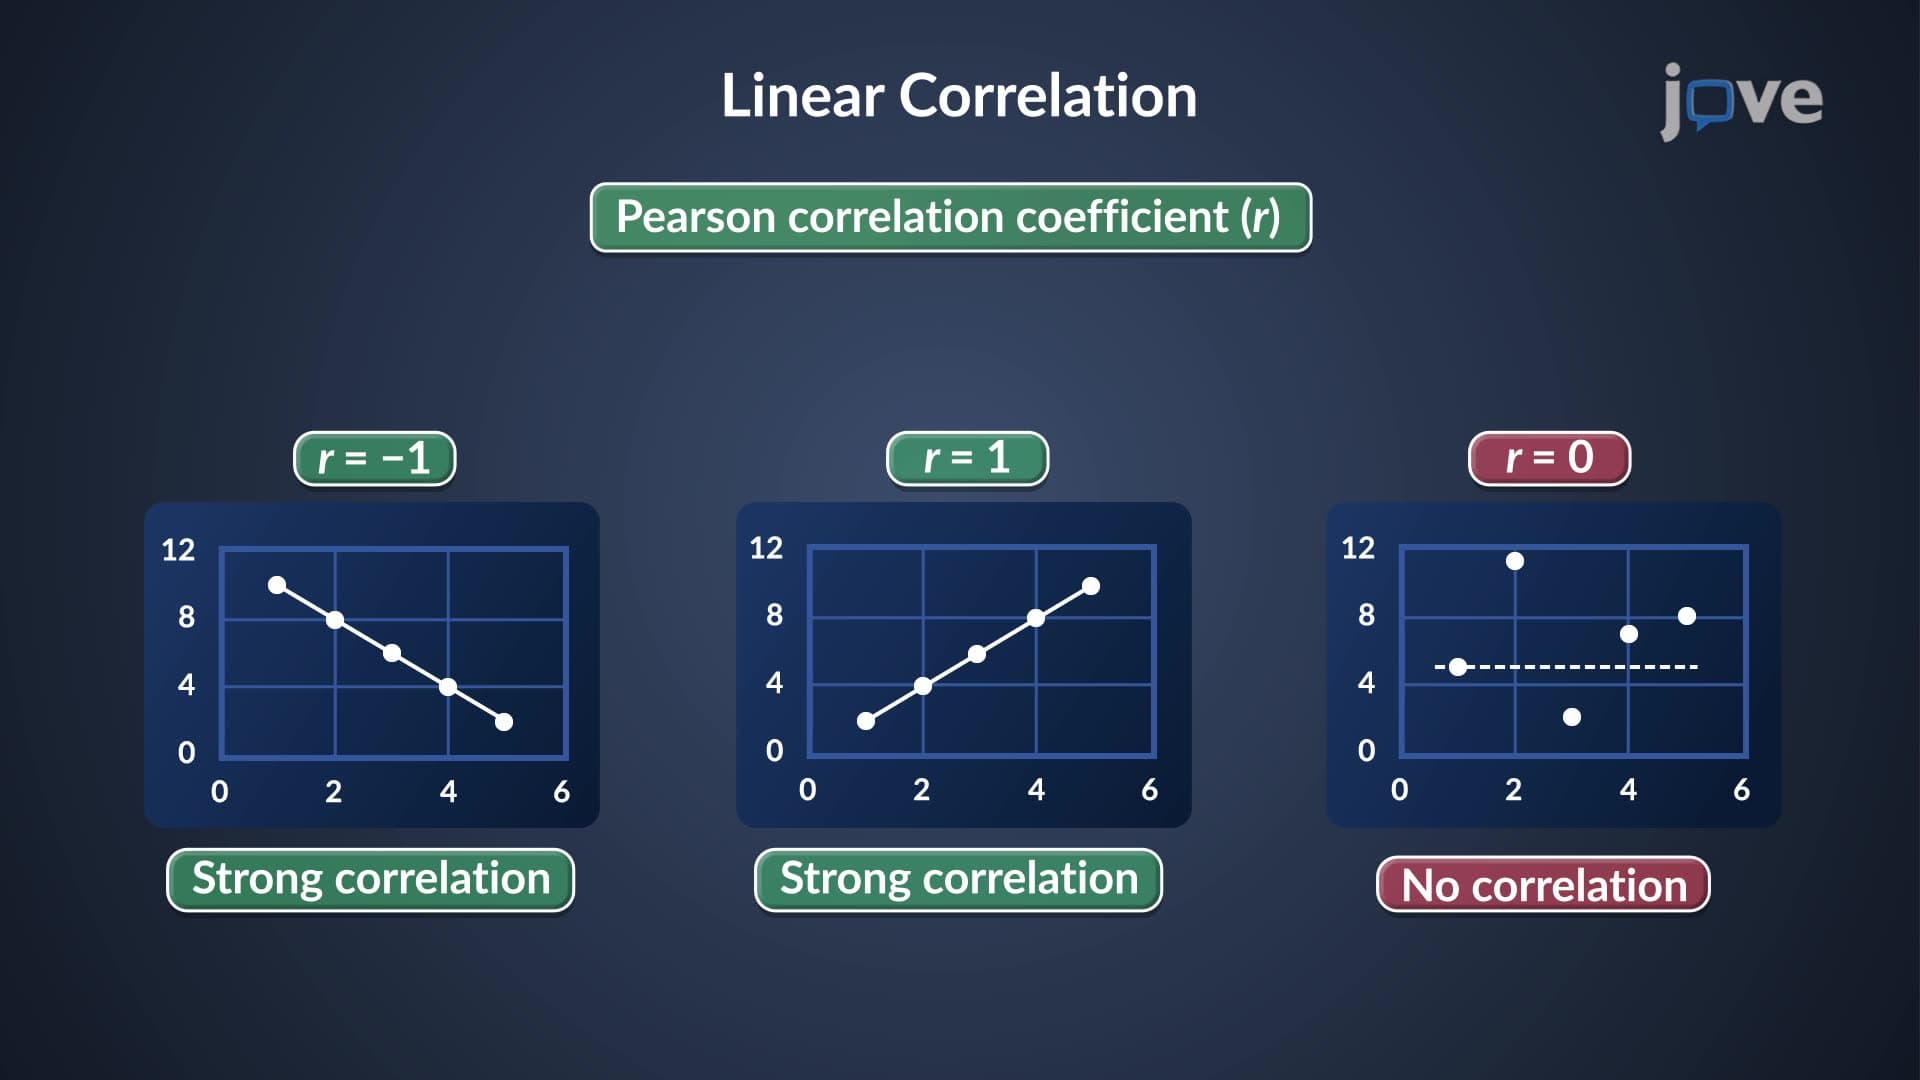 00:53
Correlation and Regression
 01:12
Coefficient of Correlation
If you suspect a linear relationship between x and y, then r can measure how strong the linear relationship is.
What the VALUE of r tells us:
The value of r is always between –1 and +1: –1 ≤ r ≤ 1.
The size of the correlation r indicates the...
 02:20
Correlations
 01:59
Relative Stabilities of Alkenes