Related Experiment Video
Updated: Jul 9, 2025
Comparing Bibliometric Analysis Using PubMed, Scopus, and Web of Science Databases
Published on: October 24, 2019
Do implied volatilities of stock and commodity markets affect conventional & shariah indices differently? An evidence
Safika Praveen Sheikh1, Syed Ahsan Jamil2, Ahmet Faruk Aysan3
1Alliance University, Bangalore, India.

Abstract:
The current study aims to investigate how index returns of conventional and shariah indices of the USA, Europe, and Asia are affected by changes in oil prices, gold prices, VIX, gold-VIX, and oil-VIX. In our investigation, we used the S&P 500, S&P Europe 350, S&P Pan Asia, and their relevant shariah counterparts for the USA, Europe, and Asia. To examine how the explanatory factors affect the overall distribution of the explained variables, we used OLS and quantile regression. For the time frame prior to Covid-19, we discover that all volatility indices-OVX, GVZ, and VIX-influence returns of all indices simultaneously, and that all variables-aside from the spot price of oil-have a greater impact during the bear phase according to QR findings. Further, Volatility indices have a greater impact on volatility of index returns during the Covid-19 period. This is largely because the Covid-19 outbreak had a rapid impact on economies all around the world, and the only thing that affected financial markets consistently was high volatility. This is further supported by the findings of BEKK, which demonstrate that volatility extends across all markets and originates from commodities like gold, oil, gold-VIX, and VIX. Evidence for this can be seen in the fact that during the COVID-19 period, stock prices reacted more favorably to oil price volatility than to oil spot prices, which even went negative on April 20, 2020. Because of this, market stability can be promoted by reducing volatility through the prompt dissemination of crucial information, even while governments have little direct control over the prices of significant commodities like gold and crude oil.
Related Concept Videos
 01:10
Coefficient of Variation
The coefficient of variation is a practical statistical tool in finance. It allows investors to assess the volatility or...
 01:09
Empirical Method to Interpret Standard Deviation
This rule is used widely in statistics to calculate the proportion of data values...
 01:19
Testing a Claim about Standard Deviation
The hypothesis testing for the claim of population standard deviation (or variance) requires the data and samples to be random and unbiased. The population distribution also must be normal. There is no specific requirement on the sample size as the estimation is based on the chi-square distribution.
As a first step, the hypothesis (null and alternative) concerning the claim about...
 02:14
Combustion Energy: A Measure of Stability in Alkanes and Cycloalkanes
Alkanes undergo combustion in the presence of excess oxygen and high-temperature conditions to give carbon dioxide and water. A combustion reaction is the energy source in natural gas, liquified...
 01:59
Relative Stabilities of Alkenes
 01:14
Standard Deviation of Calculated Results
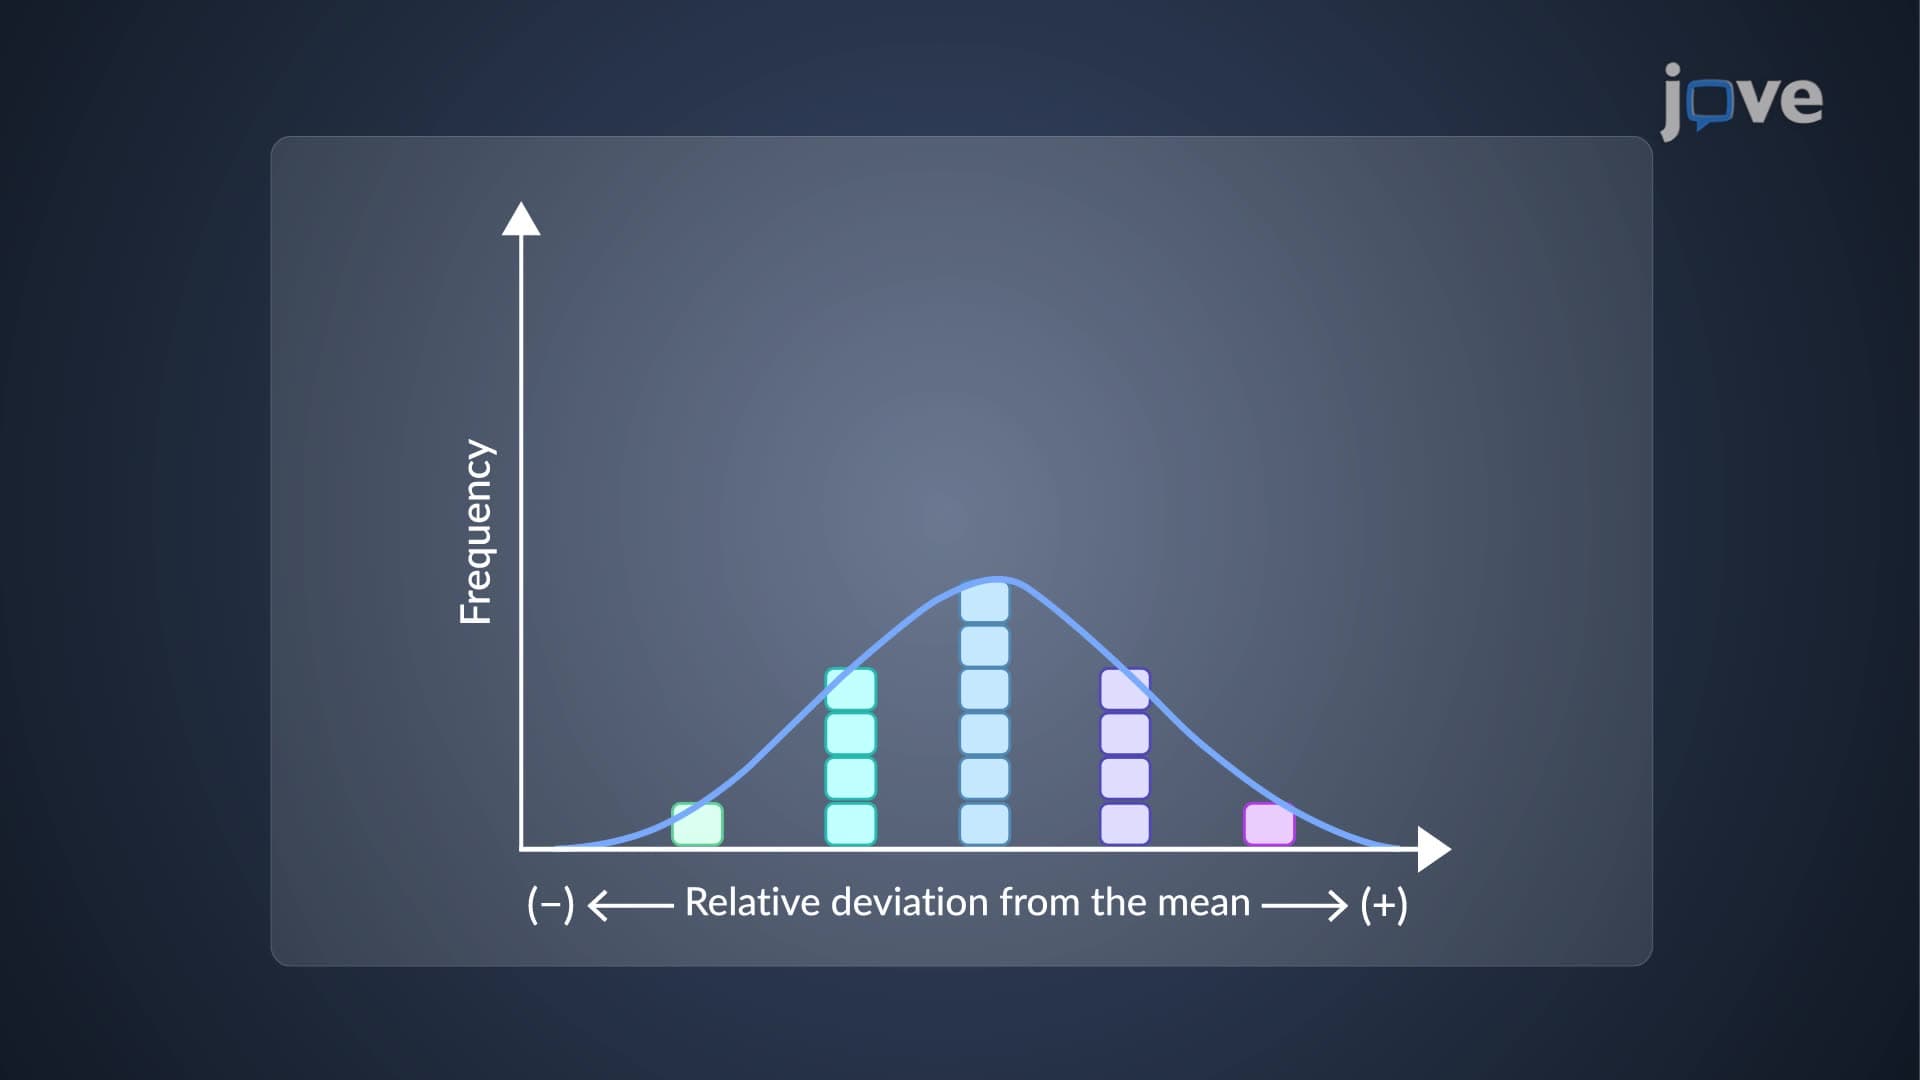
A broad Gaussian distribution curve has a wider standard deviation, representing a data set with...