Related Experiment Video
Updated: Jul 1, 2025

Analysis of SEC-SAXS data via EFA deconvolution and Scatter
Published on: January 28, 2021
A new denoising approach based on mode decomposition applied to the stock market time series: 2LE-CEEMDAN
Zinnet Duygu Akşehir1, Erdal Kılıç1
1Department of Computer Engineering, Ondokuz Mayıs University Samsun, Samsun, Turkey.

Abstract:
Time series, including noise, non-linearity, and non-stationary properties, are frequently used in prediction problems. Due to these inherent characteristics of time series data, forecasting based on this data type is a highly challenging problem. In many studies within the literature, high-frequency components are commonly excluded from time series data. However, these high-frequency components can contain valuable information, and their removal may adversely impact the prediction performance of models. In this study, a novel method called Two-Level Entropy Ratio-Based Complete Ensemble Empirical Mode Decomposition with Adaptive Noise (2LE-CEEMDAN) is proposed for the first time to effectively denoise time series data. Financial time series with high noise levels are utilized to validate the effectiveness of the proposed method. The 2LE-CEEMDAN-LSTM-SVR model is introduced to predict the next day's closing value of stock market indices within the scope of financial time series. This model comprises two main components: denoising and forecasting. In the denoising section, the proposed 2LE-CEEMDAN method eliminates noise in financial time series, resulting in denoised intrinsic mode functions (IMFs). In the forecasting part, the next-day value of the indices is estimated by training on the denoised IMFs obtained. Two different artificial intelligence methods, Long Short-Term Memory (LSTM) and Support Vector Regression (SVR), are utilized during the training process. The IMF, characterized by more linear characteristics than the denoised IMFs, is trained using the SVR, while the others are trained using the LSTM method. The final prediction result of the 2LE-CEEMDAN-LSTM-SVR model is obtained by integrating the prediction results of each IMF. Experimental results demonstrate that the proposed 2LE-CEEMDAN denoising method positively influences the model's prediction performance, and the 2LE-CEEMDAN-LSTM-SVR model outperforms other prediction models in the existing literature.

Related Concept Videos
 00:56
Noncompartmental Analysis: Statistical Moment Theory
 01:21
Linear Approximation in Time Domain
For a simple pendulum with a mass evenly distributed along its length and the center of mass located at half the pendulum's length,...
 01:29
Mechanistic Models: Compartment Models in Algorithms for Numerical Problem Solving
In individual population analyses, different algorithms are employed, such as Cauchy's method, which uses a...
 01:20
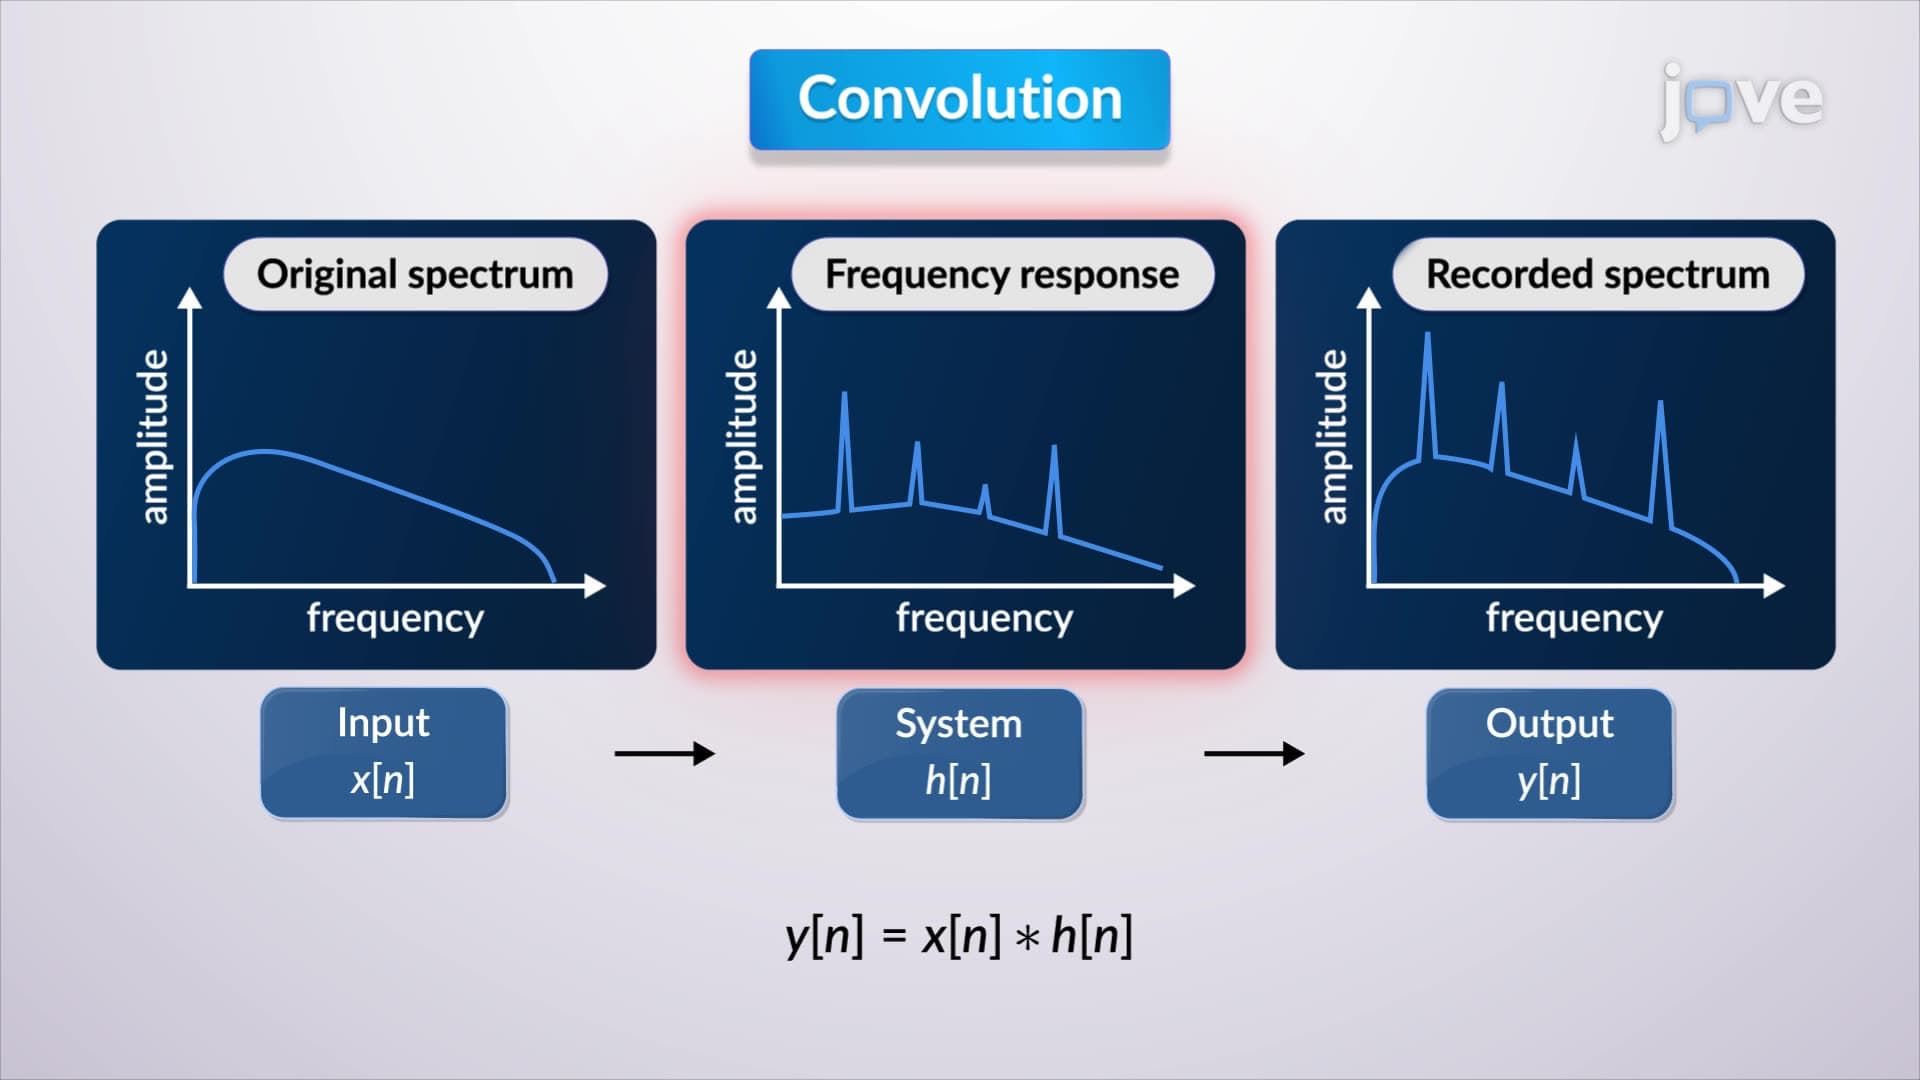
Deconvolution
Deconvolution involves several mathematical techniques to derive the impulse response. One common approach is polynomial division. In this method, the input and output sequences are treated as coefficients of...
 01:30
Classification of Signals
A continuous-time signal holds a value at every instant in time, representing information seamlessly. In contrast, a discrete-time signal holds values only at specific moments, often denoted as x(n), where...
 01:12
Quantitative Analysis
In quantitative analysis, two key measurements are made: the sample quantity and a property proportional to the amount of the analyte (the substance being analyzed). This forms the basis of the...