Related Experiment Video
Updated: Jul 1, 2025


Development of an Individual-Tree Basal Area Increment Model using a Linear Mixed-Effects Approach
Published on: July 3, 2020
Modeling opening price spread of Shanghai Composite Index based on ARIMA-GRU/LSTM hybrid model
Yuancheng Si1, Saralees Nadarajah2, Zongxin Zhang1
1School of Economics, Fudan University, ShangHai, PR China.

Abstract:
In the dynamic landscape of financial markets, accurate forecasting of stock indices remains a pivotal yet challenging task, essential for investors and policymakers alike. This study is motivated by the need to enhance the precision of predicting the Shanghai Composite Index's opening price spread, a critical measure reflecting market volatility and investor sentiment. Traditional time series models like ARIMA have shown limitations in capturing the complex, nonlinear patterns inherent in stock price movements, prompting the exploration of advanced methodologies. The aim of this research is to bridge the gap in forecasting accuracy by developing a hybrid model that integrates the strengths of ARIMA with deep learning techniques, specifically Long Short-Term Memory (LSTM) and Gated Recurrent Unit (GRU) networks. This novel approach leverages the ARIMA model's proficiency in linear trend analysis and the deep learning models' capability in modeling nonlinear dependencies, aiming to provide a comprehensive tool for market prediction. Utilizing a comprehensive dataset covering the period from December 20, 1990, to June 2, 2023, the study develops and assesses the efficacy of ARIMA, LSTM, GRU, ARIMA-LSTM, and ARIMA-GRU models in forecasting the Shanghai Composite Index's opening price spread. The evaluation of these models is based on key statistical metrics, including Mean Squared Error (MSE) and Mean Absolute Error (MAE), to gauge their predictive accuracy. The findings indicate that the hybrid models, ARIMA-LSTM and ARIMA-GRU, perform better in forecasting the opening price spread of the Shanghai Composite Index than their standalone counterparts. This outcome suggests that combining traditional statistical methods with advanced deep learning algorithms can enhance stock market prediction. The research contributes to the field by providing evidence of the potential benefits of integrating different modeling approaches for financial forecasting, offering insights that could inform investment strategies and financial decision-making.
More Related Videos

Related Concept Videos
 01:06
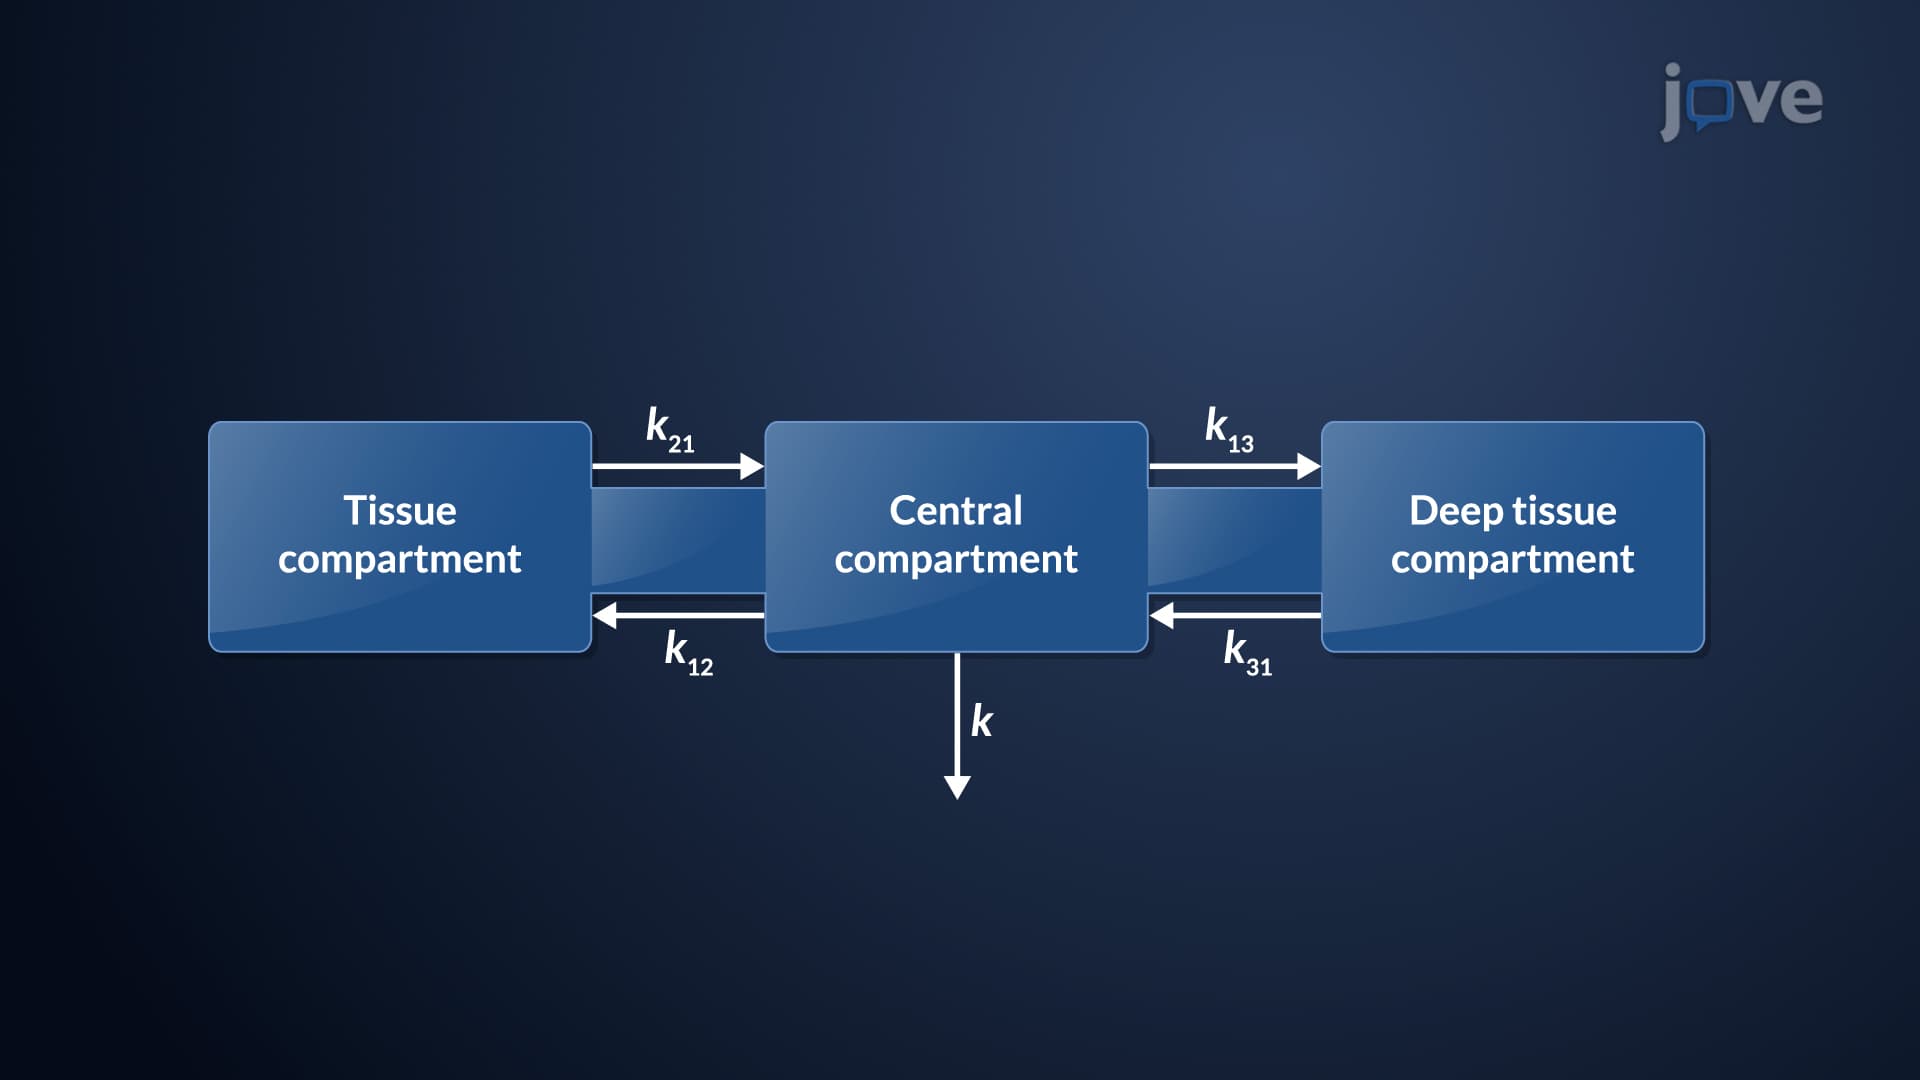
Three-Compartment Open Model
 01:24
One-Compartment Open Model: Wagner-Nelson and Loo Riegelman Method for ka Estimation
On...
 01:05
Two-Compartment Open Model: Overview
The...
 01:14
Multicompartment Models: Overview
These models offer a more comprehensive representation of drug behavior in the body than one-compartment models. They accommodate the complexity of drug distribution,...
 01:03
Prediction Intervals
However, the point estimate is most likely not the exact value of the population parameter, but close to it. After calculating point estimates, we construct interval estimates, called confidence intervals or prediction intervals. This prediction interval comprises a range of values unlike the point estimate and is a better predictor of the observed sample value, y.
 01:11
Regression Analysis
In regression analysis, a regression equation is determined based on the line of best fit– a line that best fits the data points plotted in a graph. This line is also called the regression line. The algebraic equation for the regression line is called the regression equation. It is represented as: