Related Experiment Video
Updated: Jun 28, 2025

A Method of Trigonometric Modelling of Seasonal Variation Demonstrated with Multiple Sclerosis Relapse Data
Published on: December 9, 2015
Impact of coronavirus pandemic on stock index: A polynomial regression with time delay
1Department of Applied Mathematics, Hong Kong Polytechnic University, 11 Yucai Road, Hung Hom, Hong Kong, Kowloon, China.

Motivation:
Under contemporary market conditions in China, the stock index has been volatile and highly reflect trends in the coronavirus pandemic, but rare scientific research has been conducted to model the possible nonlinear relations between the two indicators. Added, on the advent that covid-related news in one time period impacts the stock market in another period, time delay can be an equally good predictor of the stock index but rarely investigated.
Objectives:
To contribute to filling the gaps identified in existing research, this study models relationship between the stock market index and coronavirus pandemic by leveraging volatility in the stock market and covid data through time delay and best degree in a polynomial environment. The resultant optimal time delay and best degree model is used to derive a high-accuracy prediction of stock market index.
Novelty:
In line with the possible relations, the novelty of this study is that it proposes, validates and implements polynomial regression with time delay to model nonlinear relationship between the stock index and covid.
Methods:
This study utilizes high-frequency data from January 2020 to the first week of July 2022 to model the nonlinear relationship between the stock index, new covid cases and time delay under polynomial regression environment.
Findings:
The empirical results show that time delay and new covid cases, when modelled in a polynomial environment with optimal degree and delay, do present better representation of the nonlinear relationship such predictors have with stock index for China. Relative to results from the polynomial regression without delay, the empirical evidence from the model with delay show that an optimal time delay of 17 weeks makes it possible to predict the stock index at high accuracy and record improvements of 16-fold or higher. The representative delay model is used to project for up to 17 weeks for future trends in the stock index.
Implication:
The implication of the findings herein is that the prowess of the time delay polynomial regression is heavily dependent on instability in covid-related time trends and that researchers and decision-makers should consider modeling to cover for the unsteadiness in coronavirus cases to achieve better results.
Related Concept Videos
 01:11
Residuals and Least-Squares Property
If the observed data point lies above the line, the residual is positive, and the line underestimates the actual data value for y. If the observed data point lies below the line, the residual is negative, and the line overestimates the actual data value for y.
The process of fitting the best-fit...
 01:14
Parametric Survival Analysis: Weibull and Exponential Methods
Weibull Distribution
The Weibull distribution is a flexible model used in parametric survival analysis. It can handle both increasing and decreasing hazard rates, depending on its shape parameter...
 01:15
Drug Concentration Versus Time Correlation
Two pivotal parameters are the minimum effective concentration (MEC) and the minimum toxic concentration (MTC). The MEC is the...
 00:53
Correlation and Regression
 01:11
Regression Analysis
In regression analysis, a regression equation is determined based on the line of best fit– a line that best fits the data points plotted in a graph. This line is also called the regression line. The algebraic equation for the regression line is called the regression equation. It is represented as:
 01:18
Microsoft Excel: Regression Analysis
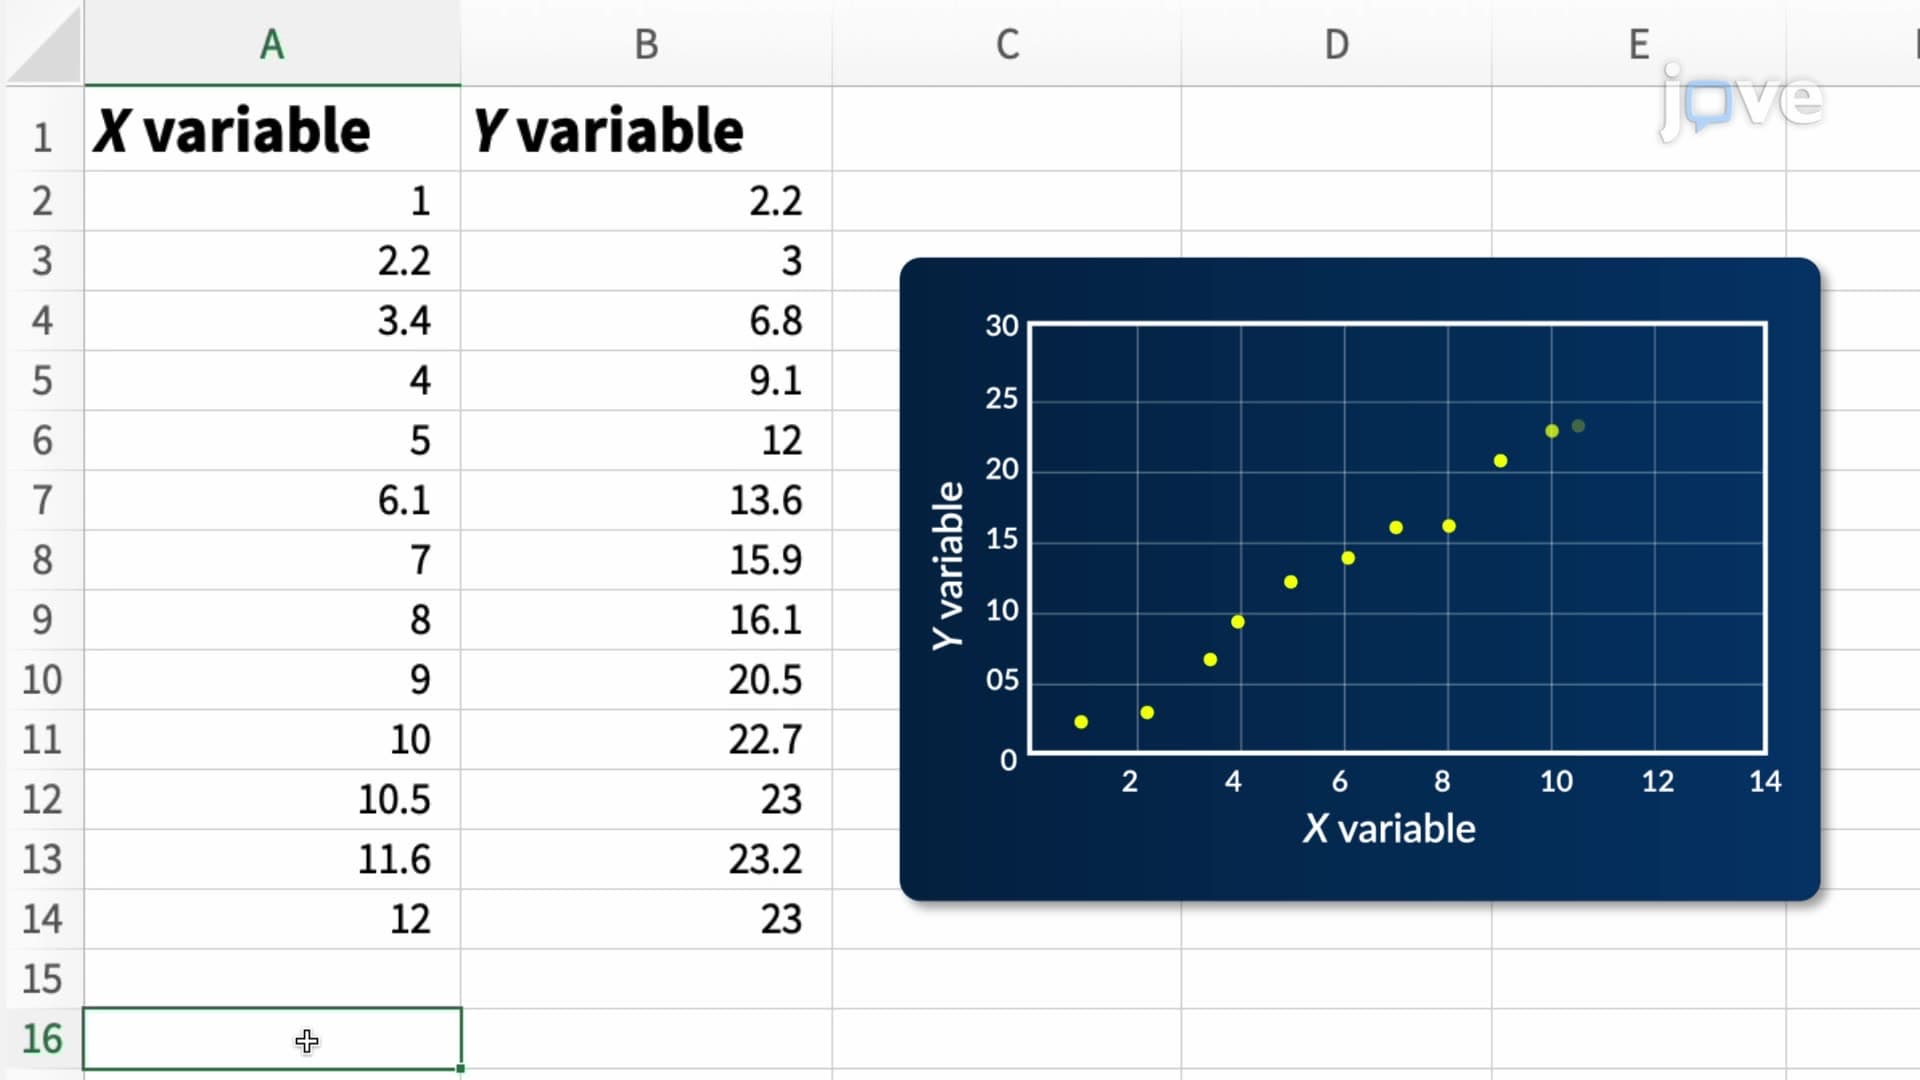
To perform regression...