Related Experiment Video
Updated: Jun 28, 2025

Measuring the Subjective Value of Risky and Ambiguous Options using Experimental Economics and Functional MRI Methods
Published on: September 19, 2012
Catastrophic risks and the pricing of catastrophe equity put options
Massimo Arnone1, Michele Leonardo Bianchi2, Anna Grazia Quaranta3
1Department of Economics, University of Messina, Messina, Italy.

Abstract:
In this paper, after a review of the most common financial strategies and products that insurance companies use to hedge catastrophic risks, we study an option pricing model based on processes with jumps where the catastrophic event is captured by a compound Poisson process with negative jumps. Given the importance that catastrophe equity put options (CatEPuts) have in this context, we introduce a pricing approach that provides not only a theoretical contribution whose applicability remains confined to purely numerical examples and experiments, but which can be implemented starting from real data and applied to the evaluation of real CatEPuts. We propose a calibration framework based on historical log-returns, market capitalization and option implied volatilities. The calibrated parameters are then considered to price CatEPuts written on the stock of the main Italian insurance company over the high volatile period from January to April 2020. We show that the ratio between plain-vanilla put options and CatEPuts strictly depends on the shape of the implied volatility smile and it varies over time.

Related Concept Videos
 01:11
Hazard Rate
 01:23
Types of Biopharmaceutical Studies: Controlled and Non-Controlled Approaches
Non-controlled studies, commonly employed for initial exploration, lack a control group, rendering them susceptible to biases and external influences. In contrast,...
 01:14
Parametric Survival Analysis: Weibull and Exponential Methods
Weibull Distribution
The Weibull distribution is a flexible model used in parametric survival analysis. It can handle both increasing and decreasing hazard rates, depending on its shape parameter...
 03:26
Framing Effects
 01:19
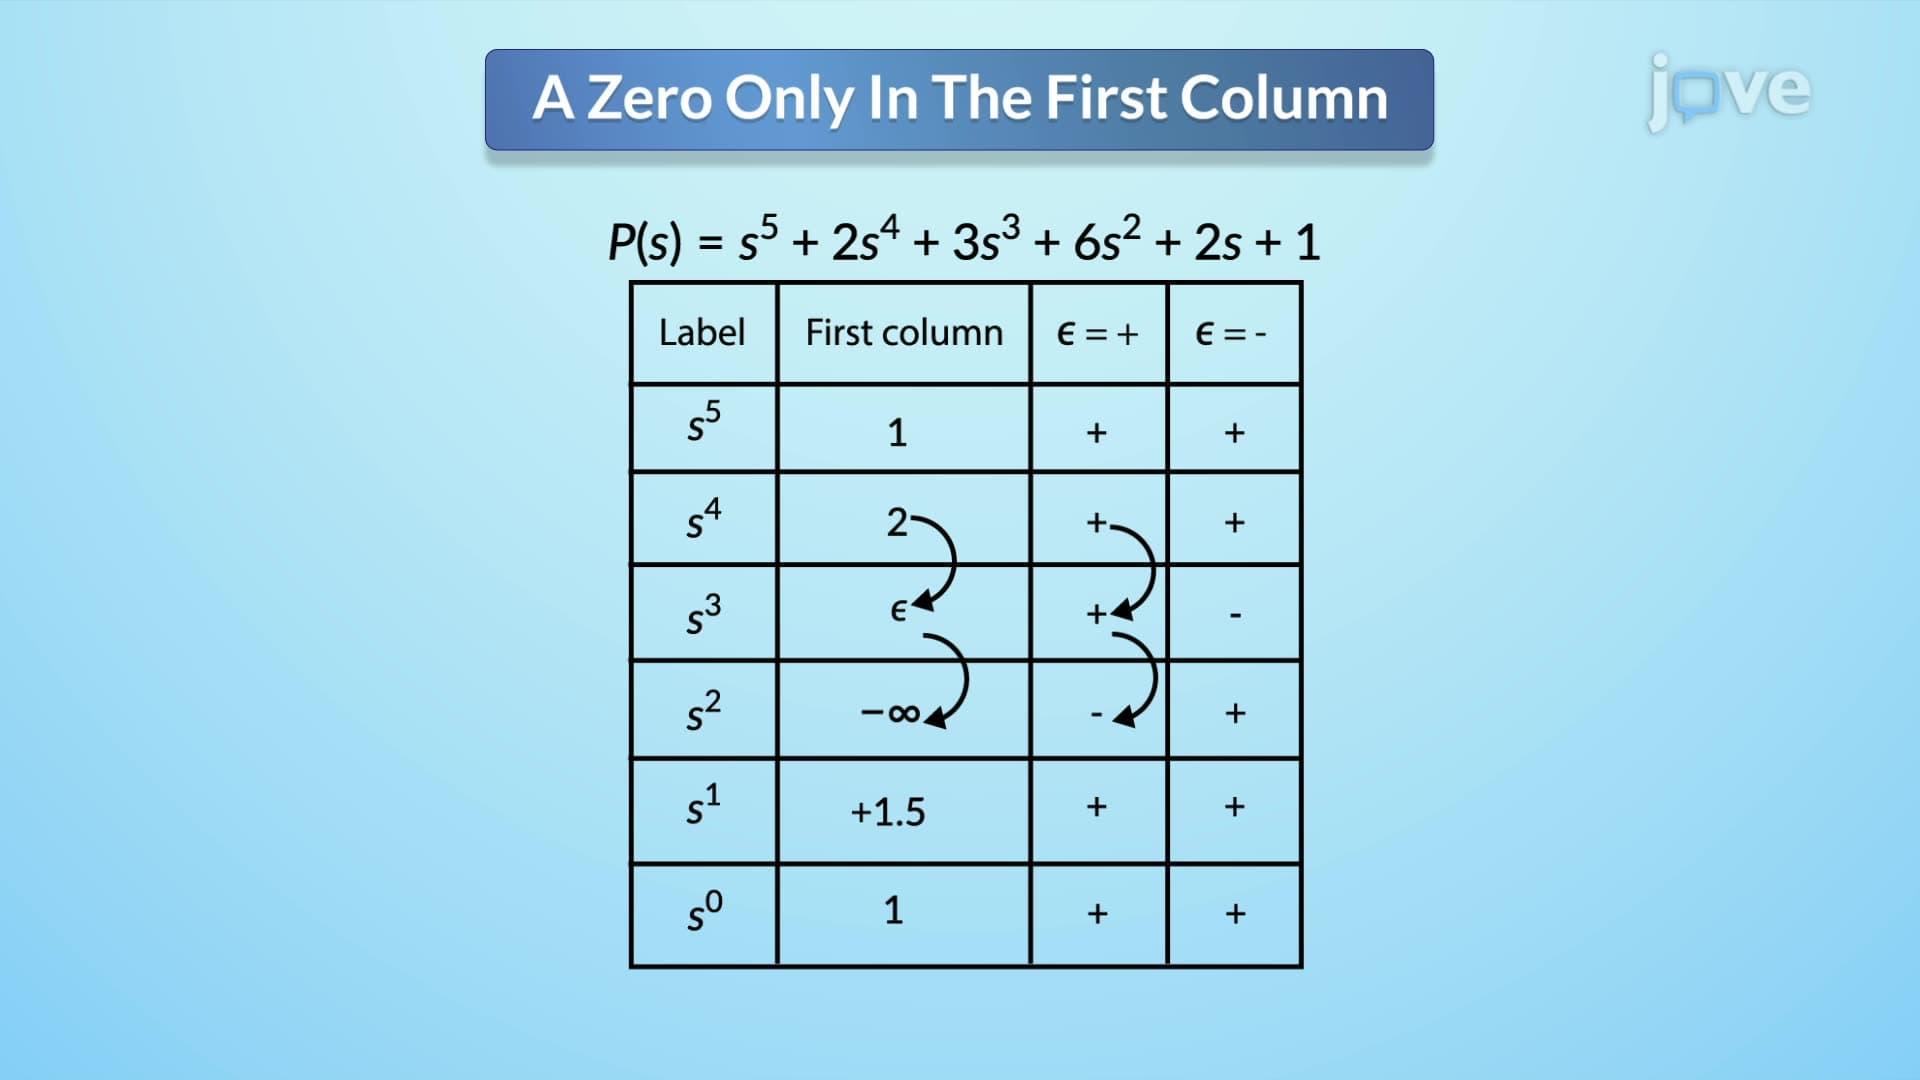
Routh-Hurwitz Criterion II
The first scenario occurs when a singular zero appears in the first column of the Routh table. This situation creates a division by zero issues. To resolve this, a small positive or negative number, denoted as epsilon (∈), is substituted for the zero. The stability analysis proceeds by assuming a sign for ∈. If ∈ is positive, any sign change in the first...
 01:09
Censoring Survival Data