Related Experiment Video
Updated: Jun 25, 2025
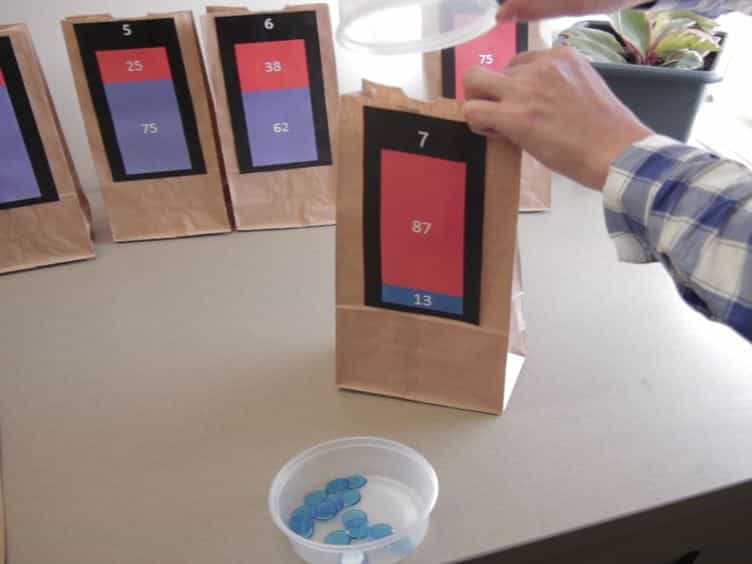

Measuring the Subjective Value of Risky and Ambiguous Options using Experimental Economics and Functional MRI Methods
Published on: September 19, 2012
High-frequency enhanced VaR: A robust univariate realized volatility model for diverse portfolios and market
1School of Sport Business, Guangzhou Sport University, Guangzhou, Guangdong, China.

Abstract:
In the field of financial risk management, the accuracy of portfolio Value-at-Risk (VaR) forecasts is of critical importance to both practitioners and academics. This study pioneers a comprehensive evaluation of a univariate model that leverages high-frequency intraday data to improve portfolio VaR forecasts, providing a novel contrast to both univariate and multivariate models based on daily data. Existing research has used such high-frequency-based univariate models for index portfolios, it has not adequately studied their robustness for portfolios with diverse risk profiles, particularly under changing market conditions, such as during crises. Our research fills this gap by proposing a refined univariate long-memory realized volatility model that incorporates realized variance and covariance metrics, eliminating the necessity for a parametric covariance matrix. This model captures the long-run dependencies inherent in the volatility process and provides a flexible alternative that can be paired with appropriate return innovation distributions for VaR estimation. Empirical analyses show that our methodology significantly outperforms traditional univariate and multivariate Generalized AutoRegressive Conditional Heteroskedasticity (GARCH) models in terms of forecasting accuracy while maintaining computational simplicity and ease of implementation. In particular, the inclusion of high-frequency data in univariate volatility models not only improves forecasting accuracy but also streamlines the complexity of portfolio risk assessment. This research extends the discourse between academic research and financial practice, highlighting the transformative impact of high-frequency data on risk management strategies within the financial sector.

Related Concept Videos
 00:56
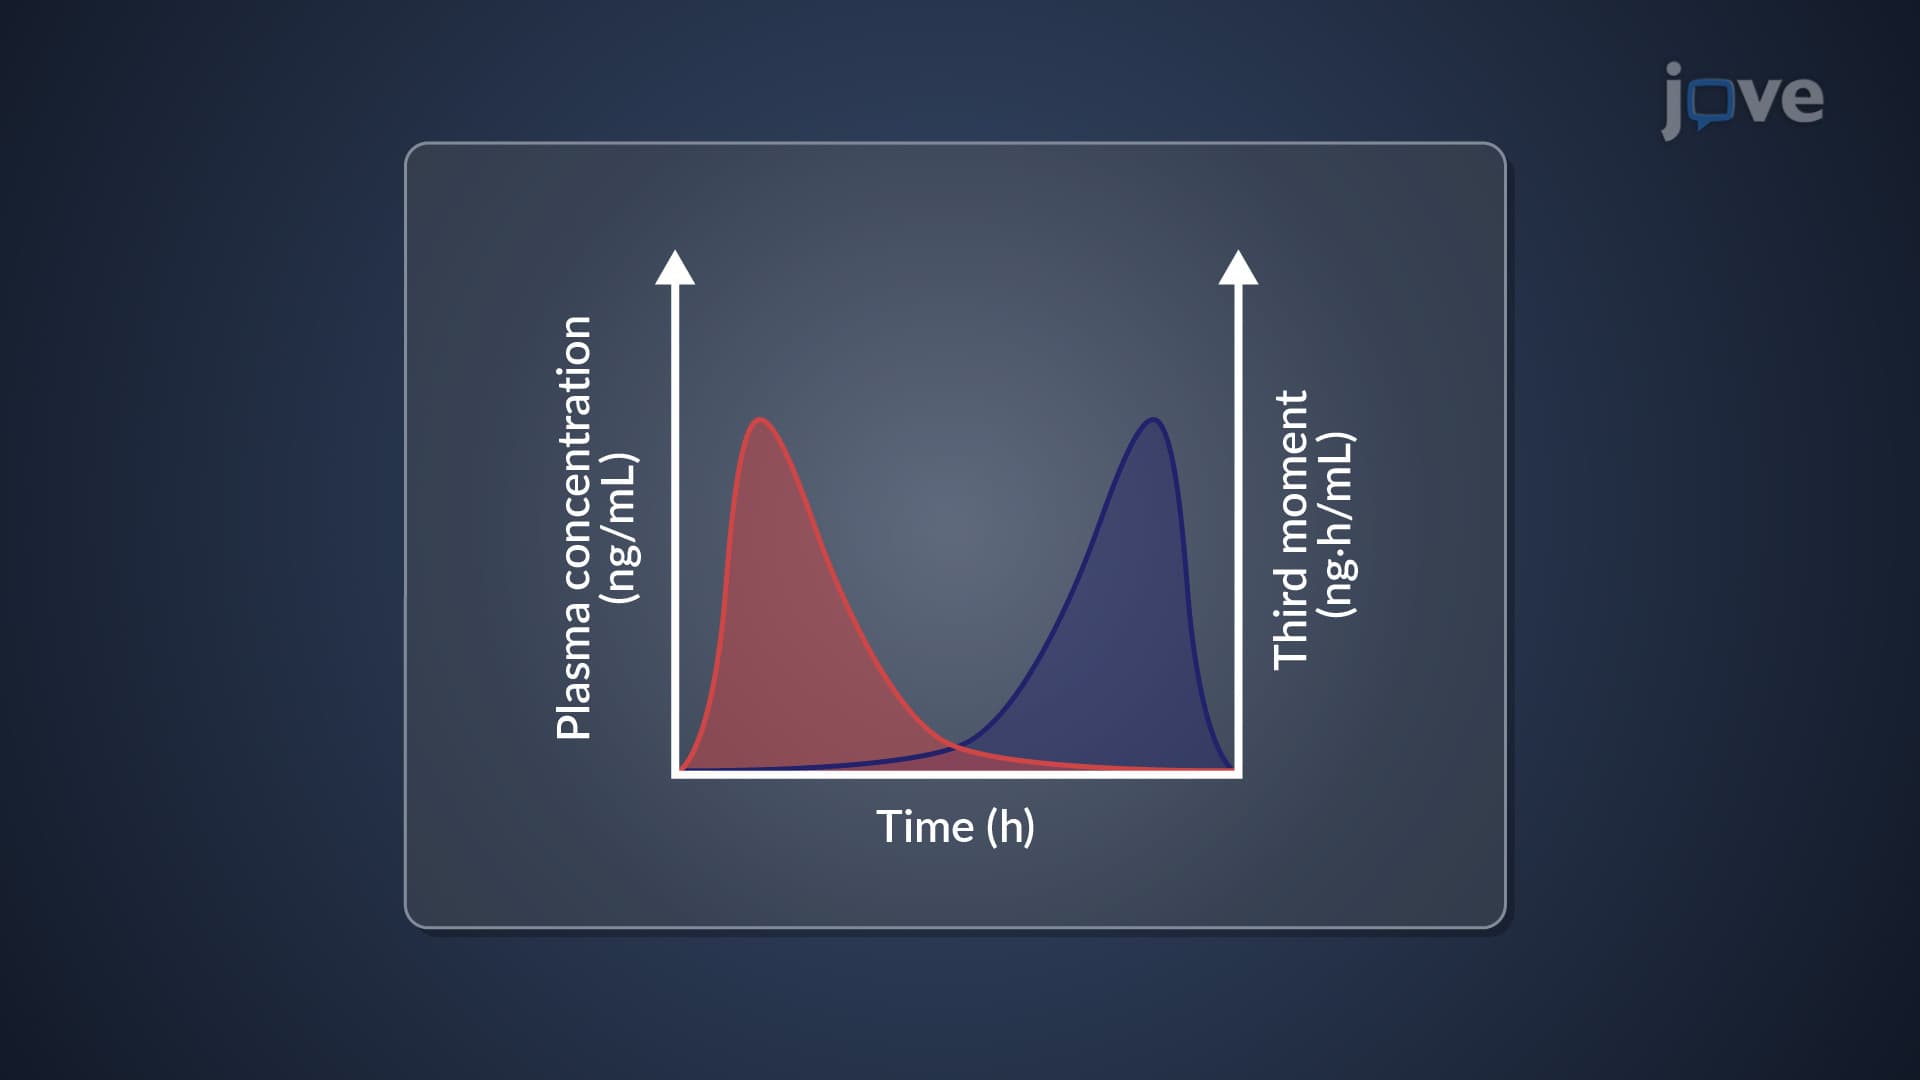
Noncompartmental Analysis: Statistical Moment Theory
 01:08
Determination of Expected Frequency
 01:19
Expected Frequencies in Goodness-of-Fit Tests
 01:09
Empirical Method to Interpret Standard Deviation
This rule is used widely in statistics to calculate the proportion of data values...
 01:07
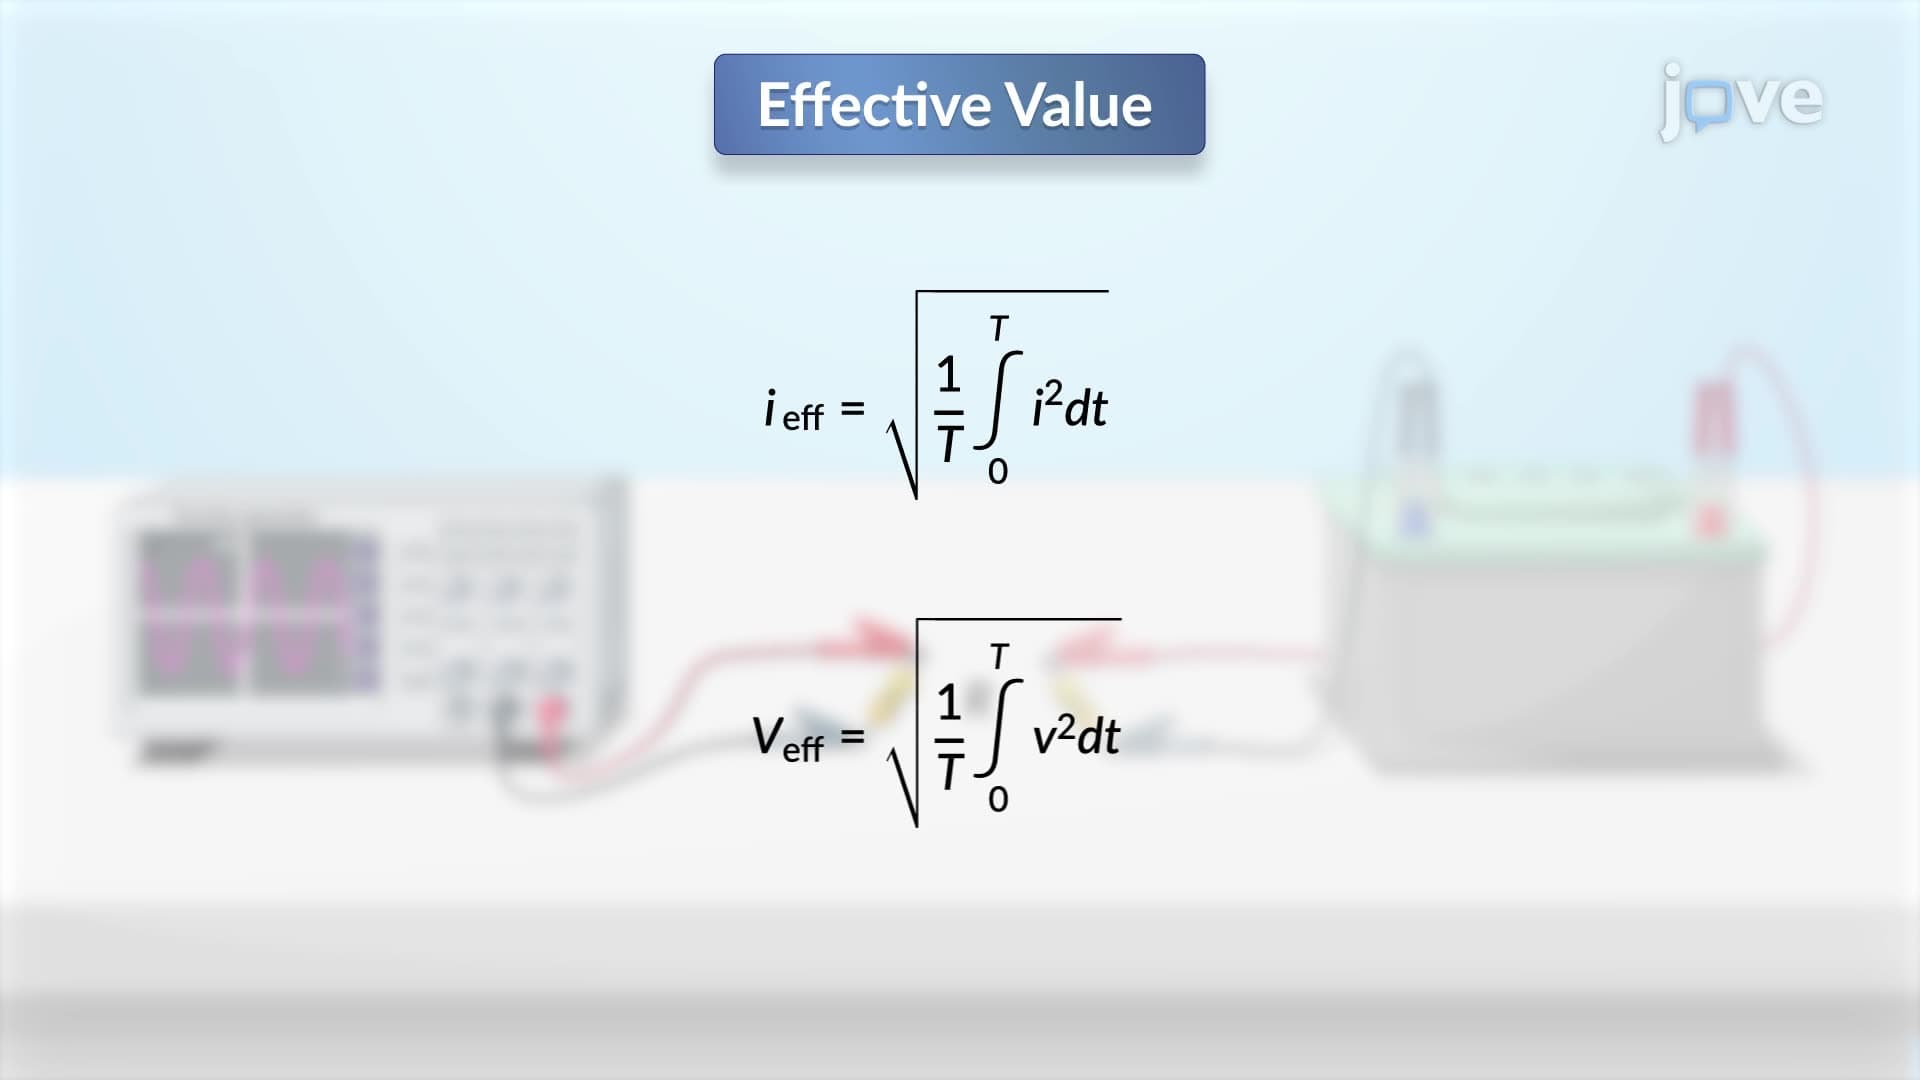
Effective Value of a Periodic Waveform
The effective value of a periodic current represents the direct current (DC) that conveys the same average power to a resistor as the periodic current itself. This concept is crucial when assessing AC circuits. To determine the...
 01:14
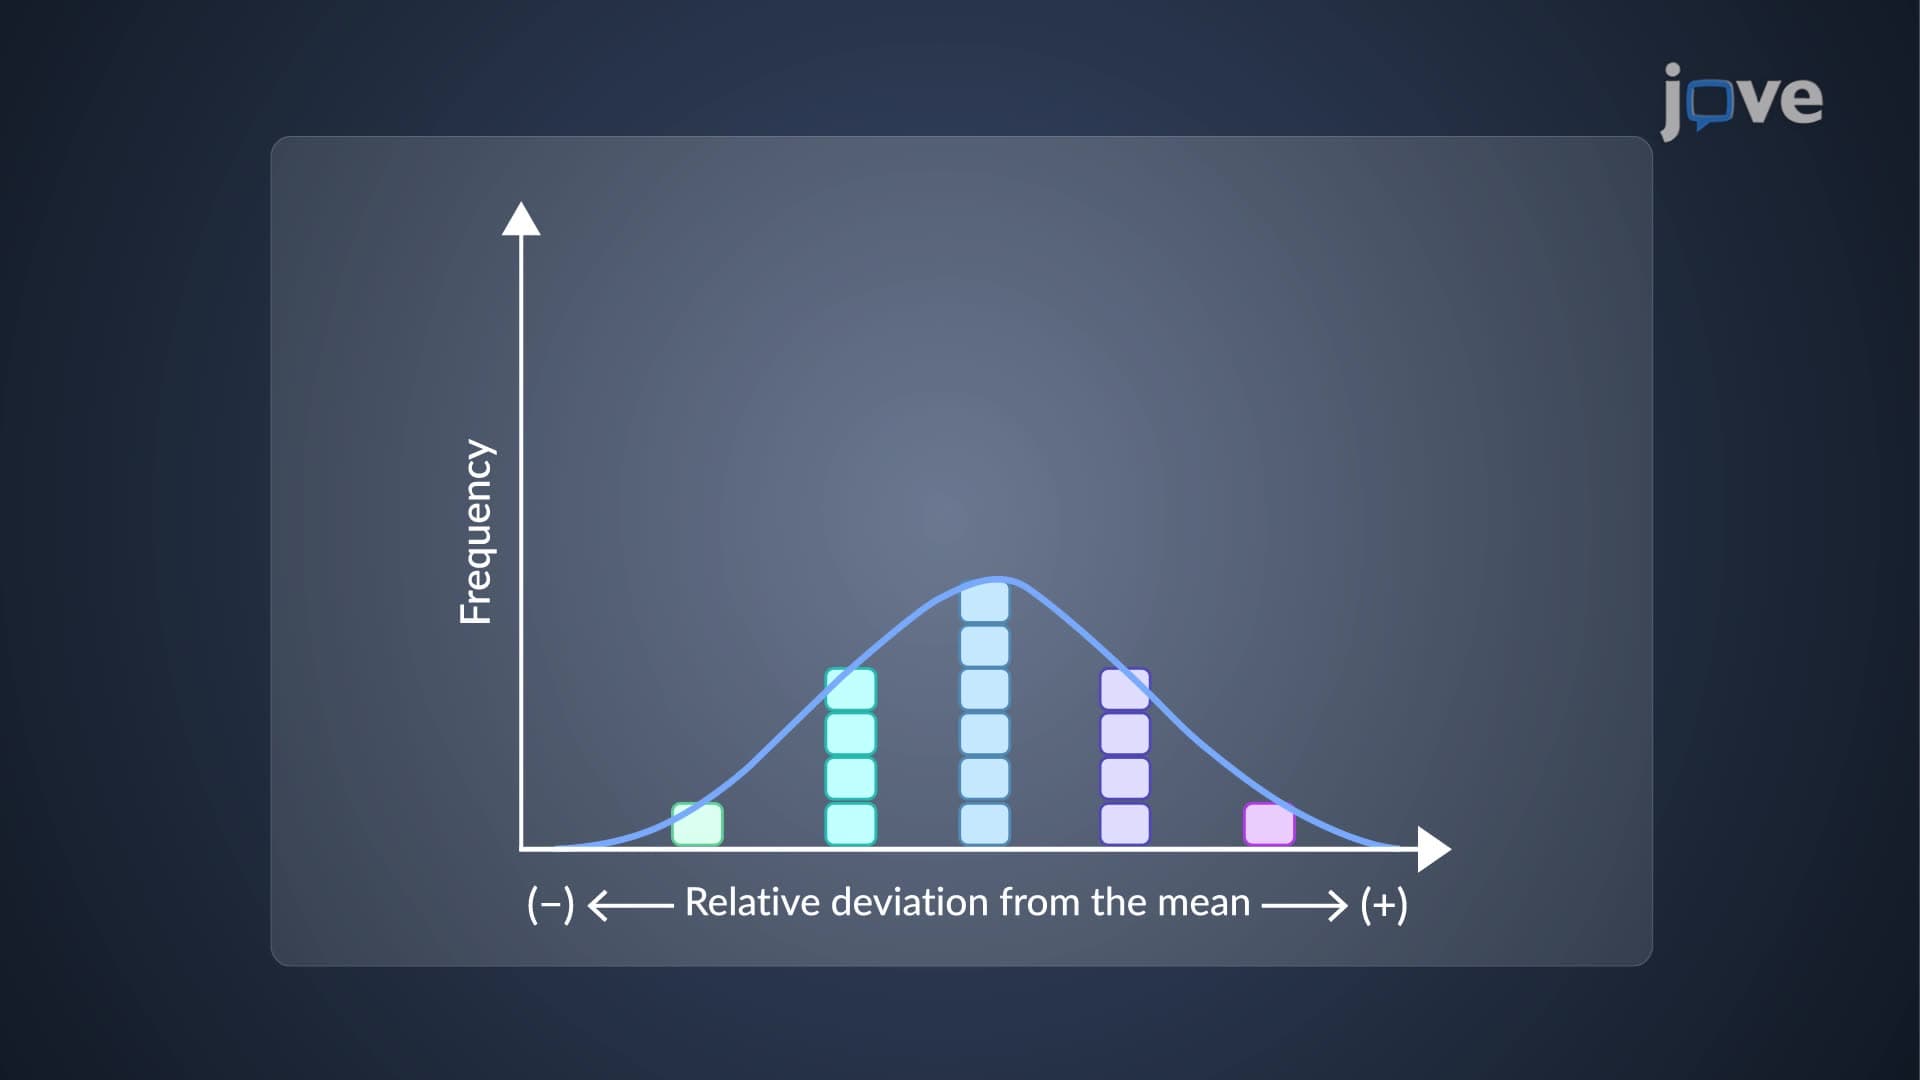
Standard Deviation of Calculated Results
A broad Gaussian distribution curve has a wider standard deviation, representing a data set with...