Related Experiment Video
Updated: Jun 11, 2025

Measuring the Subjective Value of Risky and Ambiguous Options using Experimental Economics and Functional MRI Methods
Published on: September 19, 2012
Multi-model transfer function approach tuned by PSO for predicting stock market implied volatility explained by
Kais Tissaoui1, Sahbi Boubaker2, Besma Hkiri3
1Management Information Systems Department, Applied College, University of Ha'il, P.O. Box 2440, Hail City, Saudi Arabia. k.tissaoui@uoh.edu.sa.

Abstract:
This paper studies the forecasting power of uncertainty emanating from the commodities market, energy market, economic policy, and geopolitical threats to the CBOE Volatility Index (VIX). In this study, the relationship between the various uncertainty metrics throughout the period 2012-2022, using a multi-model transfer function technique optimized by particle swarm optimization (PSO) is estimated. Furthermore, we utilize PSO for parameter optimization within the multi-model framework, improving model performance and convergence speed. According to empirical findings, the CBOE Volatility Index reacts nonlinearly to the uncertainty indices. Specifically, the conclusions of the performance metrics show that the OVX index (MAPE: 4.1559%; RMSE: 1.0476% and W: 96.74%) outperforms the geopolitical risk index, the Bloomberg energy index, and the economic policy uncertainty index in predicting the volatility of the US equities market. Although individual models have generated respectful performance, results from the aggregate simulation show that when all predictors are combined, they simultaneously provide better performance indicators (MAVE: 2.7511 %; RMSE: 0.7361%; R2: 98.93%) than when they are estimated separately. In addition, results provide evidence that, when considering non-linear patterns in the data, the multi-model transfer function technique calibrated using PSO demonstrates its outperformance over autoregressive baseline models, traditional econometric models, and deep learning techniques. The effectiveness and accuracy of the multi-model transfer function method tuned by PSO as a forecasting tool are confirmed by the convergence analysis of the cost function. Our methodology innovates by employing a multi-model transfer function technique, which captures the complex and nonlinear relationships between uncertainty indicators and the VIX more comprehensively than traditional single-model approaches. These results are important for traders in terms of hedging as well as portfolio diversification by investing in defensive equities and for policymakers in terms of reliability and preciseness of volatility forecasts.
More Related Videos
 13:54
A Workflow for Lipid Nanoparticle LNP Formulation Optimization using Designed Mixture-Process Experiments and Self-Validated Ensemble Models SVEM
Published on: August 18, 2023
 09:04
A Modeling and Simulation Method for Preliminary Design of an Electro-Variable Displacement Pump
Published on: June 1, 2022
Related Concept Videos
 00:54
Uncertainty: Confidence Intervals
 01:03
Prediction Intervals
However, the point estimate is most likely not the exact value of the population parameter, but close to it. After calculating point estimates, we construct interval estimates, called confidence intervals or prediction intervals. This prediction interval comprises a range of values unlike the point estimate and is a better predictor of the observed sample value, y.
 00:59
Uncertainty: Overview
 01:21
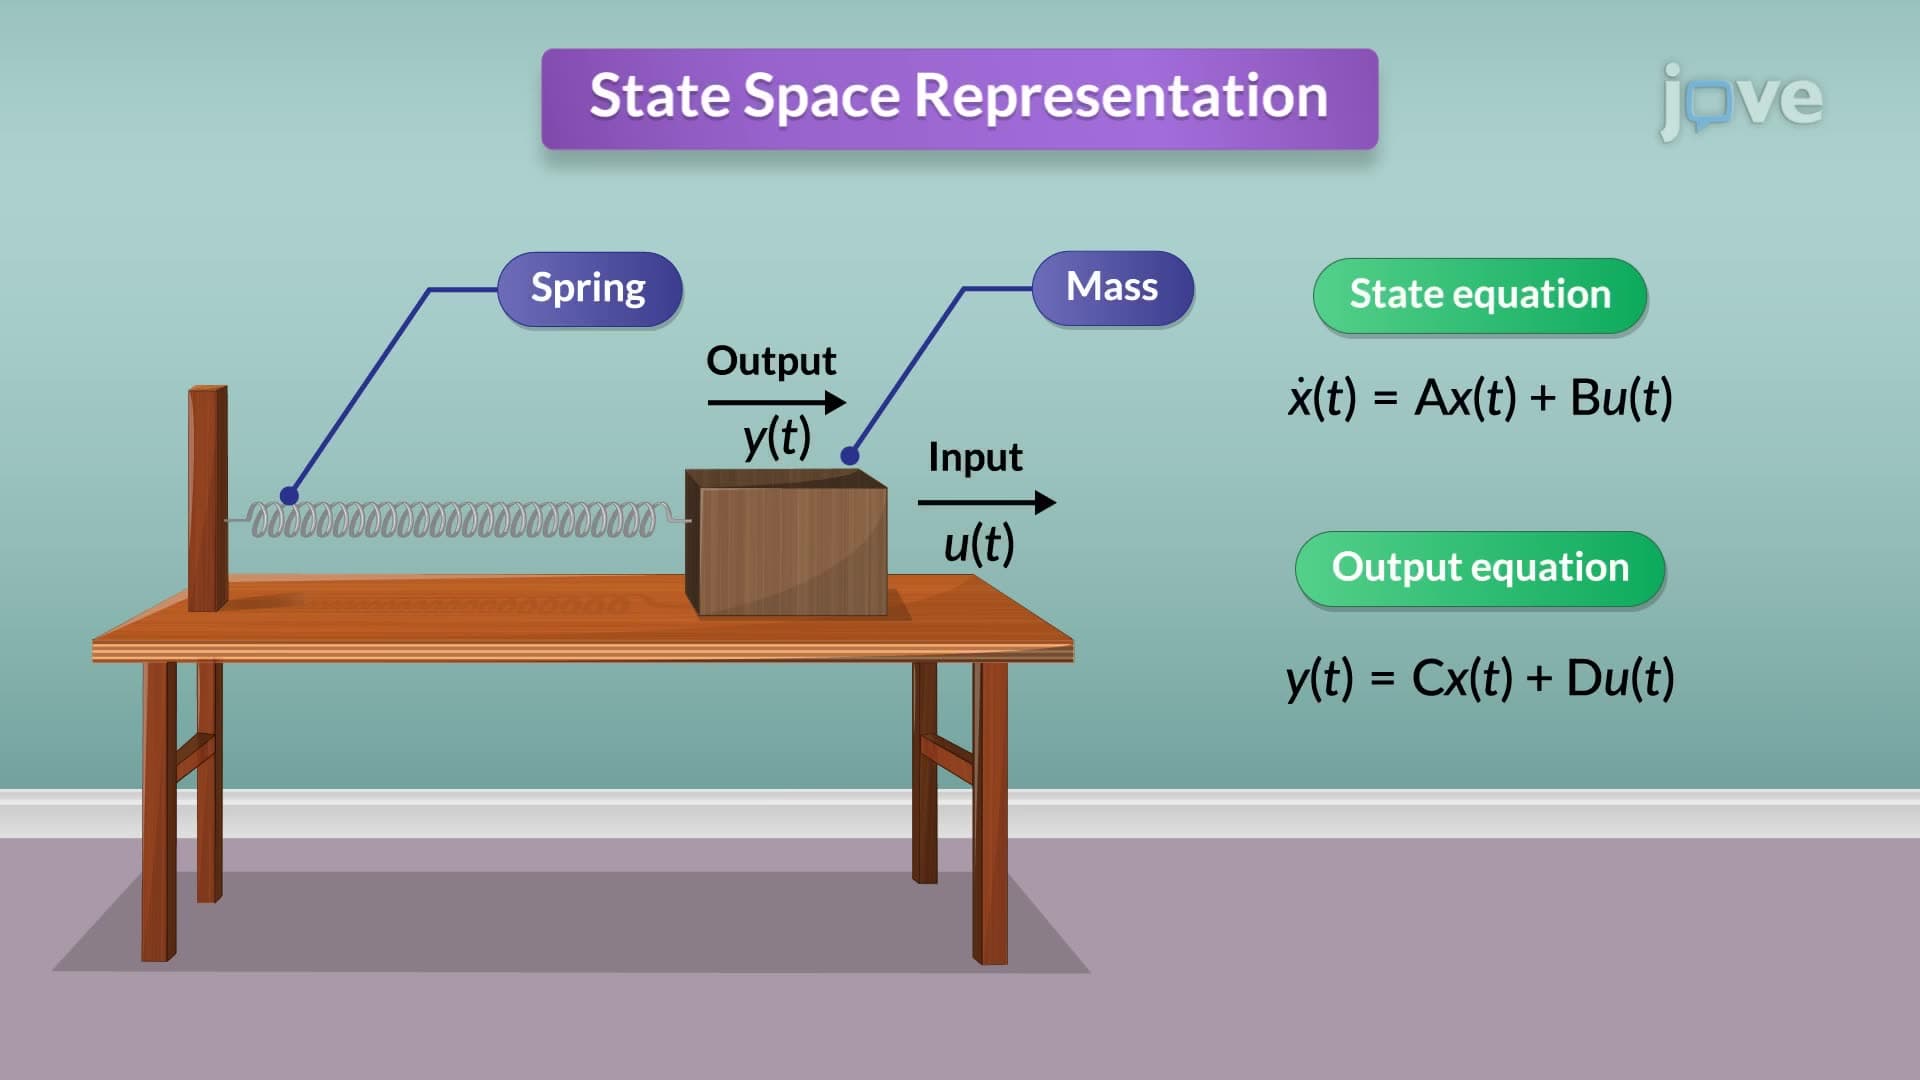
State Space to Transfer Function
The transformation process begins with the state-space representation, characterized by the state equation and the output equation. These equations are typically represented as:
 01:10
Propagation of Uncertainty from Systematic Error
 01:22
Estimating Population Mean with Unknown Standard Deviation
William S. Gosset (1876–1937) of the...