Related Experiment Video
Updated: Jun 11, 2025
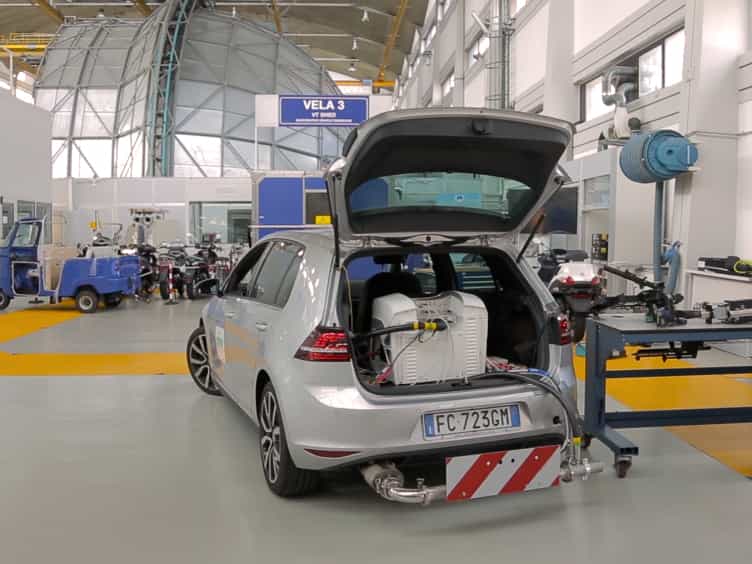
Implementation of Portable Emissions Measurement Systems PEMS for the Real-driving Emissions RDE Regulation in Europe
Published on: December 4, 2016
Can IFRS adoption mitigate earnings management in an emerging market?
Abdelnaser M Mohamed Amer1, Asil Azimli2, Muri Wole Adedokun3
1Faculty of Economics and Administrative Sciences, Department of Accounting and Finance, Cyprus International University, Lefkosa, TRCNC, Mersin, 10, Turkiye.

Abstract:
Research on the impact of the International Financial Reporting Standard (IFRS) mandate on the quality of financial reporting produced mixed findings. Several researchers showed that the IFRS mandate depresses earnings management since it improves comparability, and the principle-based approach offers limited alternatives for managers in reporting. Others have shown that it provides flexibility for managers in institutionally and legally weak countries. We examine whether the IFRS mandate depresses earnings management practices in South Africa. Using a sample of 206 firms listed on the Johannesburg Securities Exchange (JSE) from 2000 to 2010, our findings show that the IFRS mandate significantly reduces earnings management. Our findings contribute to the ongoing discussion about whether high-quality standards effectively mitigate earnings management practices and protect stakeholder rights in developing countries.