Audit reporting standards data from experimental markets
Related Experiment Video
Updated: Sep 25, 2026
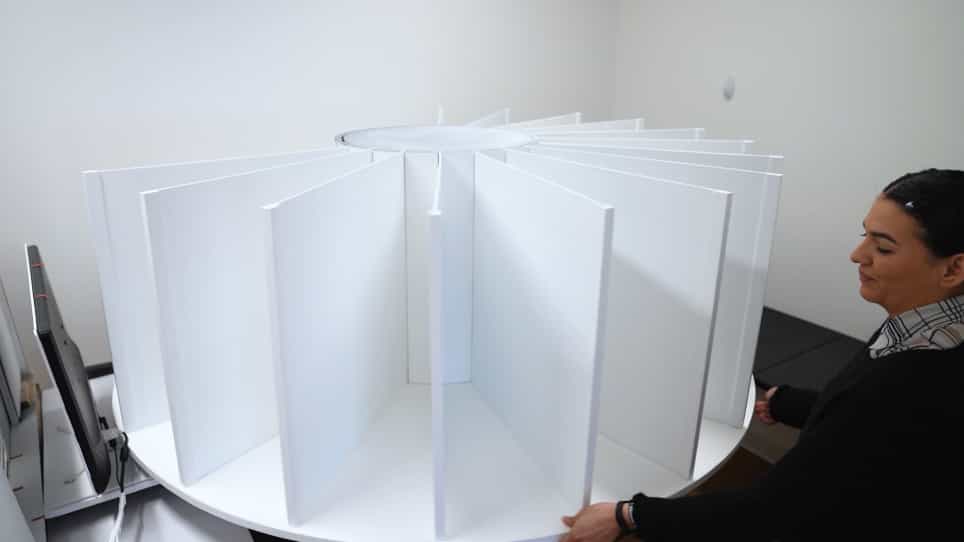
Methods for Presenting Real-world Objects Under Controlled Laboratory Conditions
Published on: June 21, 2019
1Boise State University, 1910 University Drive, Boise, ID, 83725, USA.

Abstract:
We conducted an experimental investigation on the impact of a Disclosure requirement (publicly disclosing auditor participants' actual name) and Sign-Off requirement (requiring auditor participants to sign the audit report) on auditor misreporting decisions. Specifically, we conducted experimental audit markets via networked computers at the Florida State University experimental economics lab with student participants. We utilized a 2 × 2 factorial design, where all manipulations were administered on a between-subjects basis, and all participants maintained their original randomly assigned role throughout the experiment. Two experimental sessions were conducted for each of the four experimental conditions and each session was conducted with two markets operating simultaneously. Each trading year consisted of two periods, and all markets operated for ten trading years for a total of twenty trading periods. Participants were randomly reassigned to a different market group at the end of each market year to help control reputational concerns among participants and remove market group confounds. Each market consisted of four auditors (verifiers), four managers (sellers) and two investors (buyers). Each period of the experiment, the manager must hire an auditor to opine on the value of the asset to sell the asset to the investor. Auditors competed via bid for the right to perform services for every manager in the market in every trading period. Each manager then had to select one auditor to opine on the value of the asset. Each auditor could be selected by any manager every period; thus, any given auditor could be selected to report between zero and four times each period. The experiment was conducted to observe the auditor reporting decisions each period. The auditor could choose to truthfully report the value of the asset as low or misreport the value of the asset as high. Each incident of auditor misreporting impacted the market by transferring the difference in value from the investor to the manager that hired the auditor. The data includes all the asset reporting decisions from each of the experimental sessions conducted for a total of 1,280 observations. To explore the impact of individual personality measures on reporting decisions, we also collected information utilizing a post-experimental questionnaire. The data includes dichotomous variables for misreporting, disclosure, sign-off, and their interaction variable. Each row also reports the subject number, period, second period identifier, bid amount, incumbency, gender as well as the subjects Idealism and Relativism scores and answers to the post-experimental questionnaire. The experimental parameters employed in this experiment differ significantly from previous audit markets addressing audit quality making this data novel and unexplored. Thus, the reported data can be used to address current gaps in the auditing literature related to audit quality particularly where there are inconsistencies in methodology. Moreover, the data can be used to provide additional empirical evidence to regulators on the efficacy of both identity disclosure and signature requirements on audit reporting quality.
Related Concept Videos
 01:19
Testing a Claim about Standard Deviation
The hypothesis testing for the claim of population standard deviation (or variance) requires the data and samples to be random and unbiased. The population distribution also must be normal. There is no specific requirement on the sample size as the estimation is based on the chi-square distribution.
As a first step, the hypothesis (null and alternative) concerning the claim about...
 01:13
Data Collection by Experiments
An example of the experimental method is a public clinical trial...
 01:21
Friedman Two-way Analysis of Variance by Ranks
 01:52
Regression Toward the Mean
 01:15
Study Design in Statistics
Does aspirin reduce the risk of heart attacks? Is one brand of fertilizer more effective at growing roses than another? Is fatigue as dangerous to a driver as the influence of alcohol? Questions like these are answered using randomized experiments with proper...
 01:56
Ethics in Research