Related Experiment Video
Updated: Jan 14, 2026


Identification of Disease-related Spatial Covariance Patterns using Neuroimaging Data
Published on: June 26, 2013
Distribution of singular values in large sample cross-covariance matrices
Arabind Swain1, Sean Alexander Ridout2, Ilya Nemenman3
1Emory University, Department of Physics, Atlanta, Georgia 30322, USA.

Abstract:
For two high-dimensional datasets X and Y, with dimensionalities N_{X} and N_{Y} of order of the number of samples T, estimates of their cross-covariance will have large fluctuations. These sampling fluctuations can be studied by analyzing the case of uncorrelated X and Y, samples of which comprise large matrices X and Y with Gaussian i.i.d. entries and dimensions T×N_{X} and T×N_{Y}, respectively. For this problem, we derive the probability distribution of the singular values of X^{⊤}Y in different parameter regimes. This extends the Marchenko-Pastur result for the distribution of eigenvalues of empirical sample covariance matrices to singular values of empirical cross-covariances. We analyze these results in a variety of limits, arguing that in many cases signals may be detected even if one or both datasets are of dimensionality greater than the number of samples, where methods based on whitening of the cross-covariance cannot be used. Our results will help to establish statistical significance of cross-correlations in many data-science applications.
Related Concept Videos
 01:15
One-Way ANOVA: Equal Sample Sizes
Different sample means can result in different values for the variance estimate: variance between samples. This is because the variance between samples is calculated as the product of the sample size and the variance between the...
 01:10
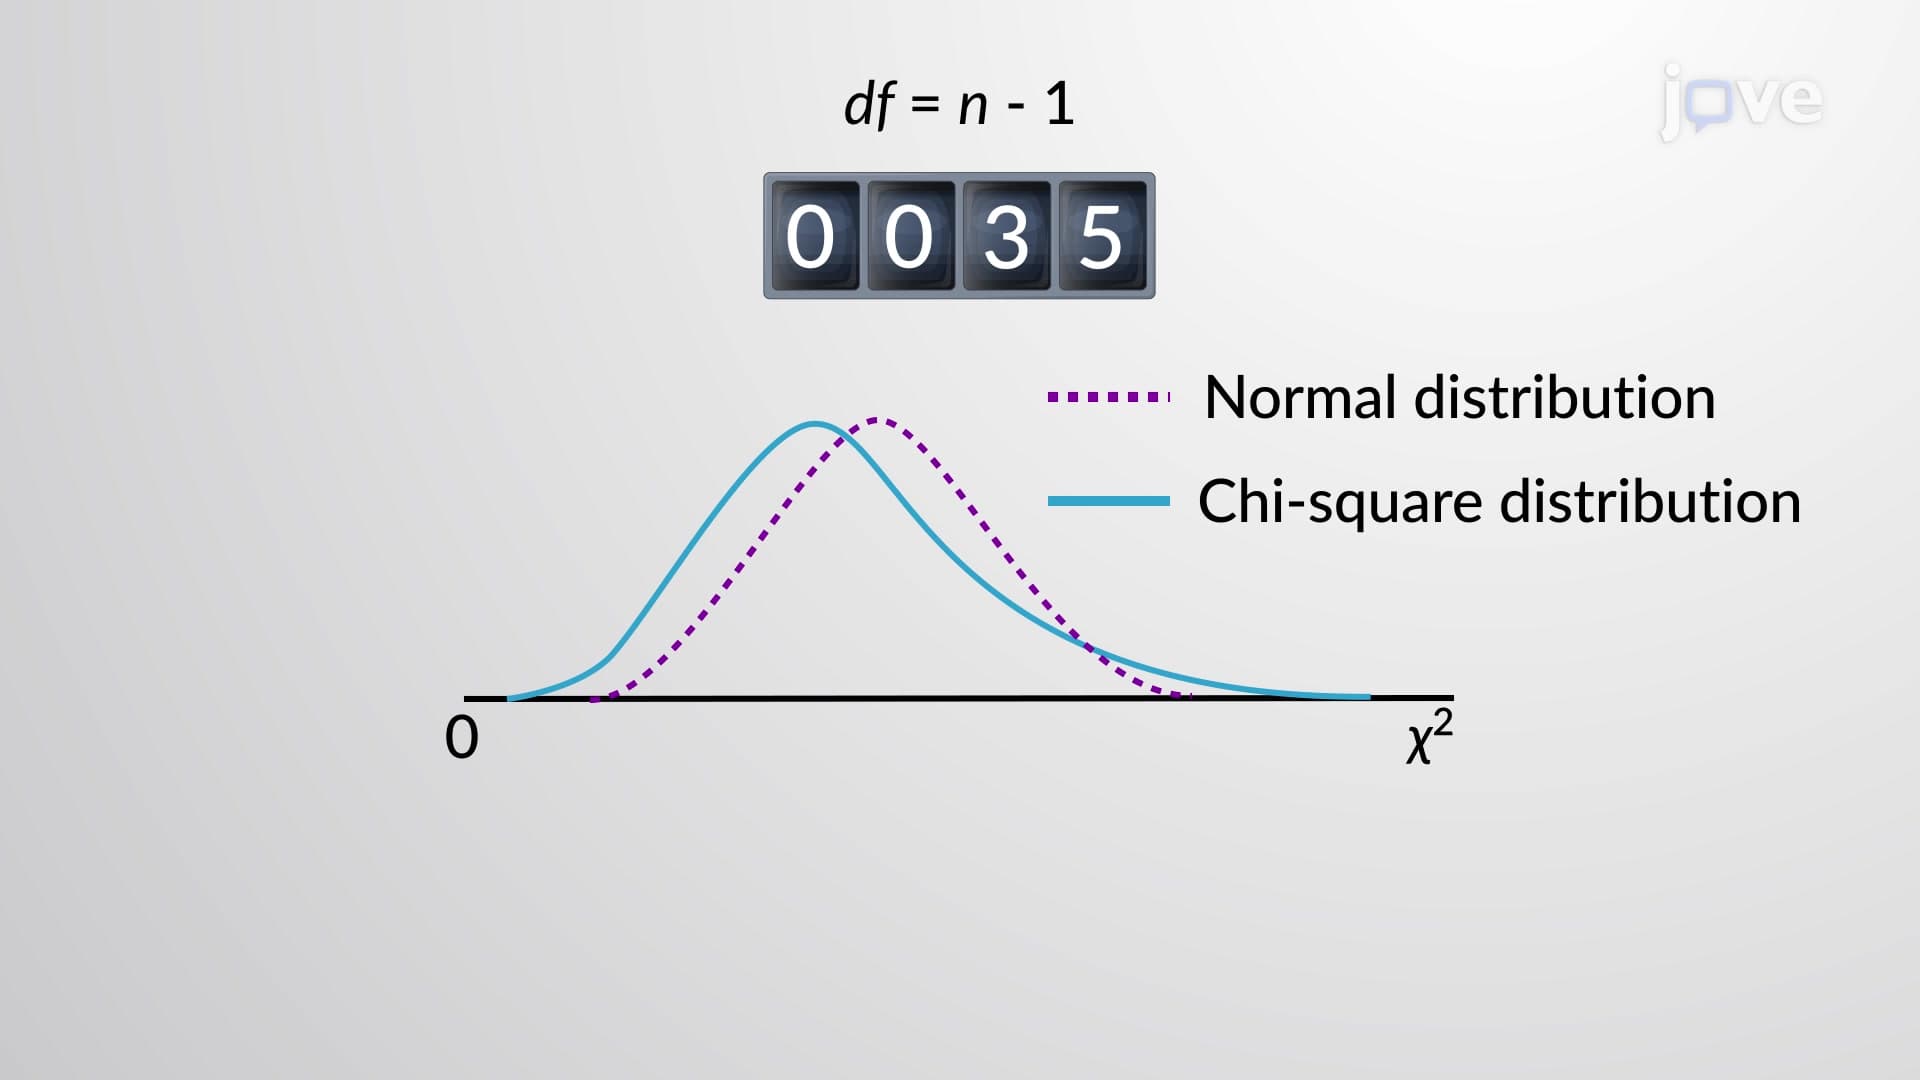
Chi-square Distribution
 01:15
One-Way ANOVA: Unequal Sample Sizes
 01:26
Distributions to Estimate Population Parameter
 01:14
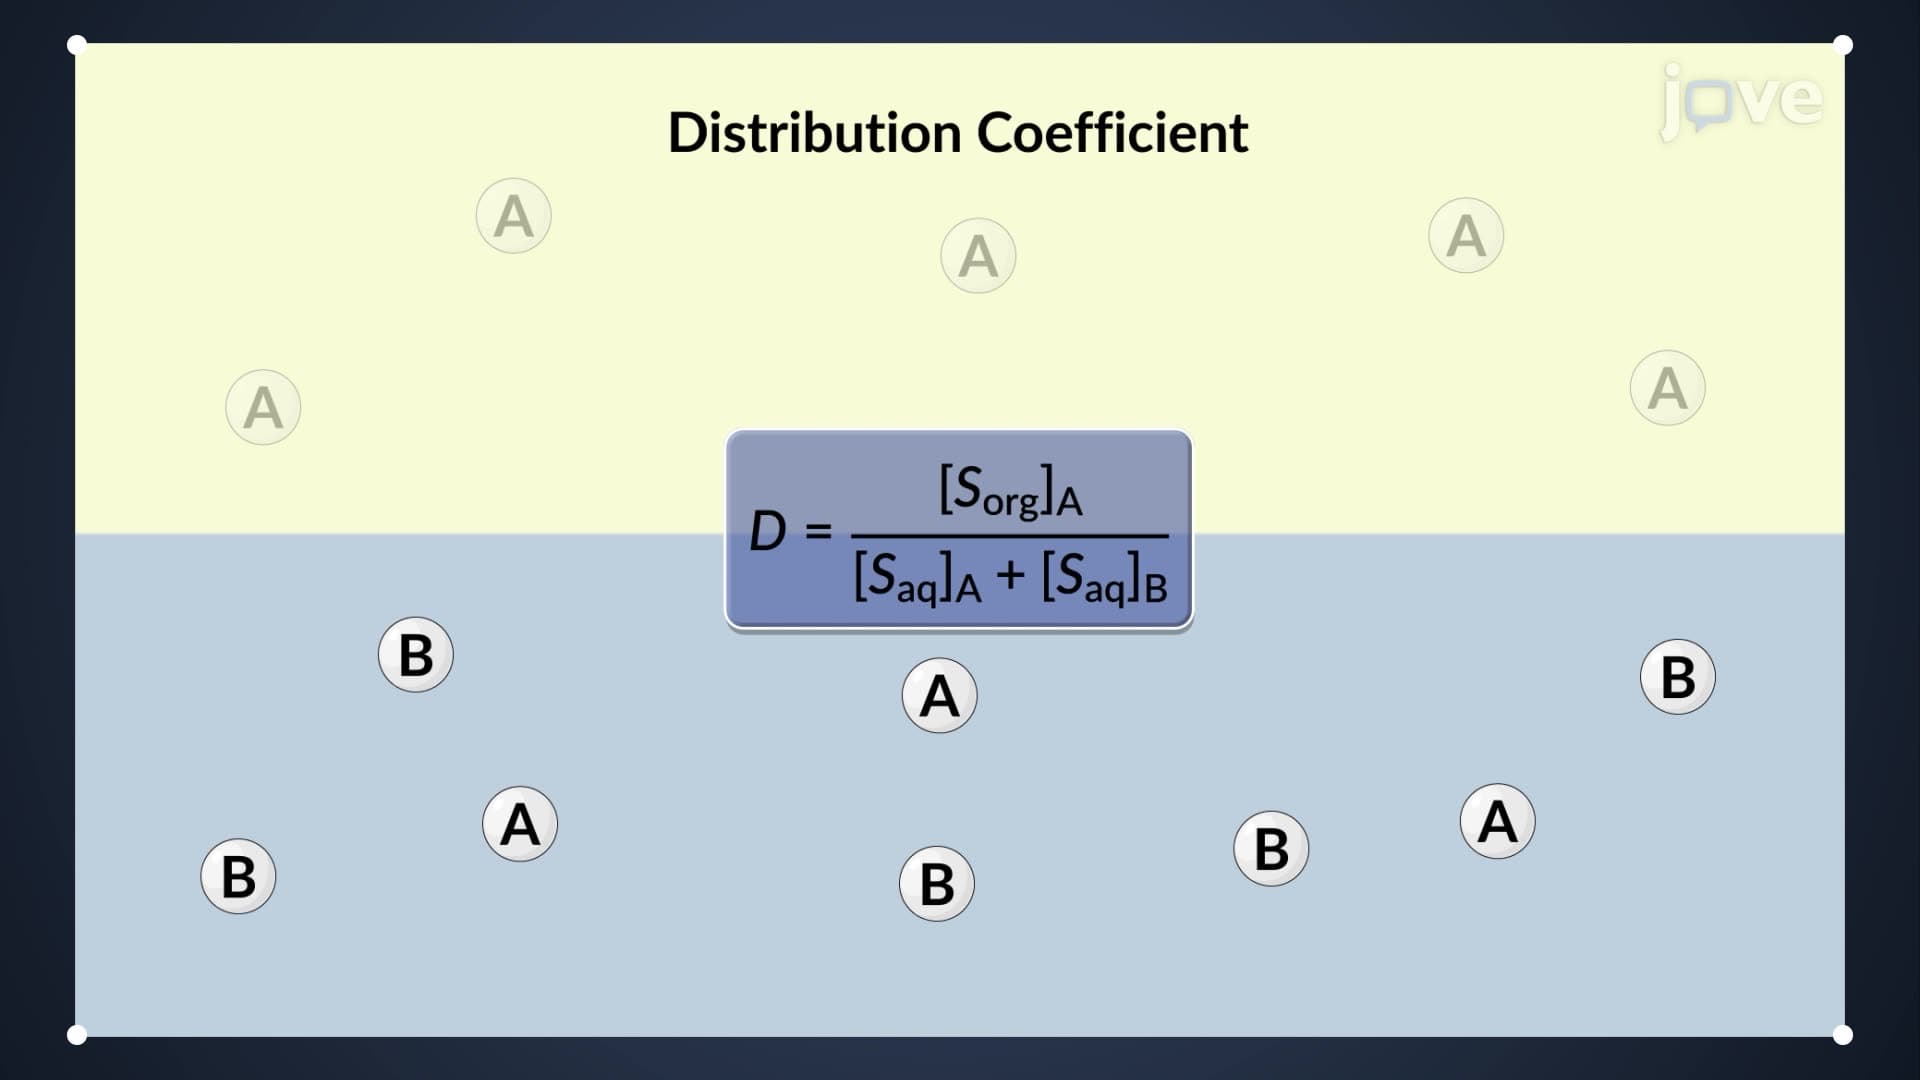
Extraction: Partition and Distribution Coefficients
For extracting a solute from an aqueous phase into an...
 01:14
Wilcoxon Signed-Ranks Test for Median of Single Population