Related Experiment Video
Updated: Jan 8, 2026
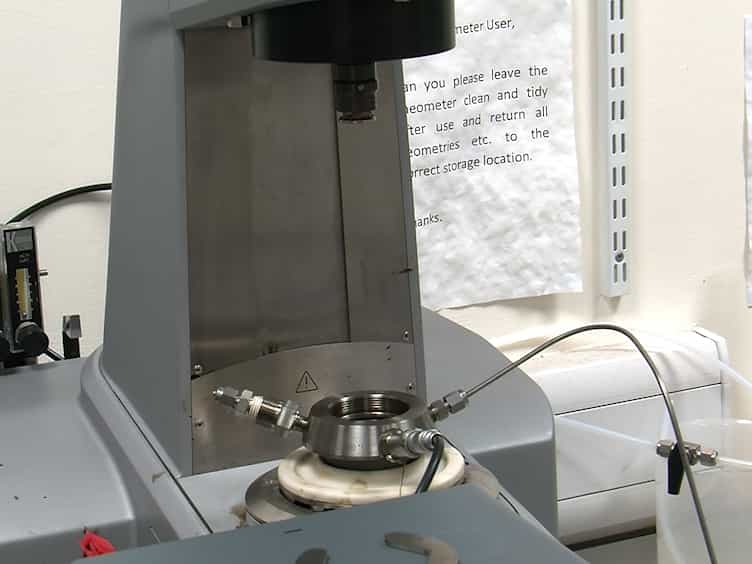

Measurement of the Rheology of Crude Oil in Equilibrium with CO2 at Reservoir Conditions
Published on: June 6, 2017
A Hybrid GARCH-BiLSTM-KAN Model for Crude Oil Price Forecasting: Capturing Volatility, Temporal Dependencies, and
1Business School, Guangzhou College of Technology and Business.

Abstract:
Crude oil prices, as a cornerstone of global energy markets, exhibit intricate dynamics---including volatility clustering, asymmetric temporal dependencies, and nonlinear responses to geopolitical, economic, and supply-demand shocks---posing formidable challenges to accurate forecasting. Existing models often struggle to simultaneously capture these multifaceted characteristics, limiting their predictive robustness. To address this, this study proposes a novel hybrid framework which synergistically integrates three complementary components: (1) the Generalized Autoregressive Conditional Heteroskedasticity model to quantify time-varying volatility and address clustering effects; (2) the Bidirectional Long Short-Term Memory network to model bidirectional temporal relationships, capturing both historical and future contextual influences on price movements; and (3) the Kolmogorov-Arnold Network to refine nonlinear patterns through univariate basis functions, enhancing the mapping of complex high-dimensional dependencies beyond the capabilities of traditional neural networks. Empirical validation is conducted using 39 years of daily West Texas Intermediate crude oil prices (1986-2025), a dataset encompassing critical events such as the 2008 financial crisis, 2020 COVID-19 pandemic, and 2022 geopolitical tensions, ensuring robustness across diverse market conditions. The proposed model is rigorously compared against benchmark models, including traditional volatility models, standalone deep learning architectures, and other hybrid models. Results demonstrate that the proposed hybrid achieves superior performance with the lowest root mean squared error, mean absolute error, and the highest coefficient of determination. Statistical tests confirm the significance of its outperformance, highlighting the synergistic value of integrating volatility modeling, bidirectional sequence learning, and advanced nonlinear refinement. This research advances energy economics by providing a robust forecasting tool, with implications for policymakers in strategic energy planning, energy firms in risk hedging, and financial institutions in derivative pricing and portfolio optimization.
Related Concept Videos
 01:07
Residual Plots
When the residual values are plotted against the variable x, it is called a residual...
 01:13
Parameters Affecting Nonlinear Elimination: Zero-Order Input, First-Order Absorption and Two-Compartment Model
When a drug is administered through a constant intravenous infusion and eliminated via nonlinear pharmacokinetics, it follows zero-order input. For example, oral drugs undergo first-order absorption upon administration and are eliminated through nonlinear pharmacokinetics.
In the case of subcutaneously administered drugs,...
 01:14
Multicompartment Models: Overview
These models offer a more comprehensive representation of drug behavior in the body than one-compartment models. They accommodate the complexity of drug distribution,...
 02:14
Combustion Energy: A Measure of Stability in Alkanes and Cycloalkanes
Alkanes undergo combustion in the presence of excess oxygen and high-temperature conditions to give carbon dioxide and water. A combustion reaction is the energy source in natural gas, liquified...
 01:06
Model Approaches for Pharmacokinetic Data: Distributed Parameter Models
The distributed parameter models are specifically designed to account for variations and differences in some drug classes. This model is particularly useful for assessing regional concentrations of anticancer or...
 00:54
Time-Series Graph