Related Experiment Video
Updated: Mar 11, 2026

Measuring the Subjective Value of Risky and Ambiguous Options using Experimental Economics and Functional MRI Methods
Published on: September 19, 2012
Random Neural Networks for Rough Volatility
Antoine Jacquier1,2, Žan Žurič1
1Department of Mathematics, Imperial College London, London, UK.

Abstract:
We construct a deep learning-based numerical algorithm to solve path-dependent partial differential equations arising in the context of rough volatility. Our approach is based on interpreting the PDE as a solution to an BSDE, building upon recent insights by Bayer, Qiu and Yao, and on constructing a neural network of reservoir type as originally developed by Gonon, Grigoryeva, Ortega. The reservoir approach allows us to formulate the optimisation problem as a simple least-square regression for which we prove theoretical convergence properties.

Related Concept Videos
 01:09
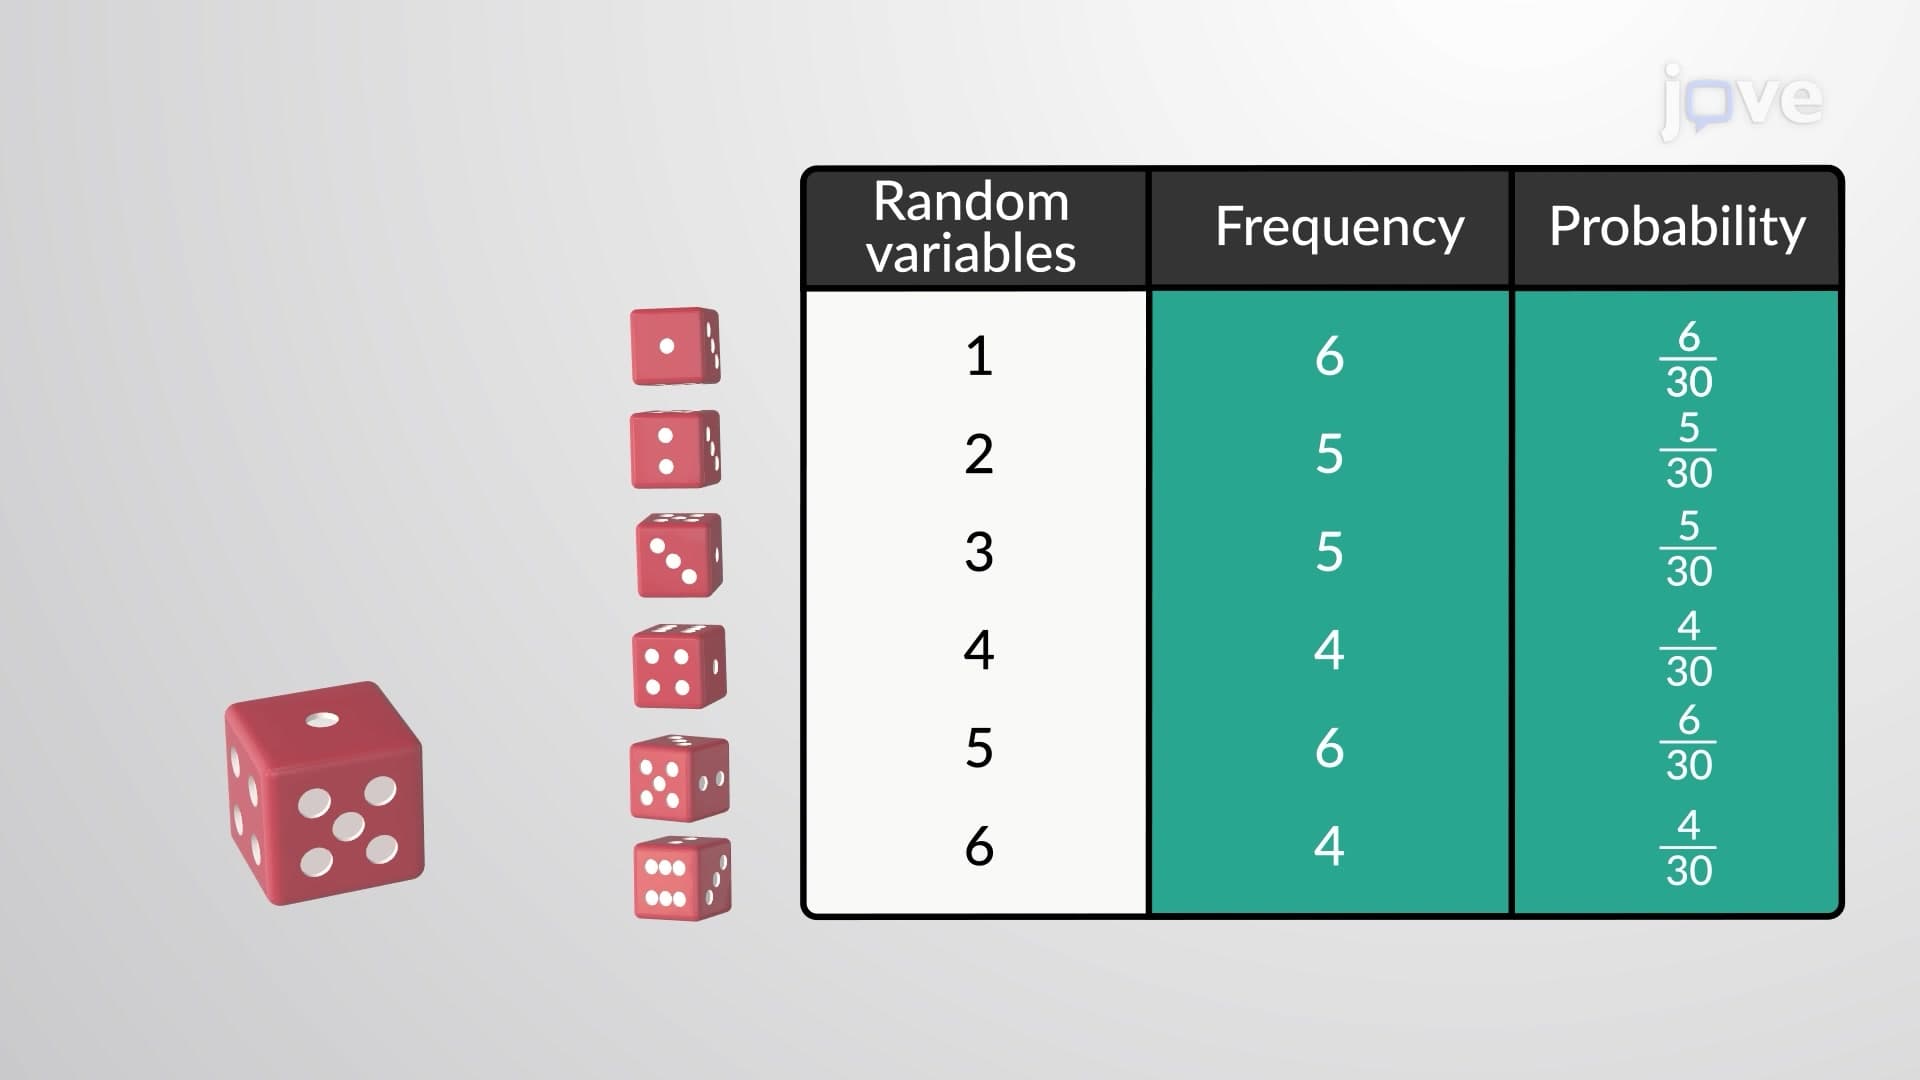
Random Variables
Uppercase letters such as X or Y denote a random variable. Lowercase letters like x or y denote the value of a random variable. If X is a random variable, then X is written in words, and x is given as a number.
For example, let X = the...
 00:59
Propagation of Uncertainty from Random Error
 01:04
Random Error
 01:20
Random and Systematic Errors
 01:37
Neural Regulation
 01:32
Probability Distributions
A discrete probability distribution is a probability distribution of discrete random variables. It can be categorized into binomial probability distribution and Poisson...