Related Experiment Video
Updated: Jun 27, 2026

Measuring the Subjective Value of Risky and Ambiguous Options using Experimental Economics and Functional MRI Methods
Published on: September 19, 2012
Analytic Approximation for Bachelier Option Prices and Applications
1Department of Economics and Business, Barcelona School of Economics, Universitat Pompeu Fabra, Ramón Trias Fargas 25-27, 08005 Barcelona, Spain.

Abstract:
It is well-known that, in the Bachelier model, when asset prices and volatilities are uncorrelated, the at-the-money implied volatility coincides with the fair value of the volatility swap. Using this identity as a starting point and applying classical Itô calculus and Taylor expansions, we write the price for out-of the-money (OTM) and in-the-money (ITM) options as an expansion with respect to the moneyness, where the coefficients are related to the negative (non-integer) powers of the future mean volatility. As an a application, we use it as a control variate to reduce the variance of Monte Carlo option prices in the correlated case.
Related Concept Videos
 01:24
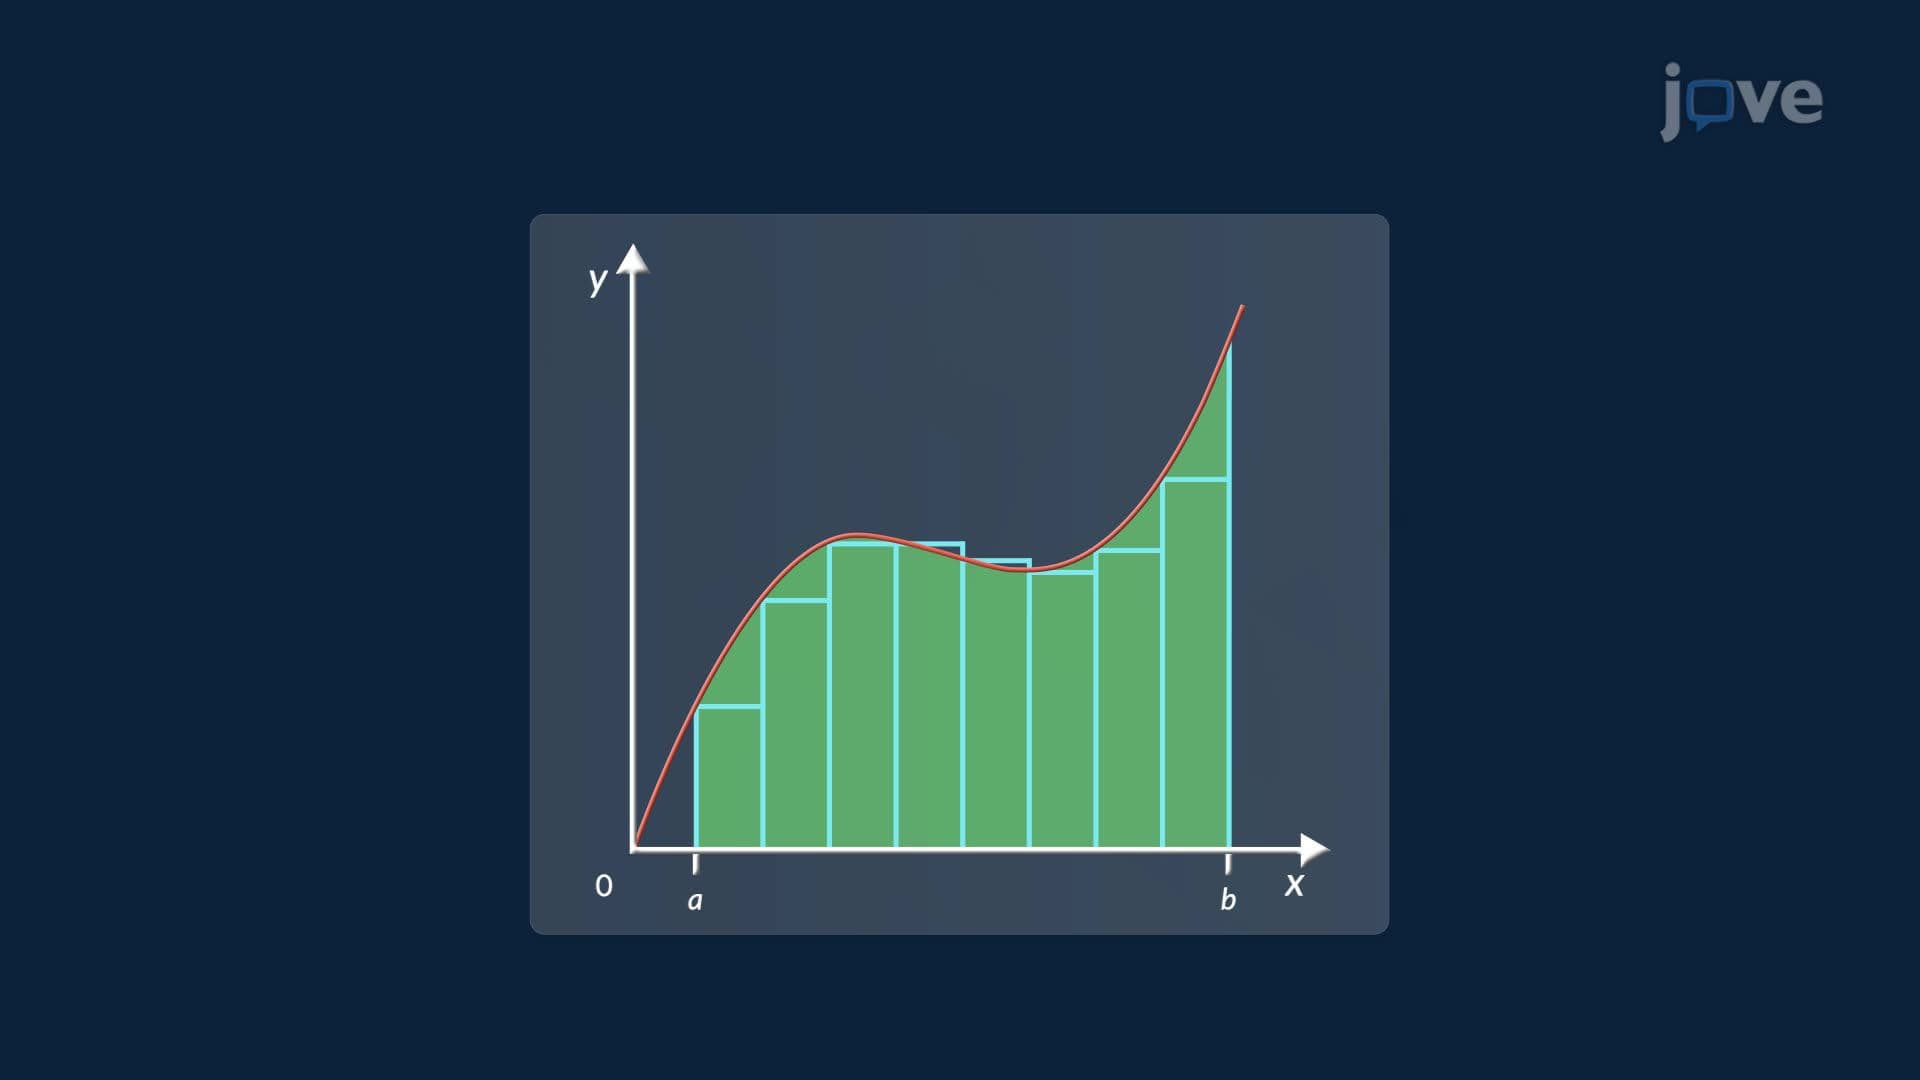
Approximate Integration
 01:29
Application of Differentiation to Business
 01:26
Linearization and Approximation
 01:25
First Derivative Test: Problem Solving
 01:28
Accuracy, limits, and approximation
Accuracy is defined as the closeness of the measured value to the true or actual value. In engineering mechanics, repeated measurements are taken during theoretical or experimental analyses to ensure that the result is precise and accurate.
The accuracy of any solution is based on the...
 01:23
Linear Approximations