Related Experiment Video
Updated: Aug 5, 2026

Dynamic Digital Biomarkers of Motor and Cognitive Function in Parkinson's Disease
Published on: July 24, 2019
Core-periphery dynamics in market-conditioned financial networks: A conditional p-threshold mutual information
Kundan Mukhia1, Imran Ansari2, Salam Rabindrajit Luwang1
1Department of Physics, National Institute of Technology Sikkim, Sikkim 737139, India.

Abstract:
This study investigates how financial market structure reorganizes during the COVID-19 crash using a conditional p-threshold mutual information (MI) based Minimum Spanning Tree (MST) network framework. We analyze nonlinear dependencies among the largest stocks from four economically diverse QUAD countries: the United States, Japan, Australia, and India. The crash period is identified using the Hellinger distance and further characterized by the Hilbert spectrum. A crash is defined when the Hellinger distance exceeds the threshold, enabling the segmentation of the data into pre-crash, crash, and post-crash periods. To isolate direct stock-level dependencies, the conditional p-threshold MI approach filters out common market effects and applies permutation-based significance testing. The resulting statistically validated dependencies are used to construct MST networks, allowing consistent comparison across market periods. The network analysis reveals common crisis-related dynamics across all markets. During the crash, networks become more integrated, with shorter path lengths and higher centrality, while algebraic connectivity declines, indicating increased structural fragility. A clear reorganization of the core-periphery structure is observed, with declining core concentration and increasing periphery fragility, supported by disassortative mixing that facilitates shock transmission. In the post-crash period, network topology shows partial and non-uniform recovery, suggesting persistent structural effects. This interpretation is further supported by an aftershock analysis based on the Gutenberg-Richter law, which indicates a higher relative frequency of large volatility events following the crash. The consistency of these findings across all four markets highlights the effectiveness of the conditional p-threshold MI framework for capturing nonlinear interdependencies and systemic vulnerability in financial markets.
Related Concept Videos
 01:26
Equity Theory
 01:28
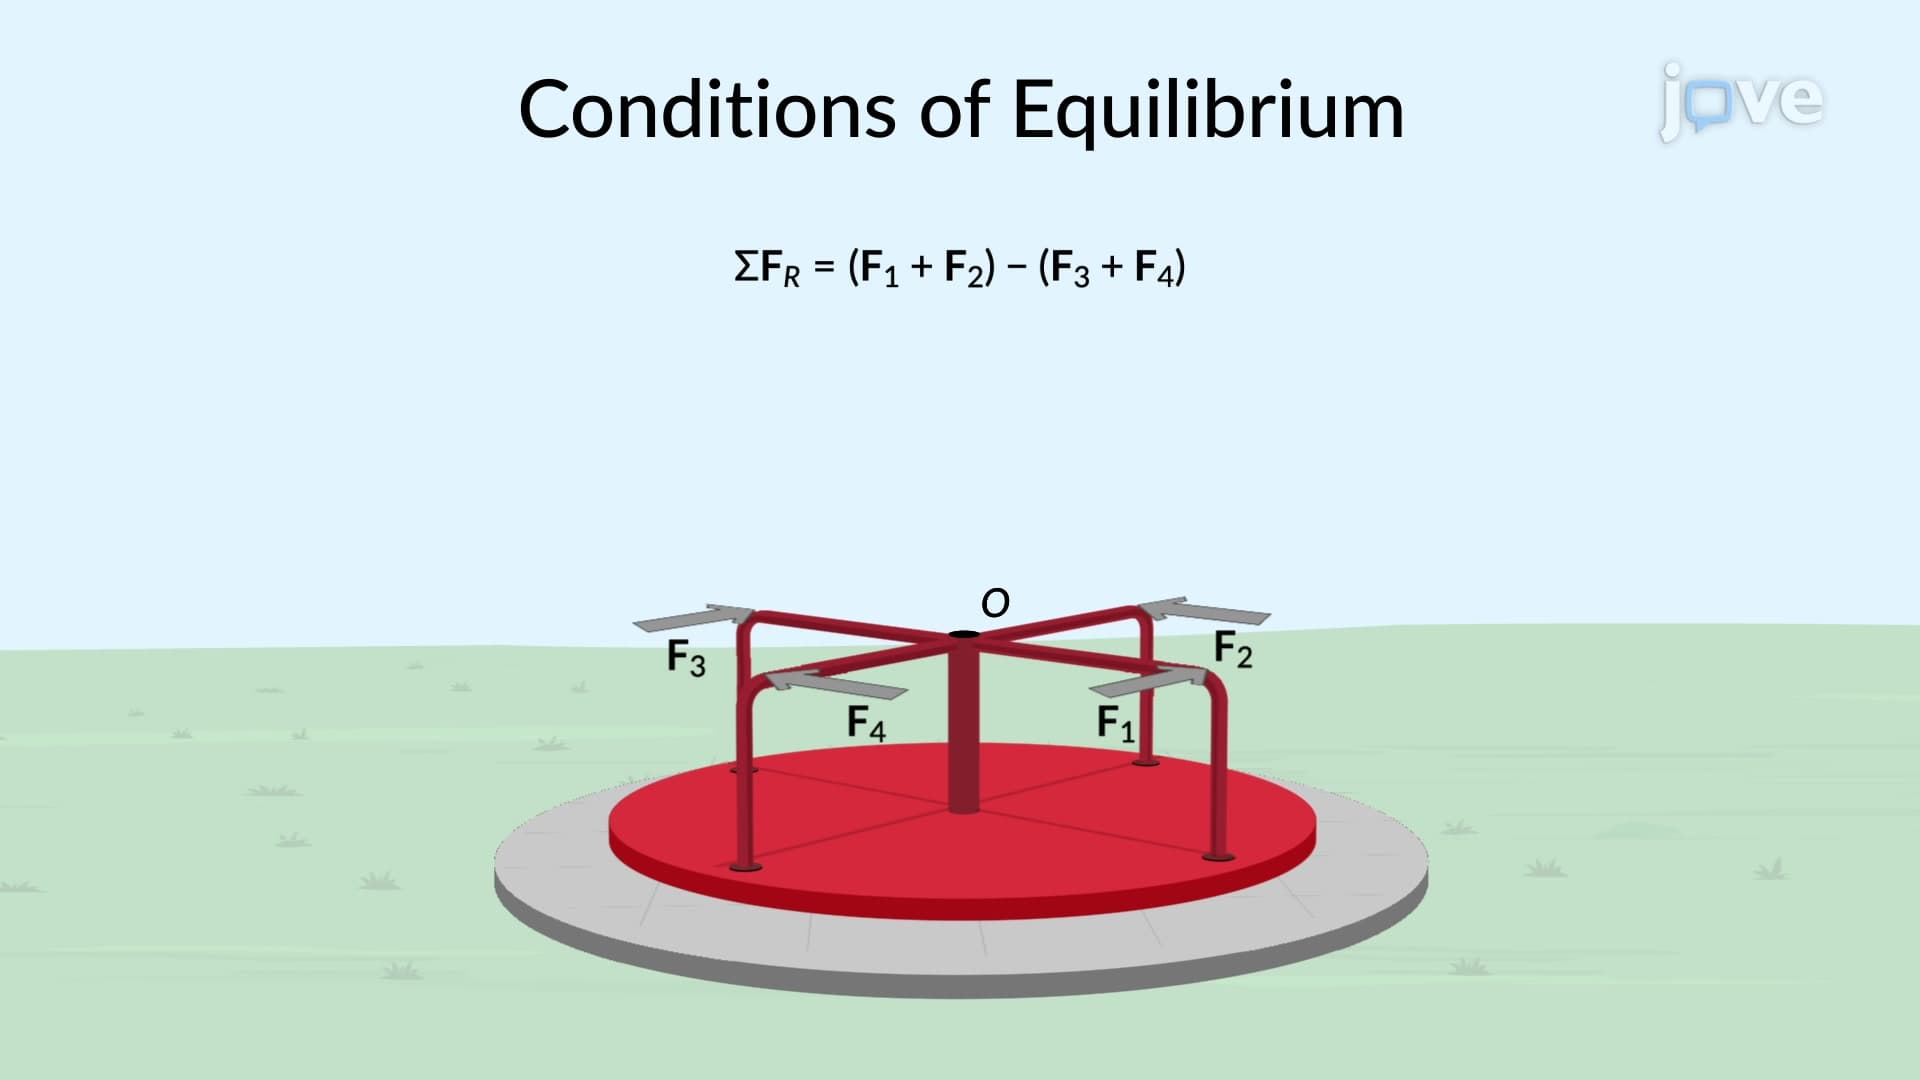
Conditions of Equilibrium
Internal forces are not considered for conditions of equilibrium because they occur in equal and opposite pairs within the body, effectively canceling each other. As a result,...
 01:23
Pore Size Distribution
Adequate...
 01:22
Net Change Theorem
 01:19
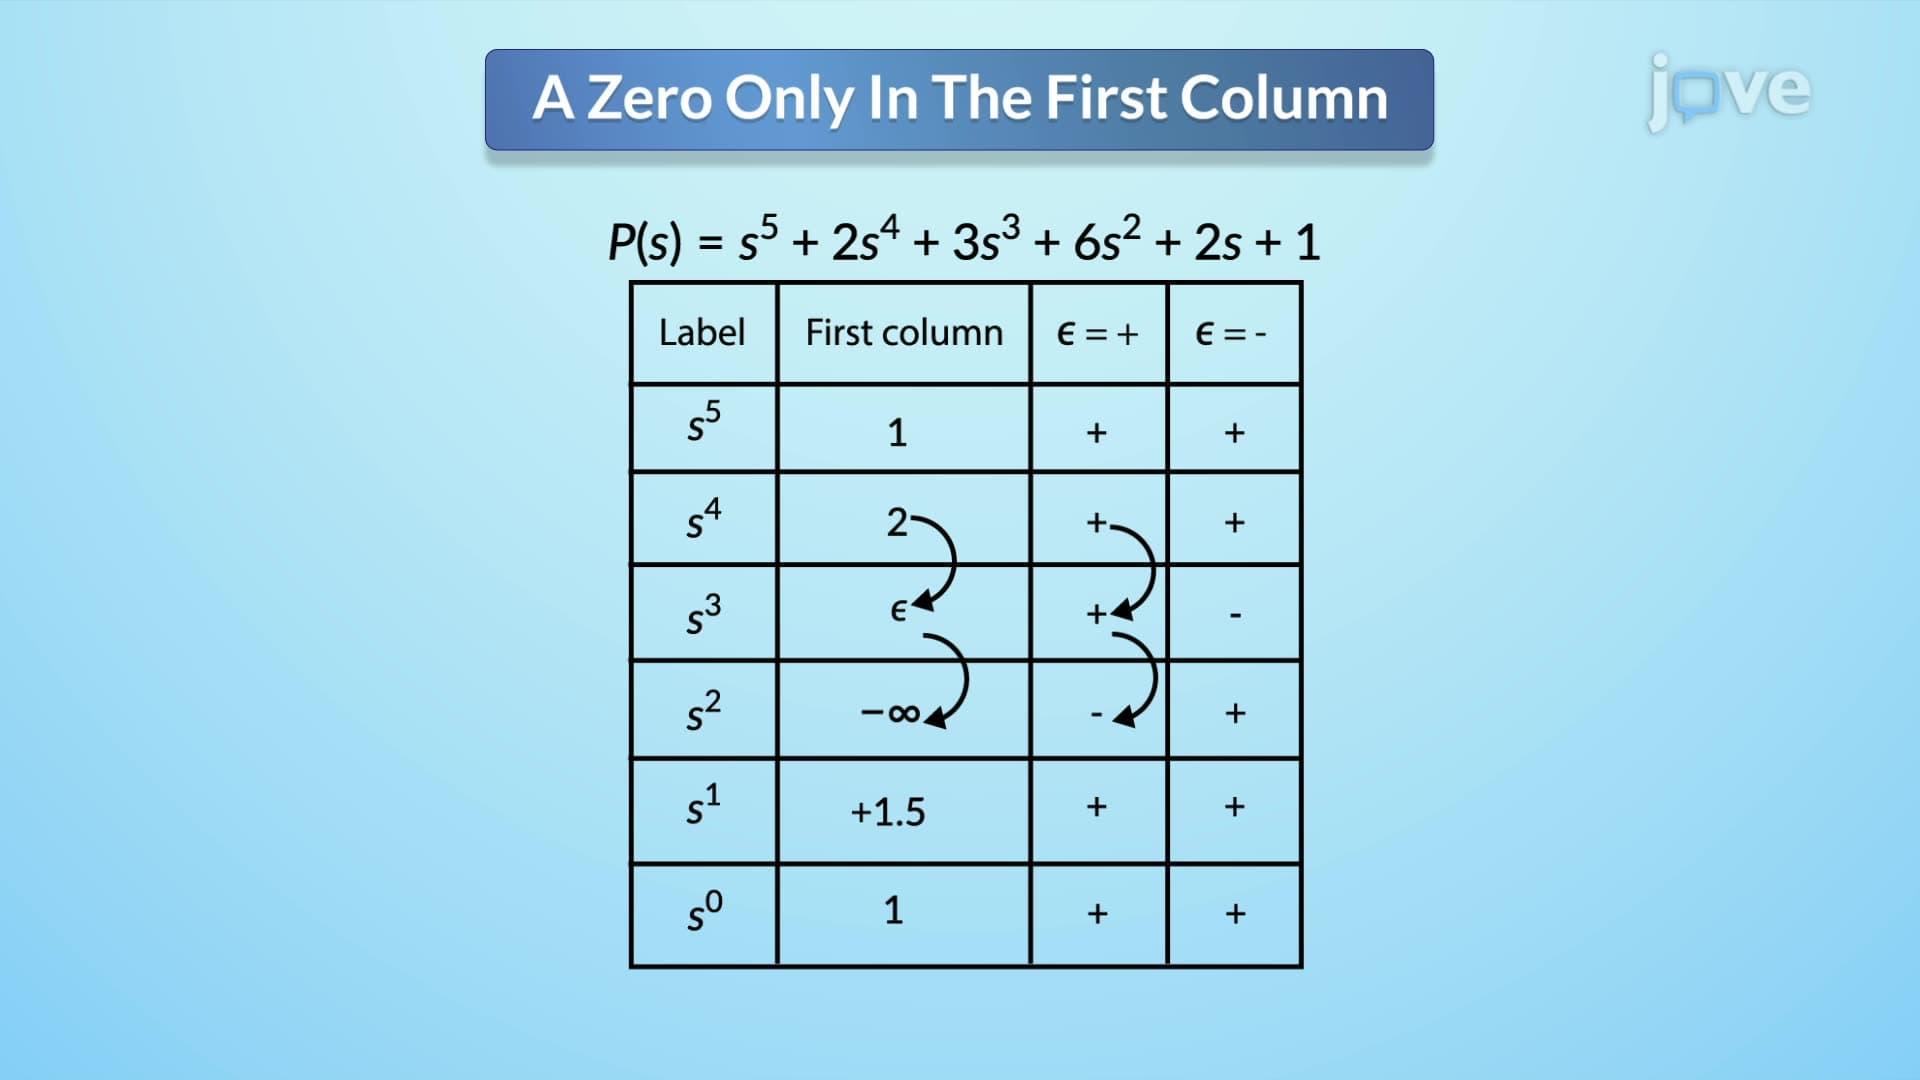
Routh-Hurwitz Criterion II
The first scenario occurs when a singular zero appears in the first column of the Routh table. This situation creates a division by zero issues. To resolve this, a small positive or negative number, denoted as epsilon (∈), is substituted for the zero. The stability analysis proceeds by assuming a sign for ∈. If ∈ is positive, any sign change in the first column of the Routh...
 00:56
Noncompartmental Analysis: Statistical Moment Theory