Related Experiment Videos
The Free Energy Principle and Free Markets
Karl Friston1, Johan Medrano1,2, Tim Verbelen3
1Queen Square Institute of Neurology, University College London, London WC1N 3AR, UK.

Abstract:
We apply the free energy principle to free markets by treating the Market as a random dynamical system with an attracting set, i.e., some characteristic states. This licenses a normal form for stochastic dynamics that inherits from the Helmholtz-Hodge decomposition. Equipped with this functional form-and a suitable parameterization-one can create a generative model of fluctuations in the value of assets and accompanying indicator variables. This affords the opportunity for prospective (ex ante) prediction, scenario modelling and forecasting that could, in principle, be applied to any complex dynamical system exhibiting stochastic chaos. Here, we illustrate the application to portfolio management-in the context of financial services-and use the (posterior) predictive densities over future paths to evaluate the expected free energy that underwrites active inference. In this application, active inference reduces to risk-sensitive control, which can be used to model the optimal decision-making of an agent or investor. In this setting, an investor is characterized by their prior preferences for a high rate of return under drawdown constraints. Using numerical studies and historical financial data, we quantify the improvement in portfolio management, relative to baseline policies.
Related Concept Videos
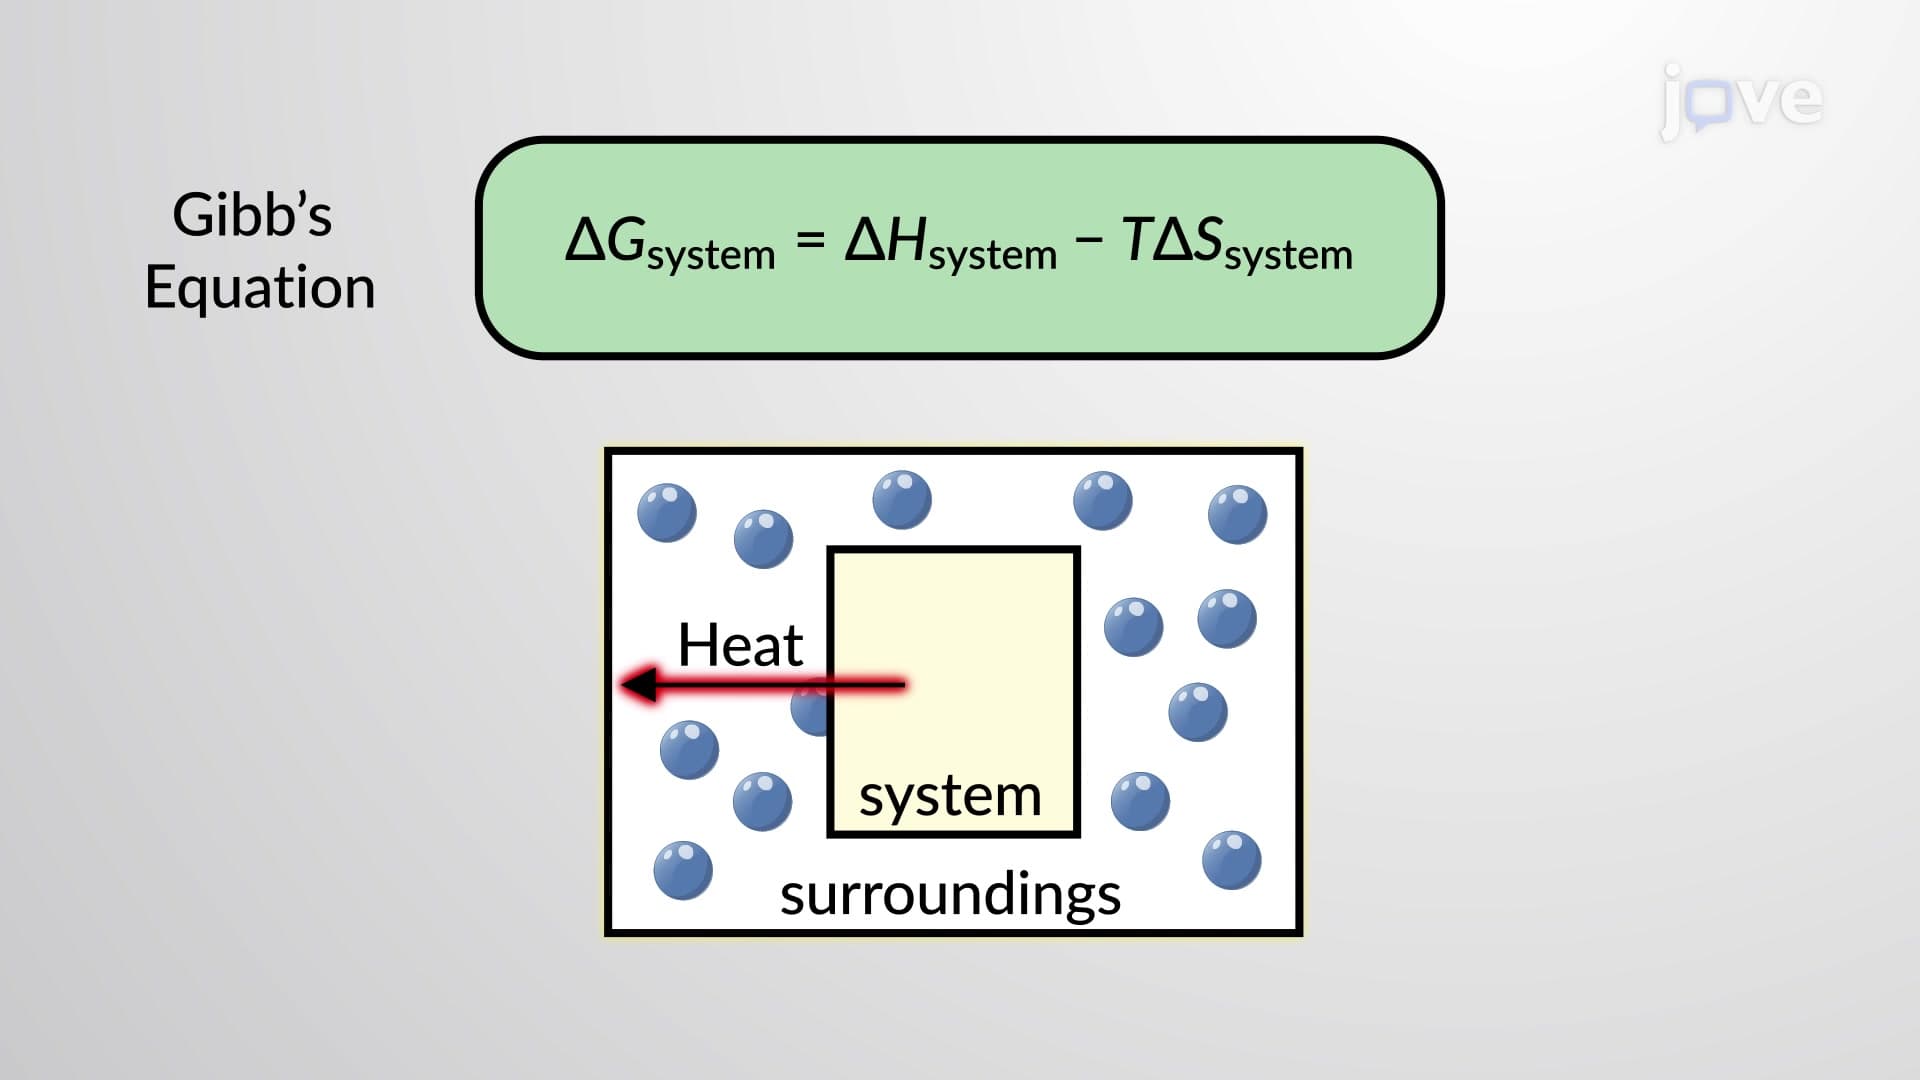 01:05
An Introduction to Free Energy
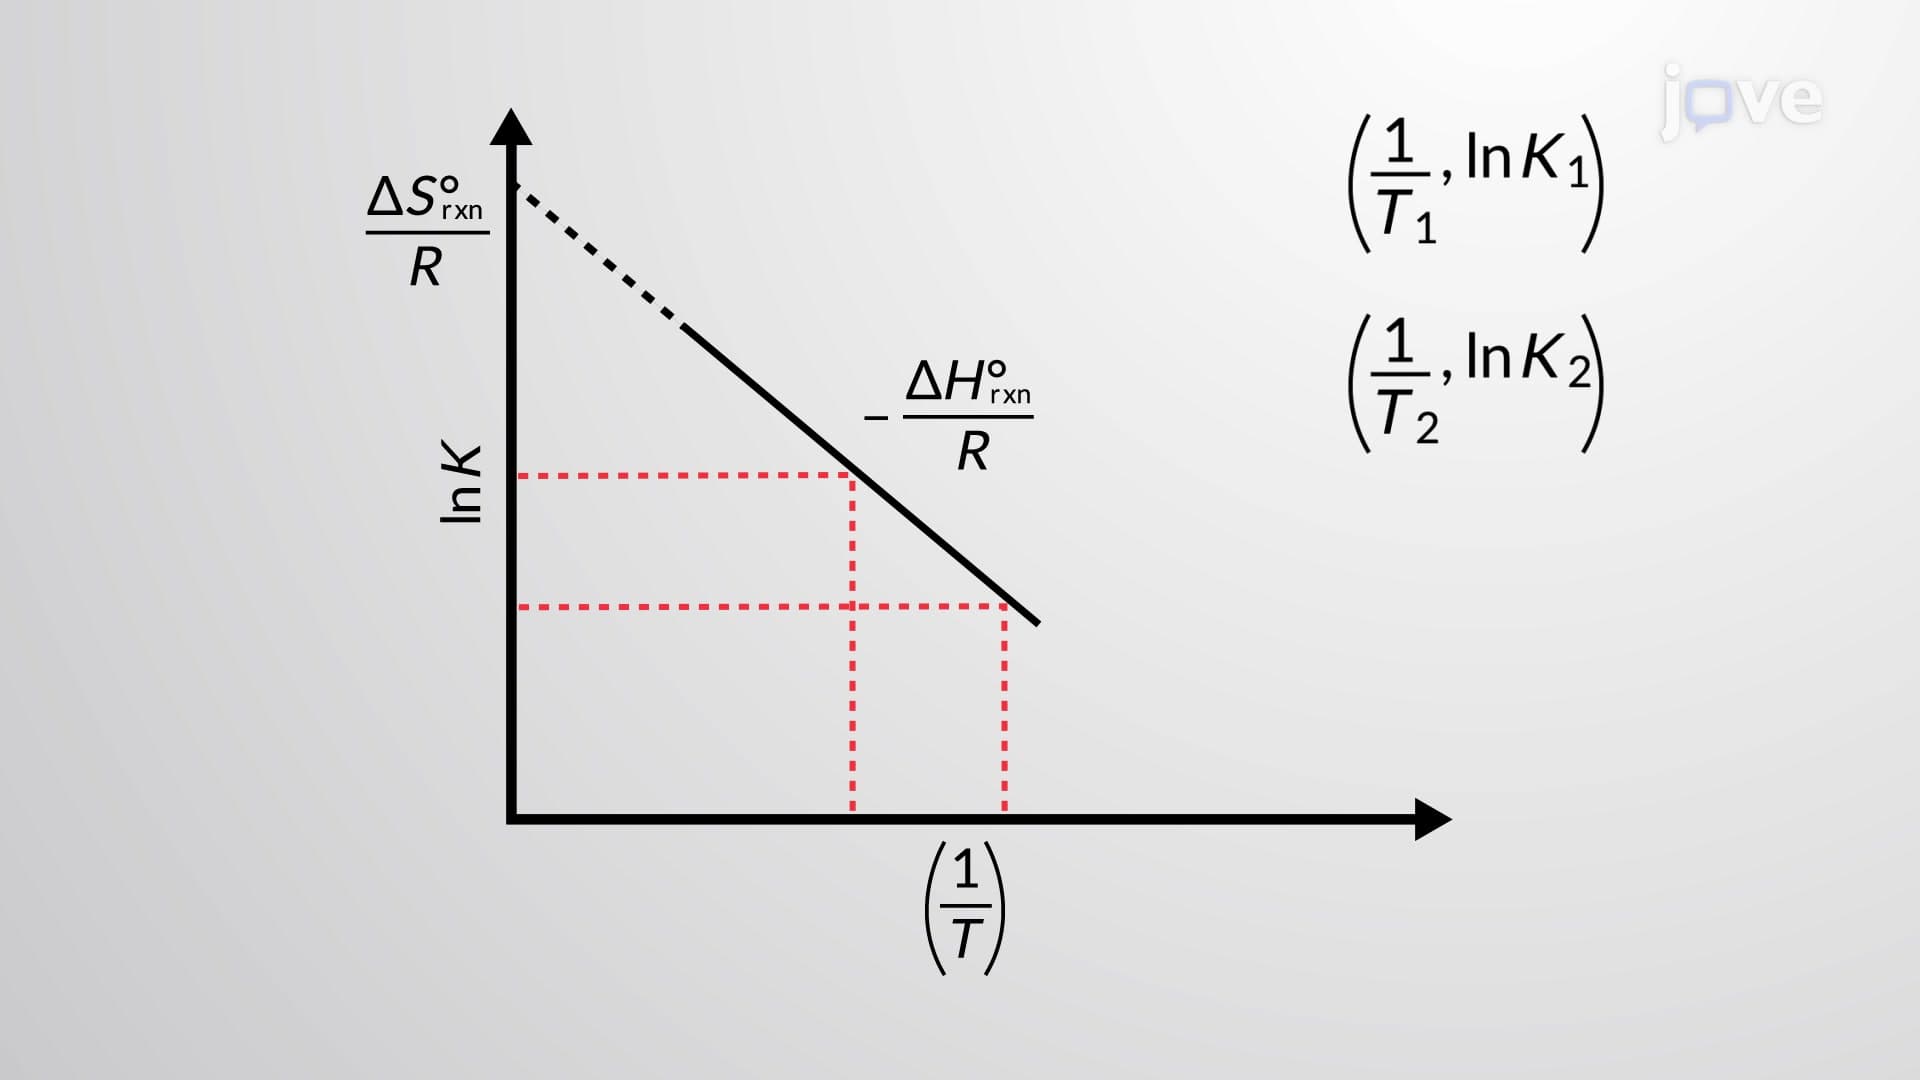 02:56
Free Energy and Equilibrium
Recall that Q is the numerical value of the mass action expression...
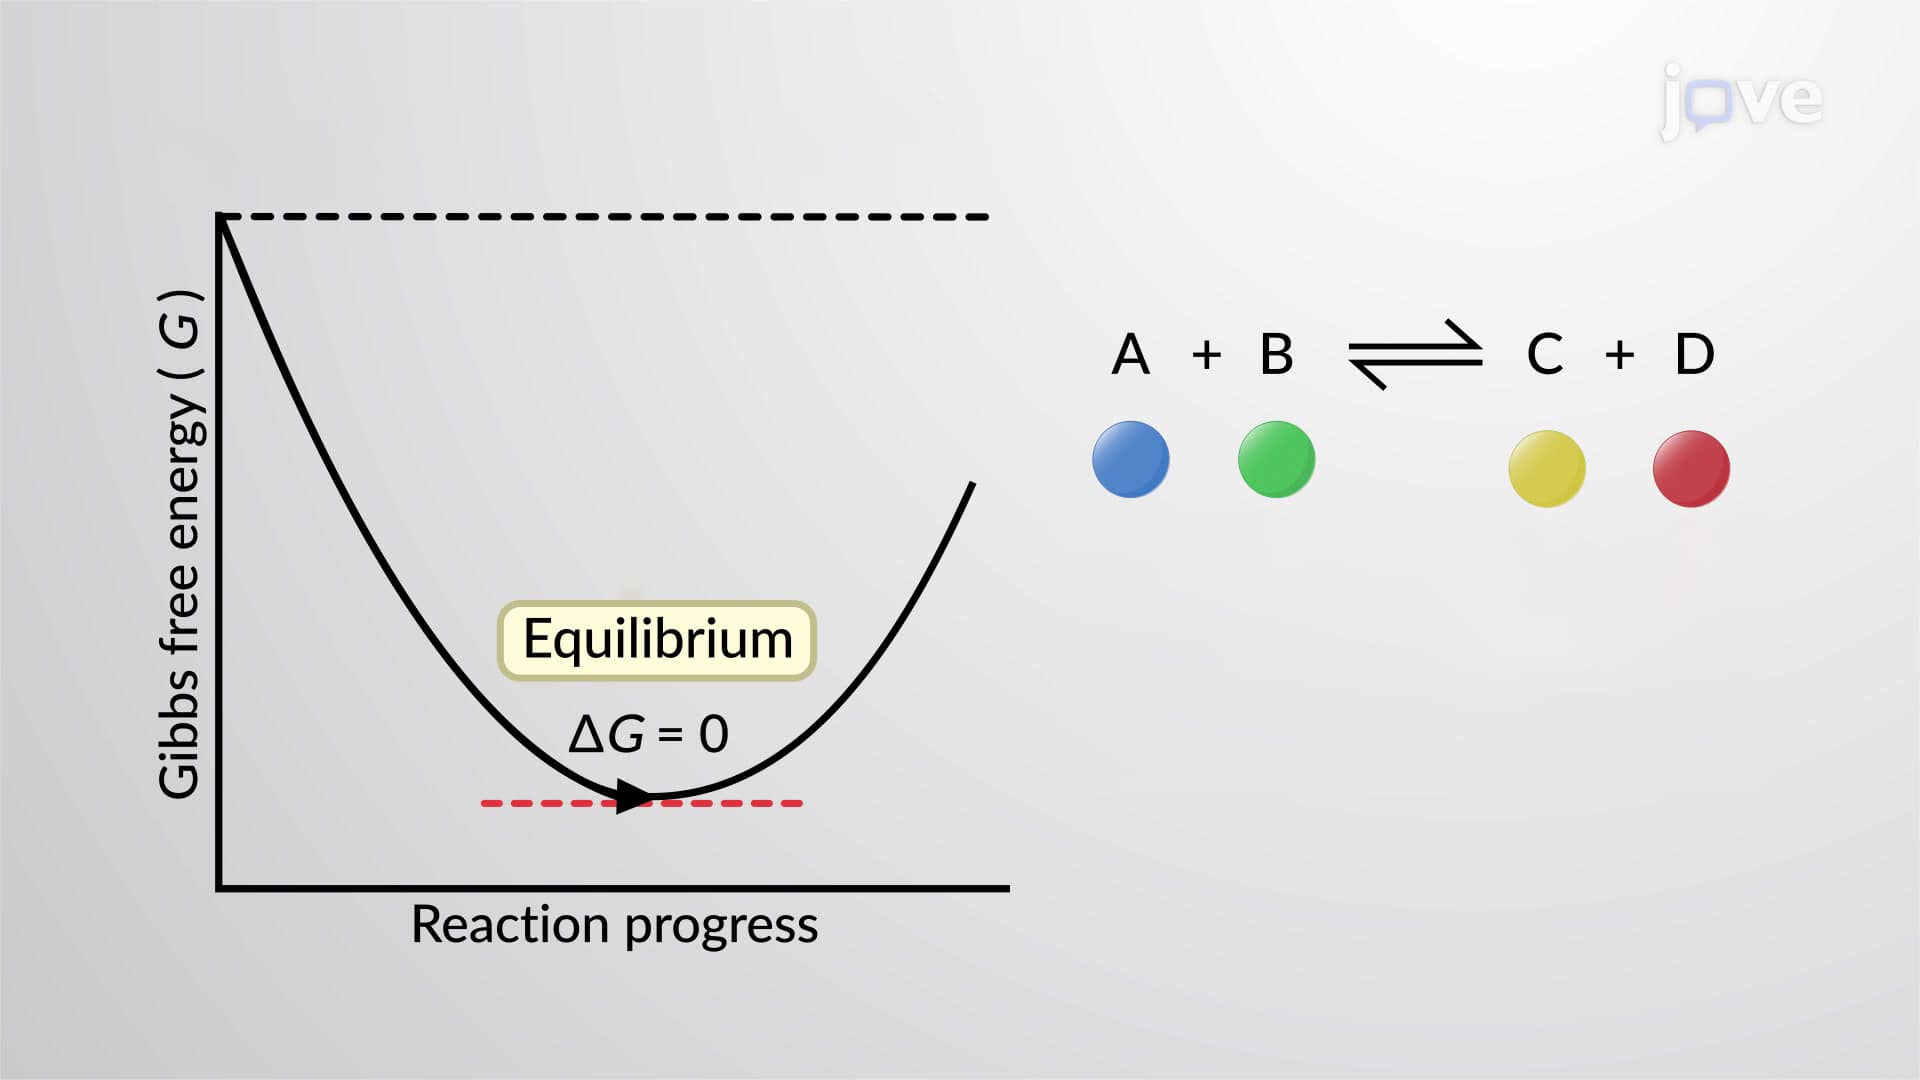 00:55
Free Energy and Equilibrium
The reaction quotient, Q, is a convenient measure of the status of an...
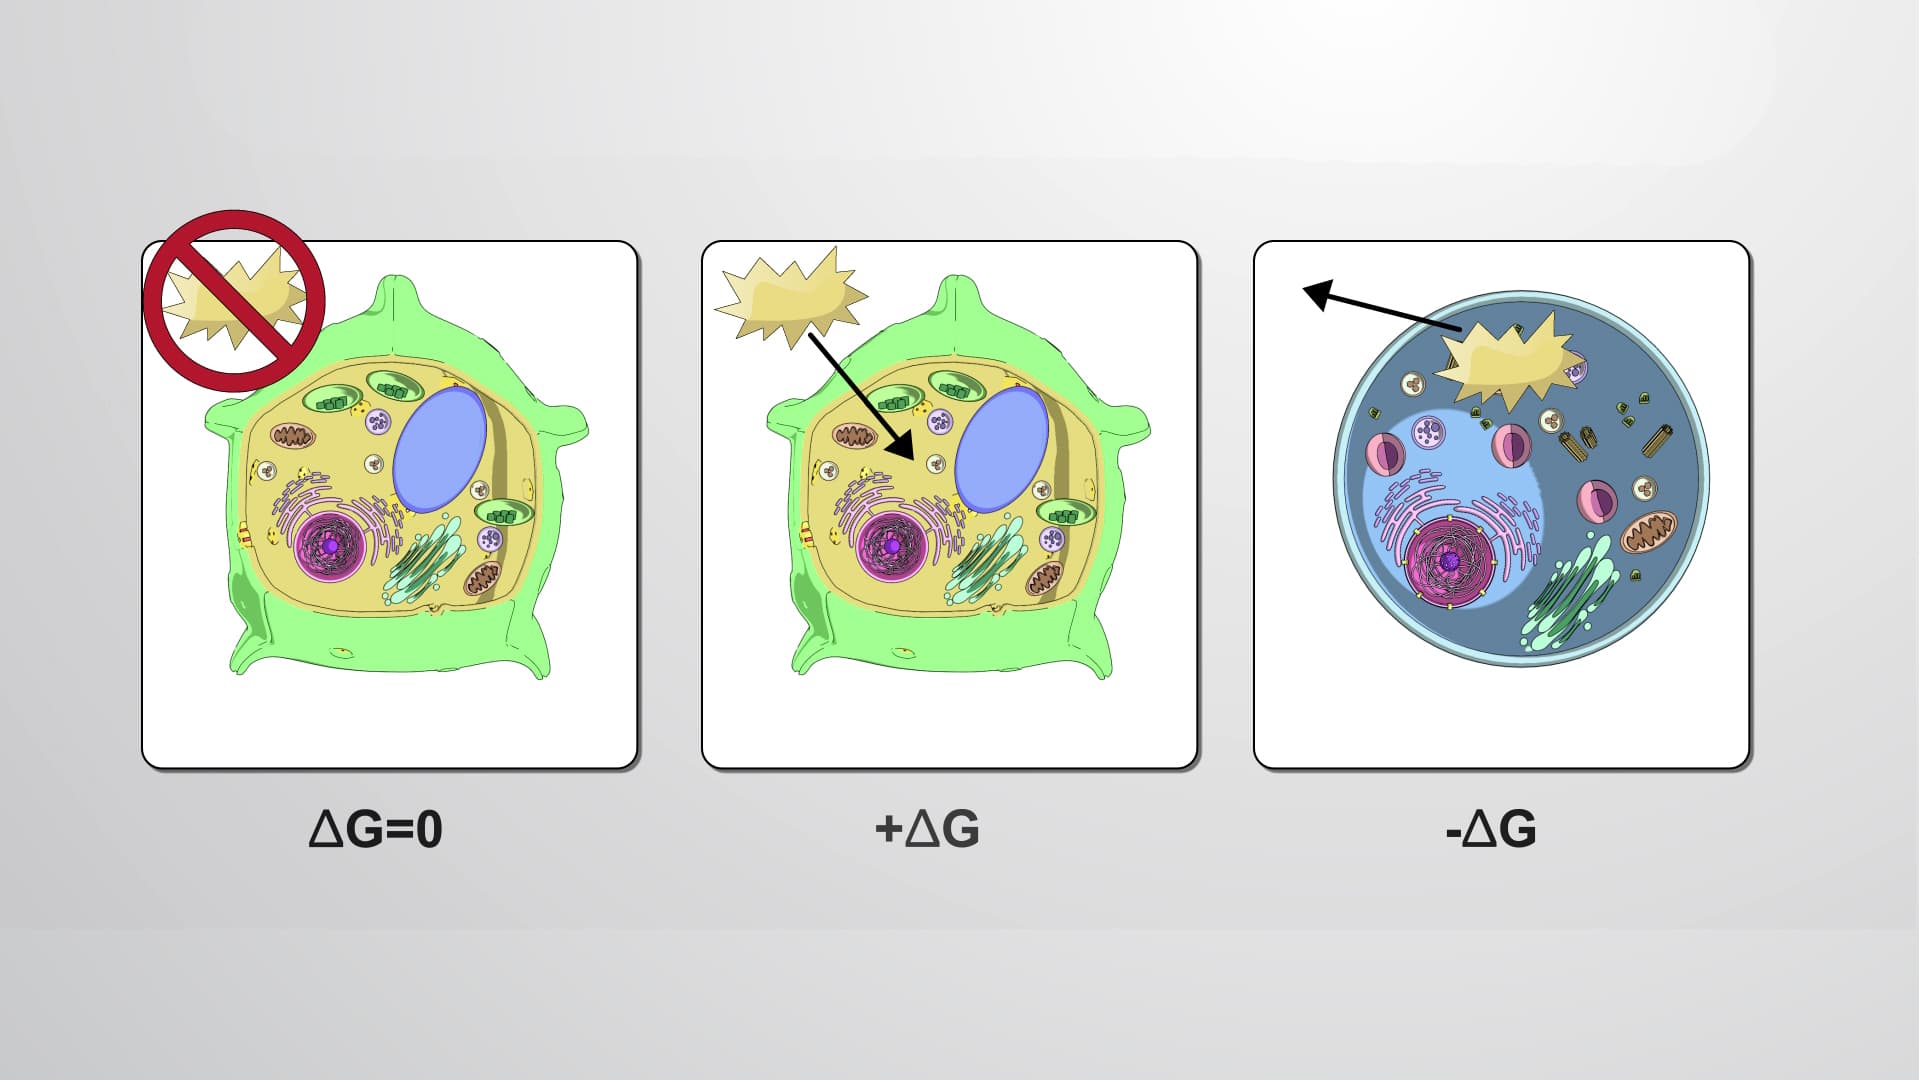 01:21
Free Energy
 02:39
Gibbs Free Energy
 02:23
Gibbs Free Energy and Thermodynamic Favorability