Related Experiment Video
Updated: Oct 7, 2026

Identification of Disease-related Spatial Covariance Patterns using Neuroimaging Data
Published on: June 26, 2013
Recovering house price trajectories from sparse transaction data using functional principal component analysis
Xiaolei Wang1,2, Naiming Xie1, Jiguo Cao2
1College of Economics and Management, Nanjing University of Aeronautics and Astronautics, Nanjing, Jiangsu, People's Republic of China.

Abstract:
In the real estate market, property prices are recorded only at the time of sale, leading to highly sparse transaction data. Recovering house price trajectories from such sparse data is therefore essential for accurate property valuation. This study models the latent price trajectory as functional data and applies functional principal component analysis (FPCA) to recover the underlying price trajectory. Real estate transaction data from the Kitsilano neighborhood in Vancouver is collected to validate the FPCA model. The first three eigenfunctions are employed to reconstruct the price trajectories, along with their corresponding confidence intervals. A 10-fold cross-validation procedure is conducted to assess the accuracy of the recovered trajectories. The results demonstrate that FPCA can reconstruct house price trajectories with high precision.
Related Concept Videos
 01:15
Scatter Plot
 01:14
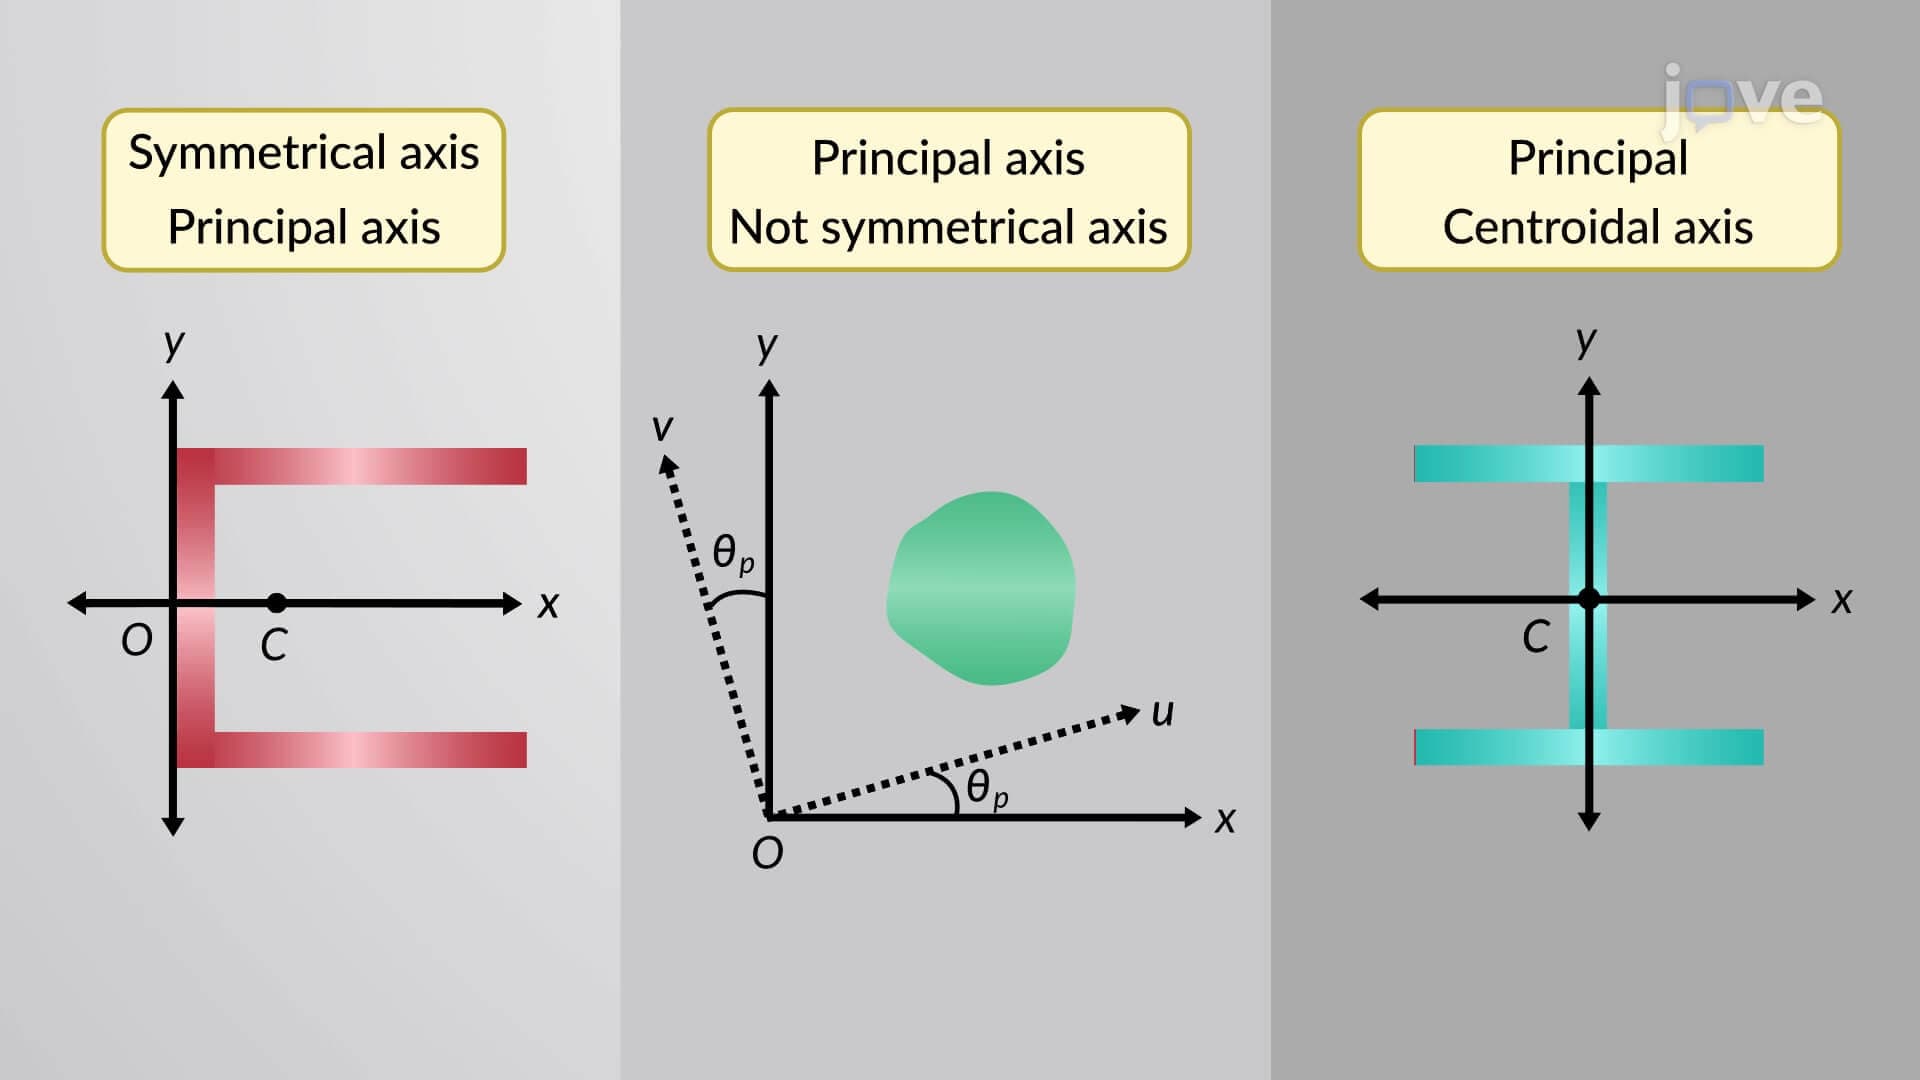
Principal Moments of Area
The principal moment of inertia axes are the...
 01:25
First Derivative Test: Problem Solving
 01:07
Residual Plots
When the residual values are plotted against the variable x, it is called a residual...
 01:14
Multicompartment Models: Overview
These models offer a more comprehensive representation of drug behavior in the body than one-compartment models. They accommodate the complexity of drug distribution,...
 00:59
Model-Independent Approaches for Pharmacokinetic Data: Noncompartmental Analysis
One important characteristic of noncompartmental analyses is that drug exposure increases proportionally with increasing doses. This relationship...