Sibuya probability distribution and numerical evaluation of fractional-order operators
Related Experiment Videos
Nikolai Leonenko1, Igor Podlubny2
1School of Mathematics, Cardiff University, Cardiff, CF 24 4AG United Kingdom.

Abstract:
In this work we explore the Sibuya probability distribution, which serves as the basis and the main instrument for numerical simulations of Grünwald-Letnikov fractional derivatives by the Monte Carlo method. We provide three methods for simulating the Sibuya distribution. We also introduce the Sibuya-like sieved probability distributions, and apply them to numerical fractional-order differentiation. Additionally, we use the Monte Carlo method for evaluating fractional-order integrals. The developed methods and tools are illustrated by examples of computation. We provide the MATLAB toolboxes for simulation of the Sibuya probability distribution, and for the numerical examples.
Related Concept Videos
 01:32
Probability Distributions
A discrete probability distribution is a probability distribution of discrete random variables. It can be categorized into binomial probability distribution and Poisson probability...
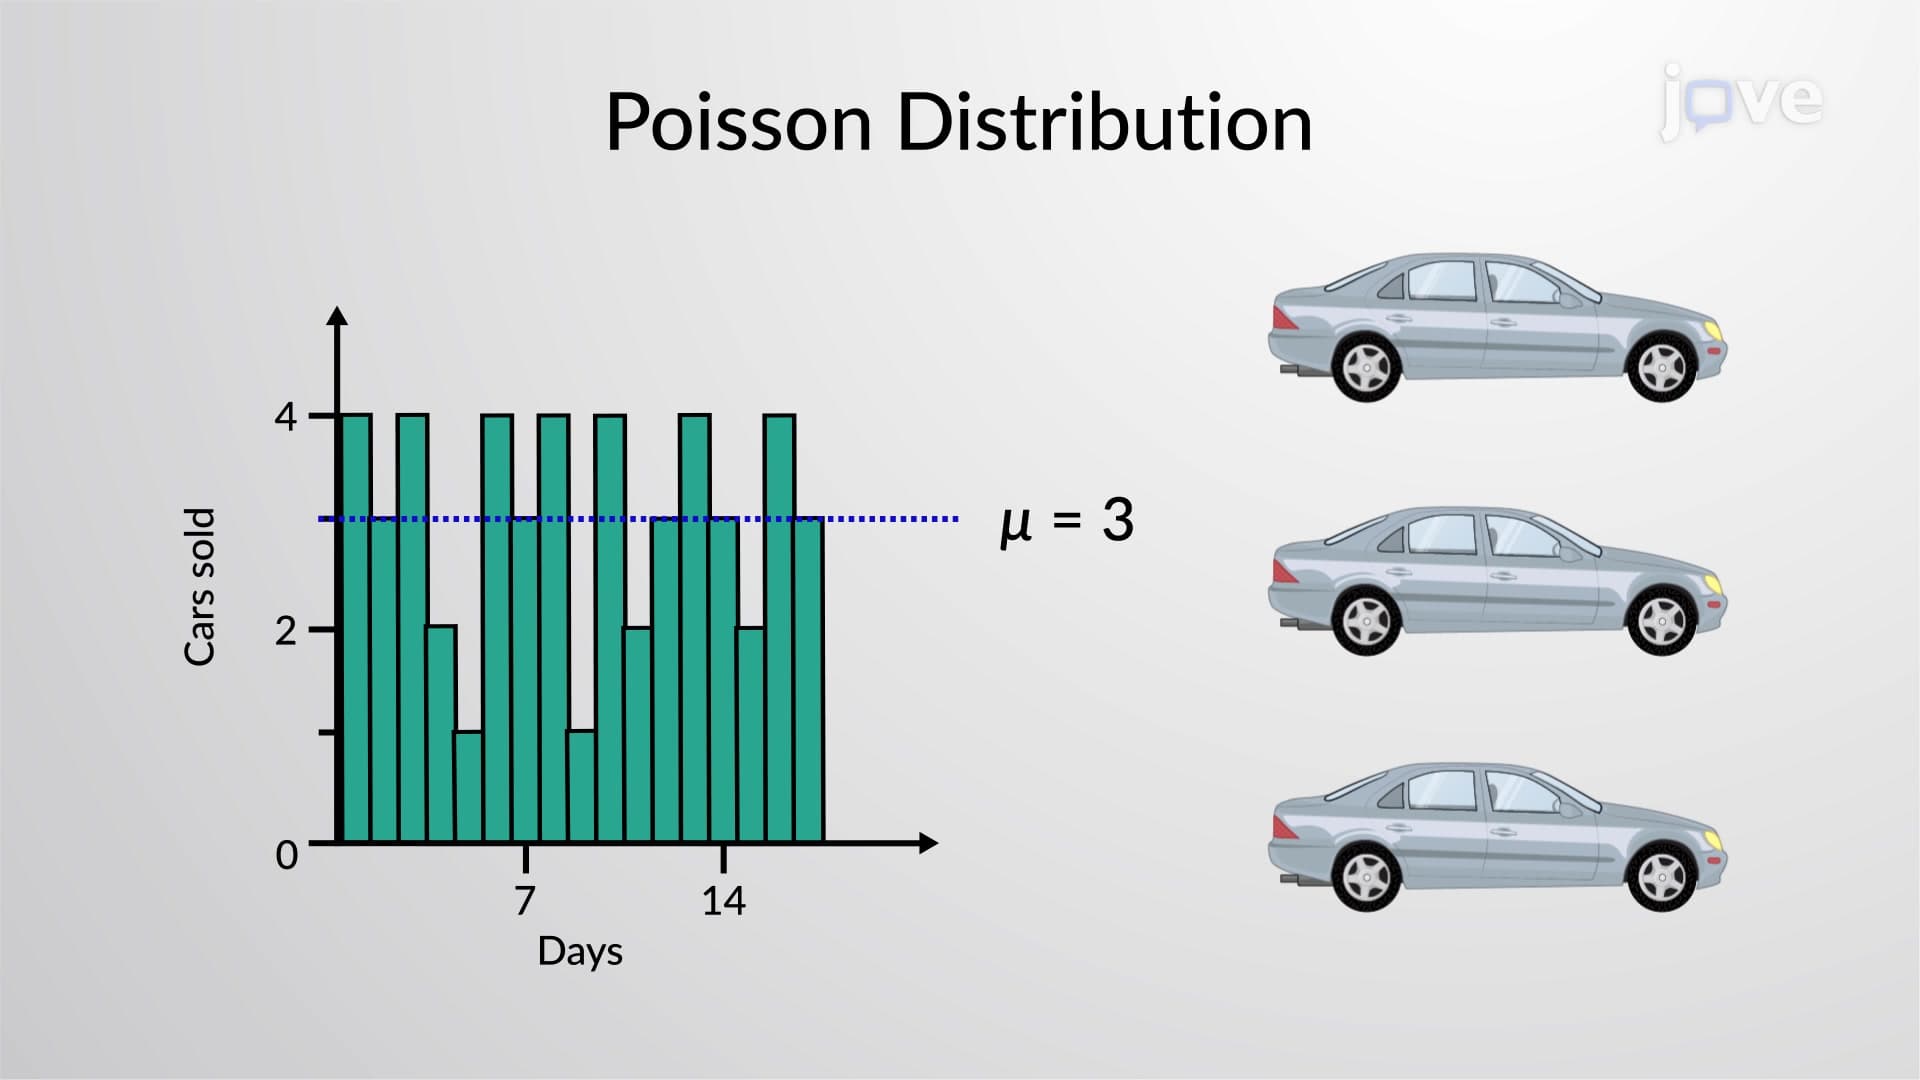 01:09
Poisson Probability Distribution
The...
 01:15
Binomial Probability Distribution
The outcomes of a binomial experiment fit a binomial probability distribution. A statistical experiment can be classified as a binomial experiment if the following conditions are met:
There are a fixed number of trials. Think of trials as repetitions of an experiment. The letter n denotes the number of trials.
There are only two possible outcomes,...
 01:17
Probability Histograms
 01:22
Second Derivatives and Laplace Operator
Consider a scalar function. The curl of its...
 01:27
Applications of Integration to Probability Density Functions